2026 ESPP: Unlocking Hidden Value for Tech Workers
Advertisements
Employee Stock Purchase Plans (ESPPs) in 2026 offer significant, often overlooked, financial advantages for tech workers, providing a unique avenue for wealth accumulation through discounted company stock purchases.
For tech professionals navigating the dynamic landscape of compensation and benefits, understanding The Hidden Value of 2026 Employee Stock Purchase Plans (ESPP): Insights for Tech Workers (INSIDER KNOWLEDGE) is paramount. These plans, often overshadowed by RSUs or stock options, represent a powerful, yet frequently underutilized, tool for significant wealth creation. This article delves deep into the mechanics, benefits, and strategic considerations for maximizing your ESPP in the coming year.
Understanding the Core Mechanics of 2026 ESPPs
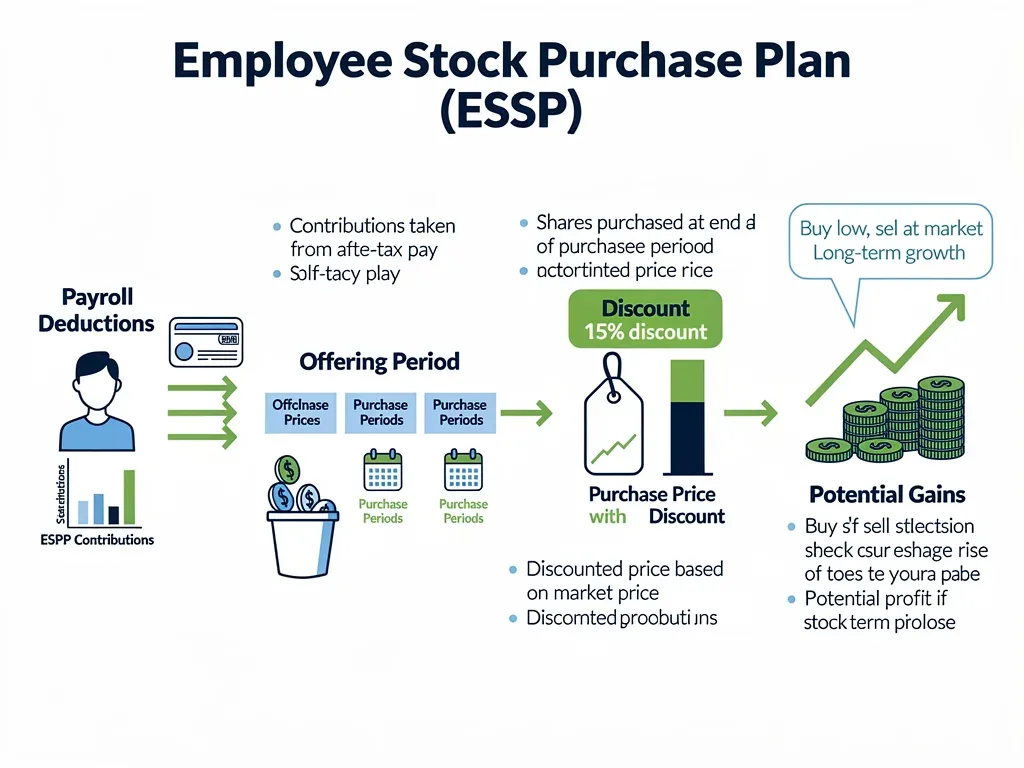
Employee Stock Purchase Plans (ESPPs) allow employees to buy company stock, often at a discount, through payroll deductions. This mechanism provides a built-in advantage, making it a compelling financial vehicle for many. The 2026 iterations of these plans continue to offer these fundamental benefits, though specific terms can vary widely by company.
Typically, an ESPP involves a defined offering period during which employees contribute funds, usually through post-tax payroll deductions. At the end of this period, often six months, the accumulated funds are used to purchase company stock. The key benefit lies in the discount, which can range from 5% to 15% below the market price, sometimes even lower if a ‘look-back’ provision is included.
The ‘Look-Back’ Provision: A Powerful Advantage
The ‘look-back’ provision is a game-changer within many ESPPs. It allows the purchase price to be based on the lower of the stock price at the beginning of the offering period or the end of the offering period, applying the discount to that lower price. This feature significantly reduces risk and enhances potential returns, especially in volatile markets.
- Reduced Risk: Protects against market downturns during the offering period.
- Enhanced Returns: Maximizes the discount by choosing the most favorable price point.
- Automatic Benefit: Often applied automatically, requiring no active decision-making from the employee.
- Market Volatility Buffer: Provides a cushion in unpredictable stock environments.
Understanding these core mechanics is the first step toward appreciating the substantial, often hidden, value that 2026 ESPPs can offer. Tech workers, with their typically higher discretionary income, are uniquely positioned to leverage these plans effectively, turning a standard benefit into a significant wealth-building opportunity.
Maximizing Your ESPP: Strategic Contributions and Selling
Simply participating in an ESPP is good, but strategically maximizing your contributions and understanding the optimal selling window can turn a good benefit into an exceptional one. For 2026, tech workers should evaluate their financial goals and risk tolerance to determine the best approach.
The maximum annual contribution to an ESPP is often capped by the IRS at $25,000 worth of stock at the time of the offering (before the discount). Many companies also set their own internal limits, usually a percentage of your salary. Contributing the maximum amount, if financially feasible, is often recommended due to the immediate, virtually risk-free gain from the discount.
Optimal Selling Strategies for ESPP Shares
When to sell your ESPP shares is a critical decision influenced by tax implications and personal financial goals. There are generally two main holding periods: a ‘disqualifying disposition’ and a ‘qualifying disposition.’
- Disqualifying Disposition: Selling shares less than two years from the offering date OR less than one year from the purchase date. The discount portion is taxed as ordinary income, and any additional gain is taxed as a short-term capital gain.
- Qualifying Disposition: Selling shares more than two years from the offering date AND more than one year from the purchase date. The discount portion is still taxed as ordinary income, but any additional gain is taxed as a long-term capital gain, which typically has a lower tax rate.
- Immediate Sale Strategy: For many tech workers, selling immediately after purchase (disqualifying disposition) is a popular strategy. This allows them to realize the guaranteed discount profit quickly and reinvest the funds elsewhere, minimizing exposure to company stock price fluctuations.
While the immediate sale forfeits the potential for long-term capital gains tax treatment on the discount, it provides immediate liquidity and reduces single-company stock concentration risk. The decision should align with your personal financial plan and risk appetite, considering the potential tax savings versus market exposure.
Navigating Tax Implications: Ordinary Income vs. Capital Gains
The tax treatment of ESPP shares is one of the most complex aspects, yet understanding it is crucial for maximizing net gains. For 2026, the fundamental tax rules remain consistent, but a clear grasp of ordinary income versus capital gains is essential for tech workers.
The discount you receive on ESPP shares is always considered a form of compensation. This means that, regardless of how long you hold the shares, the discount portion will eventually be taxed as ordinary income. The timing of this taxation, however, depends on whether it’s a qualifying or disqualifying disposition.
Understanding the Taxable Components
When you sell your ESPP shares, the IRS looks at two main components for taxation: the discount and any appreciation (or depreciation) in the stock’s value from the purchase date to the sale date. Properly accounting for these can make a significant difference in your tax liability.
- Discount as Ordinary Income: The difference between the fair market value of the stock on the purchase date and the discounted purchase price is always taxed as ordinary income. This amount is typically reported on your W-2.
- Capital Gains/Losses: Any gain or loss realized from the sale beyond the discount amount is treated as a capital gain or loss. This is where the distinction between short-term (taxed at ordinary income rates) and long-term (taxed at preferential rates) becomes critical.
- Basis Adjustment: It’s important to adjust your cost basis for tax reporting. Your cost basis for capital gains purposes is your purchase price plus the ordinary income recognized from the discount.
For tech workers, who often have higher incomes, minimizing ordinary income and maximizing long-term capital gains is a key objective. Careful planning around ESPP sales can help achieve this, potentially saving thousands in taxes. Consulting with a tax professional experienced in employee equity compensation is highly recommended to navigate these intricacies for 2026.
ESPPs vs. Other Equity Compensation: A Comparative View for 2026
Tech workers often receive a mix of equity compensation, including Restricted Stock Units (RSUs), stock options (ISOs or NSOs), and ESPPs. While each offers unique benefits, understanding how ESPPs stack up against these other forms in 2026 is vital for comprehensive financial planning.
Unlike RSUs, which are granted and vest over time, or stock options, which give the right to buy stock at a set price, ESPPs provide an immediate, guaranteed discount on company stock. This inherent discount makes ESPPs often the most straightforward and least risky form of equity compensation, assuming an immediate sale strategy.
Key Differentiators and Synergies
Each form of equity compensation serves a different purpose and carries different risk/reward profiles. Integrating ESPPs into a broader equity strategy can optimize overall financial outcomes.
- Risk Profile: ESPPs, especially with a ‘look-back’ and immediate sale, are generally considered low-risk due to the guaranteed discount. RSUs carry market risk but no strike price risk. Stock options have both market and strike price risk, offering higher potential upside but also higher potential loss.
- Liquidity: ESPPs often provide quick liquidity if shares are sold immediately after purchase. RSUs provide liquidity upon vesting. Stock options require exercising and then selling.
- Taxation: ESPPs involve ordinary income on the discount and then capital gains/losses. RSUs are taxed as ordinary income upon vesting. Stock options have complex tax rules depending on the type (ISO vs. NSO) and holding period.
For 2026, tech workers should view ESPPs as a foundational element of their equity compensation, providing a relatively low-risk, high-probability return. It can be used to diversify funds away from company stock, or as a source of capital for other investments, complementing the longer-term growth potential of RSUs and stock options.
Strategic Financial Planning with Your 2026 ESPP
Integrating your 2026 ESPP into a broader financial plan is key to transforming this benefit into a powerful wealth-building tool. This involves considering your overall investment portfolio, risk tolerance, and long-term financial goals.
Many tech workers accumulate a significant portion of their wealth in company stock through various equity programs. While company loyalty is commendable, over-concentration in a single stock, even your employer’s, can expose you to undue risk. ESPPs offer a unique opportunity to generate cash that can be immediately diversified.
Diversification and Reinvestment Strategies
The guaranteed discount from an ESPP, particularly with an immediate sale strategy, creates a predictable source of funds. This cash can then be strategically redeployed to reduce risk and enhance overall portfolio performance.
- Fund Emergency Savings: The consistent, albeit smaller, gains from ESPPs can be an excellent way to build or replenish an emergency fund without impacting your primary income.
- Diversify Investments: Reinvest the proceeds into a broad-market index fund, ETFs, or other diversified assets to reduce reliance on your company’s stock performance.
- Accelerate Debt Repayment: Use the ESPP profits to pay down high-interest debt, such as credit card balances or personal loans, improving your overall financial health.
- Contribute to Retirement Accounts: Funnel ESPP gains into your 401(k), IRA, or other retirement vehicles, leveraging tax advantages for long-term growth.
By treating your ESPP as a cash-generating mechanism rather than a long-term stock holding strategy, tech workers can systematically build wealth and achieve greater financial security. This approach minimizes market risk while maximizing the utility of the guaranteed discount.
Common Pitfalls and How to Avoid Them in 2026
While ESPPs offer significant advantages, certain pitfalls can diminish their value if not properly addressed. Being aware of these common mistakes can help tech workers fully capitalize on their 2026 ESPP benefits.
One of the most frequent errors is failing to participate at all, often due to a lack of understanding or perceived complexity. Another common pitfall is contributing too little, missing out on the full potential of the discounted stock purchase. Both scenarios result in leaving money on the table, a costly oversight for any financial plan.
Avoiding Suboptimal ESPP Management
Effective management of your ESPP involves more than just participation; it requires informed decisions throughout the entire cycle, from enrollment to sale.
- Ignoring the ‘Look-Back’ Provision: Not understanding or utilizing a ‘look-back’ provision means you might pay more for your shares than necessary, reducing your effective discount.
- Holding Shares Too Long (for some strategies): While holding for a qualifying disposition can offer tax benefits, holding shares for too long exposes you to unnecessary company-specific stock risk, especially if you already have substantial company equity.
- Not Understanding Tax Implications: Miscalculating the tax basis or failing to plan for the ordinary income component can lead to unexpected tax bills and reduce your net gains.
- Lack of Diversification: Allowing ESPP shares to accumulate and become a significant portion of your portfolio creates concentration risk. Always prioritize diversification.
For 2026, tech workers should make it a priority to thoroughly understand their company’s specific ESPP rules, consult with financial advisors, and establish a clear strategy for contributions, purchases, and sales. Proactive management can prevent these common pitfalls and ensure you fully realize the hidden value of your ESPP.
| Key Aspect | Brief Description |
|---|---|
| Guaranteed Discount | ESPPs typically offer a 5-15% discount on company stock, often with a ‘look-back’ provision for added value. |
| Tax Implications | Discount is taxed as ordinary income; additional gains are short-term or long-term capital gains based on holding period. |
| Strategic Selling | Immediate sale after purchase can minimize risk and provide quick cash for diversification or debt repayment. |
| Wealth Building | Leverage ESPP gains for emergency funds, diversified investments, or accelerating financial goals. |
Frequently Asked Questions About 2026 ESPPs
What is the primary benefit of a 2026 Employee Stock Purchase Plan (ESPP)?▼The primary benefit of a 2026 ESPP is the ability to purchase company stock at a significant discount, typically between 5% and 15% off the market price. Many plans also include a ‘look-back’ provision, further enhancing this discount and providing an almost immediate, low-risk return on investment for tech workers.
How does the ‘look-back’ provision work in an ESPP?▼A ‘look-back’ provision allows the purchase price of the stock to be based on the lower of the stock’s price at the beginning of the offering period or at the end of the offering period. The discount is then applied to this lower price, providing a built-in safeguard against market declines and maximizing your potential profit.
What are the tax implications of selling ESPP shares immediately after purchase?▼Selling ESPP shares immediately (a disqualifying disposition) means the discount portion is taxed as ordinary income. Any additional gain from the purchase price to the sale price is taxed as a short-term capital gain. This strategy is popular for its low risk and quick access to funds, despite the higher tax rate on gains.
Should tech workers always contribute the maximum to their ESPP?▼While contributing the maximum to an ESPP is often advisable due to the guaranteed discount, it depends on individual financial circumstances. It’s crucial to ensure you have an adequate emergency fund and are not over-concentrating your investments in a single company’s stock. Financial planning should guide this decision.
How can ESPPs be used for broader financial planning?▼ESPPs can serve as a robust tool for financial planning. The profits generated can be used to build emergency savings, pay down high-interest debt, diversify your investment portfolio into other asset classes, or contribute to long-term retirement accounts. They offer a flexible source of capital for various financial goals.
Conclusion
In conclusion, the 2026 Employee Stock Purchase Plans (ESPPs) represent a significant, yet often underestimated, financial advantage for tech workers. By understanding the core mechanics, strategically maximizing contributions, navigating the nuanced tax implications, and integrating ESPPs into a comprehensive financial plan, employees can unlock substantial hidden value. Avoiding common pitfalls through informed decisions and proactive management ensures that this powerful benefit translates directly into tangible wealth creation and enhanced financial security. For tech professionals, an ESPP is more than just an employee perk; it is a strategic financial instrument deserving of careful consideration and optimized utilization.