Refinancing Your Home in 2026: A Data-Driven Analysis
Advertisements
A data-driven analysis for 2026 indicates that refinancing your home can be a strategic financial decision, potentially yielding significant savings and enhanced financial flexibility based on prevailing market conditions and individual homeowner profiles.
As we approach 2026, many homeowners are contemplating a crucial financial question: is refinancing your home worth it in 2026? A data-driven analysis of potential savings (comparison/analysis) reveals a complex landscape shaped by evolving economic indicators, interest rate forecasts, and individual financial goals. This decision, far from being a simple one, demands a thorough examination of current market trends and personalized financial projections to truly understand its potential impact on your long-term wealth.
Understanding the 2026 Economic Landscape for Refinancing
The economic climate of 2026 is poised to be a significant determinant in the viability of home refinancing. Global economic shifts, domestic monetary policies, and inflationary pressures all play a role in shaping interest rates. For homeowners, understanding these broader trends is the first step in evaluating whether a refinance will truly deliver the anticipated savings. The Federal Reserve’s actions, in particular, will bear heavily on the cost of borrowing.
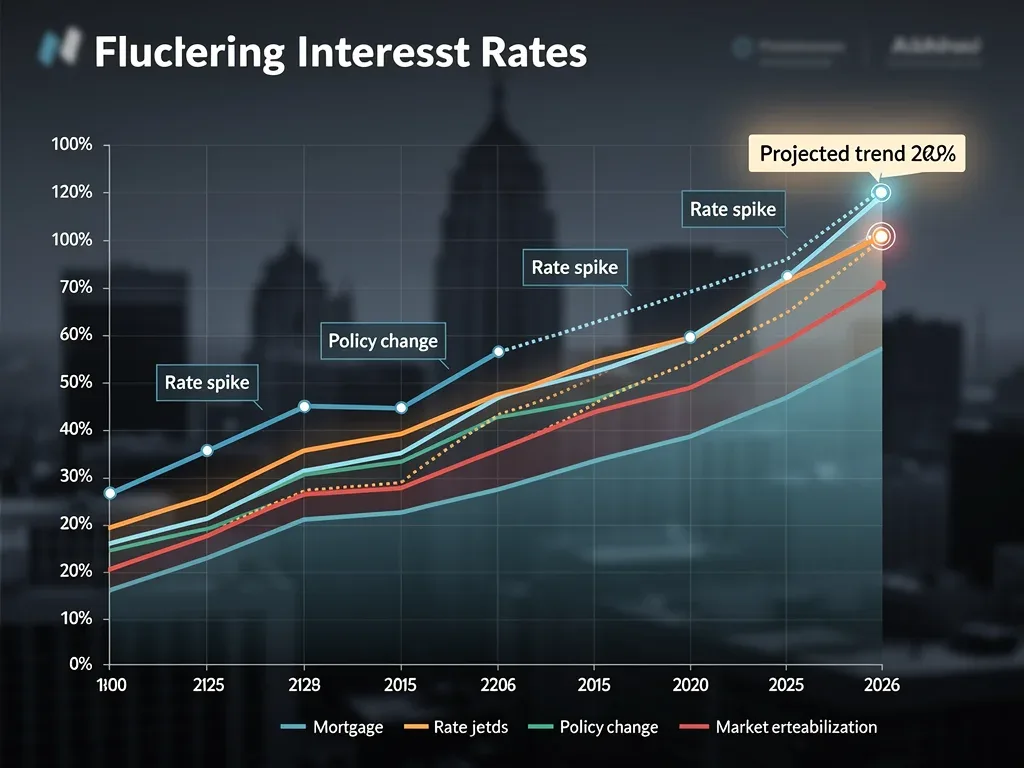
Analysts project a nuanced interest rate environment for 2026. While some anticipate a stabilization or slight decrease in rates following periods of volatility, others foresee continued upward pressure due to persistent inflation or robust economic growth. These projections, though not guarantees, provide a framework for homeowners to assess their potential savings. A lower interest rate environment typically makes refinancing more attractive, as it directly translates to reduced monthly mortgage payments and overall interest paid over the loan’s lifetime.
Key Economic Indicators to Monitor
- Inflation Rates: Persistent inflation often prompts central banks to raise interest rates to cool down the economy, making refinancing less appealing.
- Federal Reserve Policy: The Fed’s stance on interest rates, particularly the federal funds rate, directly influences mortgage rates.
- Employment Data: Strong employment figures can indicate a robust economy, which might lead to higher interest rates if inflationary concerns arise.
- Housing Market Stability: A stable housing market can provide a good foundation for refinancing, ensuring property values support loan-to-value ratios.
Ultimately, the decision to refinance in 2026 will hinge on a careful observation of these macroeconomic factors. Staying informed about economic forecasts and how they might impact mortgage rates is crucial for any homeowner considering this financial move. A well-timed refinance can lock in substantial savings, but a misstep could lead to increased costs or minimal benefit.
Analyzing Current Mortgage Interest Rates and Projections
The core of any refinancing decision lies in the prevailing mortgage interest rates. As we look towards 2026, projections from various financial institutions offer a mixed, yet insightful, outlook. These projections are vital for homeowners to gauge the potential for securing a lower rate than their current mortgage. Understanding the trajectory of these rates can help in timing a refinance application effectively.
Expert consensus, while not absolute, suggests that interest rates in 2026 might hover within a range that could still offer opportunities for savings, especially for those with older mortgages at significantly higher rates. However, it’s equally plausible that rates could tick up, making the window for substantial savings narrower. This uncertainty underscores the importance of a dynamic approach to monitoring the market.
Factors Influencing Rate Projections
- Global Geopolitical Events: International conflicts or political instability can introduce volatility into financial markets, affecting interest rates.
- Technological Advancements: Innovations in lending technology could streamline the refinancing process, potentially influencing competitiveness among lenders.
- Consumer Demand: High demand for housing or refinancing can sometimes lead to slight increases in rates as lenders manage their portfolios.
It’s important for homeowners not to solely focus on the lowest possible rate but to consider the overall financial picture. Even a seemingly small reduction in interest rate can translate into thousands of dollars in savings over the life of a loan. Therefore, a comprehensive comparison of current rates against personal loan terms is essential. This careful analysis allows homeowners to make an informed decision that aligns with their financial objectives.
Calculating Your Potential Savings: A Data-Driven Approach
The most compelling reason to refinance is often the prospect of significant financial savings. However, these savings are not guaranteed and require a detailed, data-driven calculation. Homeowners must move beyond mere assumptions and delve into the specifics of their current mortgage versus potential new loan terms to ascertain the true benefit of refinancing in 2026. This involves understanding various cost components and how they interact.
A crucial step is to compare your current interest rate and monthly payment with what a new refinance loan could offer. Even a half-percentage point reduction can lead to substantial savings over decades. Moreover, consider the total interest paid over the life of the loan. A shorter loan term, even with a slightly higher monthly payment, can drastically reduce the total interest, freeing up equity faster.
Key Data Points for Calculation
- Current Mortgage Balance: The outstanding principal on your existing loan.
- Current Interest Rate: Your existing mortgage’s annual interest rate.
- New Proposed Interest Rate: The rate offered by potential lenders for a refinance.
- Closing Costs: The fees associated with originating a new loan, which can range from 2% to 5% of the loan amount.
- Time Horizon: How long you plan to stay in the home, as this affects the break-even point for closing costs.
To accurately calculate potential savings, homeowners should use online refinance calculators or consult with a financial advisor. These tools can help factor in closing costs, which can significantly eat into initial savings. The goal is to determine the ‘break-even point’ – the time it takes for the savings from a lower monthly payment to offset the closing costs. If you plan to move before reaching this point, refinancing might not be financially advantageous. A meticulous calculation ensures that the decision is based on solid financial data, not just hopeful projections.
Understanding Different Refinancing Options in 2026
Refinancing isn’t a one-size-fits-all solution; there are several types, each catering to different financial objectives. In 2026, homeowners will continue to have access to these options, and understanding their nuances is critical for selecting the most suitable path. The choice depends on individual goals, whether it’s lowering monthly payments, reducing the loan term, or accessing home equity.
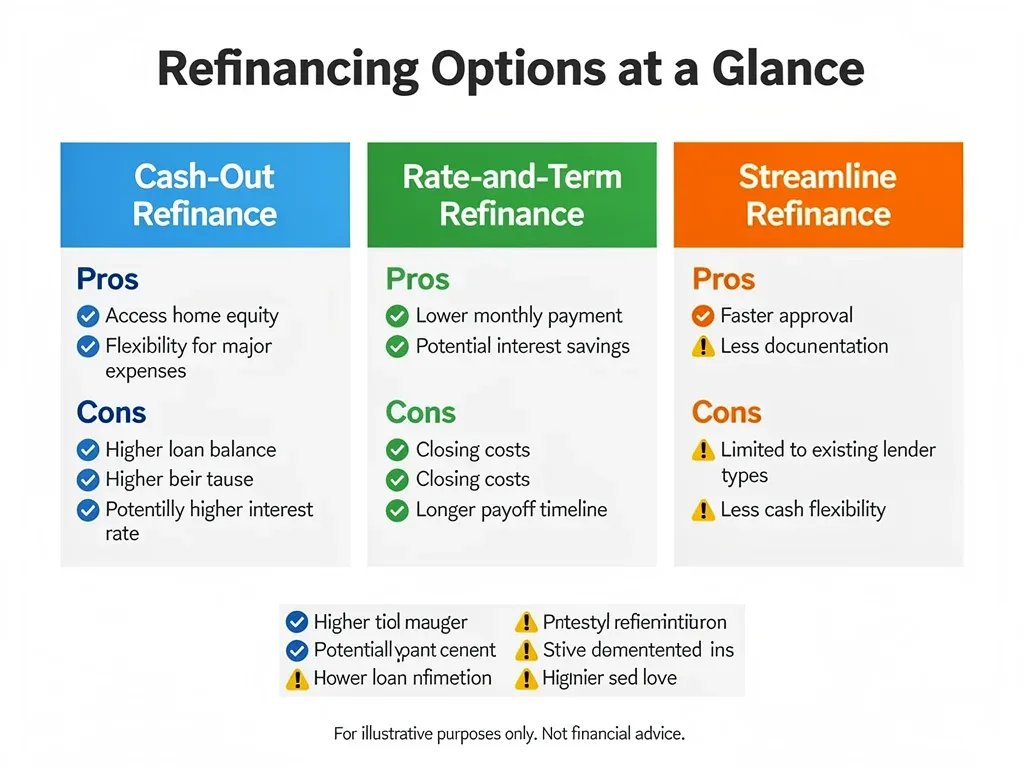
The most common type is a rate-and-term refinance, aimed at securing a lower interest rate or changing the loan term. This can lead to significant monthly savings or faster equity build-up. Another popular option is a cash-out refinance, which allows homeowners to tap into their home equity for other financial needs, such as home improvements, debt consolidation, or investments.
Common Refinancing Options
- Rate-and-Term Refinance: Primarily focuses on reducing the interest rate and/or changing the loan term (e.g., from 30 years to 15 years).
- Cash-Out Refinance: Allows homeowners to borrow against their home equity, receiving a lump sum of cash at closing.
- Streamline Refinance (FHA, VA, USDA): Often requires less paperwork and can be faster, typically for government-backed loans where the borrower already has that loan type.
- Cash-In Refinance: Involves bringing cash to the closing table to reduce the principal loan amount, potentially securing a better interest rate or removing private mortgage insurance (PMI).
Each option comes with its own set of eligibility requirements, closing costs, and potential benefits. For instance, while a cash-out refinance provides immediate liquidity, it also increases the principal balance and potentially the monthly payment. Conversely, a streamline refinance might offer a simpler process but could have specific limitations. Homeowners should carefully evaluate their financial situation and consult with lenders to determine which refinancing option best aligns with their goals for 2026.
The Role of Credit Score and Home Equity in 2026 Refinancing
Beyond market conditions, two personal financial factors significantly influence the success and terms of a refinance: your credit score and home equity. Lenders in 2026 will continue to scrutinize these elements to assess risk and determine eligibility. A strong credit profile and substantial home equity can open doors to the most favorable refinancing rates and terms, maximizing potential savings.
A higher credit score signals to lenders that you are a reliable borrower, often resulting in lower interest rates. Conversely, a lower credit score might lead to higher rates or even outright denial of a refinance application. It’s advisable for homeowners to review and, if necessary, improve their credit score well in advance of applying for a refinance. This proactive approach can yield significant financial benefits.
Impact of Credit Score and Equity
- Credit Score: A FICO score of 740 or higher generally qualifies for the best rates. Lower scores may still qualify but at higher rates.
- Home Equity: Lenders typically require a certain percentage of equity (e.g., 20%) to approve a refinance without requiring private mortgage insurance (PMI).
- Debt-to-Income Ratio (DTI): This ratio, comparing your monthly debt payments to your gross monthly income, is another critical factor lenders consider.
Home equity, the difference between your home’s market value and your outstanding mortgage balance, is equally vital. Sufficient equity not only helps you avoid PMI but can also provide leverage for a cash-out refinance. In a healthy housing market, rising property values can naturally increase your equity, making refinancing more attractive. Therefore, assessing your home’s current market value and your credit health are indispensable steps in preparing for a 2026 refinance. These personal financial pillars are as important as external market conditions in determining the overall worth of refinancing your home.
Navigating the Refinancing Process and Avoiding Pitfalls
Even with favorable market conditions and a strong financial profile, the refinancing process itself can be complex. Understanding the steps involved and being aware of common pitfalls can save homeowners time, money, and stress. A well-prepared approach to refinancing in 2026 will involve meticulous planning and careful consideration of all associated costs and legalities.
The process typically begins with gathering necessary financial documents, such as pay stubs, tax returns, and bank statements. Subsequently, homeowners will apply with multiple lenders to compare offers, focusing not just on the interest rate but also on closing costs and other fees. Transparency from lenders is key, and homeowners should not hesitate to ask questions about any charges they don’t understand.
Common Pitfalls to Avoid
- Ignoring Closing Costs: These fees can significantly reduce your net savings if not properly factored into your break-even analysis.
- Not Shopping Around: Settling for the first offer can mean missing out on better rates and terms from other lenders.
- Miscalculating the Break-Even Point: Refinancing might not be worth it if you plan to move before recovering your closing costs.
- Overlooking Prepayment Penalties: Some existing mortgages have penalties for early payoff, which can negate refinance savings.
- Impacting Your Credit Score: Multiple hard credit inquiries within a short period can temporarily lower your score, although typically grouped for mortgage shopping.
Furthermore, homeowners should be wary of predatory lending practices and ensure they are working with reputable institutions. Reading all loan documents carefully, including the fine print, is paramount. The goal is to secure a refinance that truly benefits your financial situation without introducing unforeseen burdens. By navigating the process diligently and avoiding these common pitfalls, homeowners can successfully leverage refinancing to their advantage in 2026.
Long-Term Financial Planning with Refinancing in Mind
Refinancing should not be viewed as an isolated transaction but rather as an integral part of a broader long-term financial strategy. For 2026, homeowners considering this move should assess how it aligns with their overall financial objectives, including retirement planning, wealth accumulation, and debt management. A strategic refinance can significantly bolster these goals, while a haphazard one could derail them.
One primary long-term benefit is the potential to free up cash flow through lower monthly payments. This extra capital can then be directed towards other investments, retirement accounts, or paying down higher-interest debt. Alternatively, opting for a shorter loan term, even if it means slightly higher monthly payments, can lead to faster debt elimination and substantial interest savings over the long run, accelerating equity build-up.
Integrating Refinancing into Your Financial Plan
- Debt Consolidation: A cash-out refinance can be used to pay off high-interest credit card debt or personal loans, simplifying finances.
- Investment Opportunities: Lower mortgage payments can free up funds for stock market investments, real estate, or other wealth-building avenues.
- Retirement Savings: The increased cash flow can be channeled into 401(k)s, IRAs, or other retirement vehicles to secure your future.
- Home Improvements: Using cash-out funds for renovations can increase home value, providing a return on investment.
Ultimately, the decision to refinance in 2026 should be a deliberate one, made after careful consideration of its ripple effects across your entire financial landscape. It’s an opportunity to optimize your mortgage, reduce your financial burden, and reallocate resources towards achieving your long-term goals. Consulting with a financial planner can provide invaluable guidance, ensuring that your refinancing decision contributes positively to your overall financial well-being and future aspirations.
| Key Point | Brief Description |
|---|---|
| 2026 Economic Outlook | Interest rates likely to be influenced by inflation and Fed policy; careful monitoring is essential. |
| Potential Savings Calculation | Compare current vs. new rates, factor in closing costs, and determine your break-even point. |
| Refinancing Options | Rate-and-term, cash-out, and streamline are common options, each serving different financial goals. |
| Credit & Equity Impact | Strong credit scores and sufficient home equity are crucial for securing favorable refinance terms. |
Frequently Asked Questions About Refinancing in 2026
What are the primary benefits of refinancing my home in 2026?▼The primary benefits often include securing a lower interest rate, which reduces monthly payments and total interest paid over time. It can also allow you to shorten your loan term or access home equity through a cash-out refinance for other financial needs.
How do I determine if refinancing is financially advantageous for me?▼To determine financial advantage, compare your current mortgage terms with potential new offers. Calculate the break-even point by dividing closing costs by your monthly savings. If you plan to stay in your home beyond this point, it’s likely beneficial.
What role does my credit score play in getting a good refinance rate?▼Your credit score is crucial. A higher score (typically 740+) signals lower risk to lenders, qualifying you for the best interest rates. A lower score might still allow refinancing but usually comes with higher rates, impacting overall savings.
Are there any hidden costs associated with home refinancing?▼Yes, refinancing involves closing costs, which can include appraisal fees, origination fees, title insurance, and attorney fees. These typically range from 2% to 5% of the loan amount and should be factored into your savings calculations.
When is the best time to consider a cash-out refinance?▼A cash-out refinance is best considered when you have substantial home equity and a clear purpose for the funds, such as high-return home improvements, debt consolidation, or significant investments, and when interest rates are favorable.
Conclusion
Deciding whether is refinancing your home worth it in 2026? A data-driven analysis of potential savings (comparison/analysis) indicates that it remains a powerful financial tool for homeowners, provided it’s approached with careful consideration and thorough research. The economic landscape, evolving interest rates, personal financial health, and the specific type of refinance chosen all play critical roles in determining its value. By diligently analyzing market trends, calculating potential savings, understanding the various options, and preparing personal finances, homeowners can make an informed decision that aligns with their long-term financial goals. Refinancing in 2026 could indeed unlock significant savings and improve financial stability, making it a worthwhile endeavor for many.