Maximize 2026 HSA Benefits: Unlock a $1,000 Annual Advantage
Advertisements
Maximizing your 2026 Health Savings Account (HSA) benefits can unlock a significant $1,000 annual financial advantage through strategic contributions, eligible expense utilization, and investment growth, offering triple tax benefits for healthcare and retirement.
Are you ready to truly understand and leverage the power of your Health Savings Account? In 2026, the opportunity to maximize your 2026 Health Savings Account (HSA) benefits could mean unlocking a substantial $1,000 annual financial advantage, impacting both your immediate healthcare costs and your long-term financial security.
Understanding the 2026 HSA Landscape: What’s New?
The landscape of healthcare savings evolves annually, and 2026 brings specific adjustments to Health Savings Accounts that every eligible individual should be aware of. Staying informed about these changes is crucial for optimizing your contributions and ensuring you fully capitalize on the unique tax advantages an HSA offers.
HSAs remain a powerful tool for those enrolled in a High-Deductible Health Plan (HDHP), providing a tax-advantaged way to save for medical expenses. For 2026, understanding the updated contribution limits and eligibility criteria is the first step toward maximizing your benefits. These accounts aren’t just for current medical costs; they’re a versatile financial instrument for future healthcare needs and even retirement planning.
Key Adjustments for 2026
Each year, the IRS makes inflation-adjusted changes to HSA contribution limits and HDHP requirements. These adjustments directly influence how much you can save and who qualifies. It’s essential to consult official IRS guidelines or a trusted financial advisor to confirm the precise figures for 2026 as they become available, but anticipating these changes allows for proactive planning.
- Increased Contribution Limits: Expect a slight increase in the maximum allowable contributions for both individuals and families, reflecting inflationary trends.
- Catch-Up Contributions: The additional catch-up contribution for individuals aged 55 and older is likely to remain, offering an extra boost for those nearing retirement.
- HDHP Deductible and Out-of-Pocket Max: The minimum deductible and maximum out-of-pocket limits for qualifying HDHPs will also see adjustments, impacting eligibility.
These annual adjustments, while often incremental, collectively contribute to the potential for a significant financial advantage. By understanding the new parameters, you can strategically plan your contributions to hit the maximum allowed, thereby amplifying your tax savings and investment growth potential. Don’t leave money on the table by not being aware of these critical updates.
Unlocking the Triple Tax Advantage: A $1,000 Annual Boost
One of the most compelling reasons to prioritize your HSA is its unparalleled triple tax advantage, a benefit that can easily translate into hundreds, if not thousands, of dollars in annual savings. This unique structure sets HSAs apart from nearly every other savings or investment vehicle available today. For 2026, understanding and leveraging this advantage is key to realizing that potential $1,000 annual financial impact.
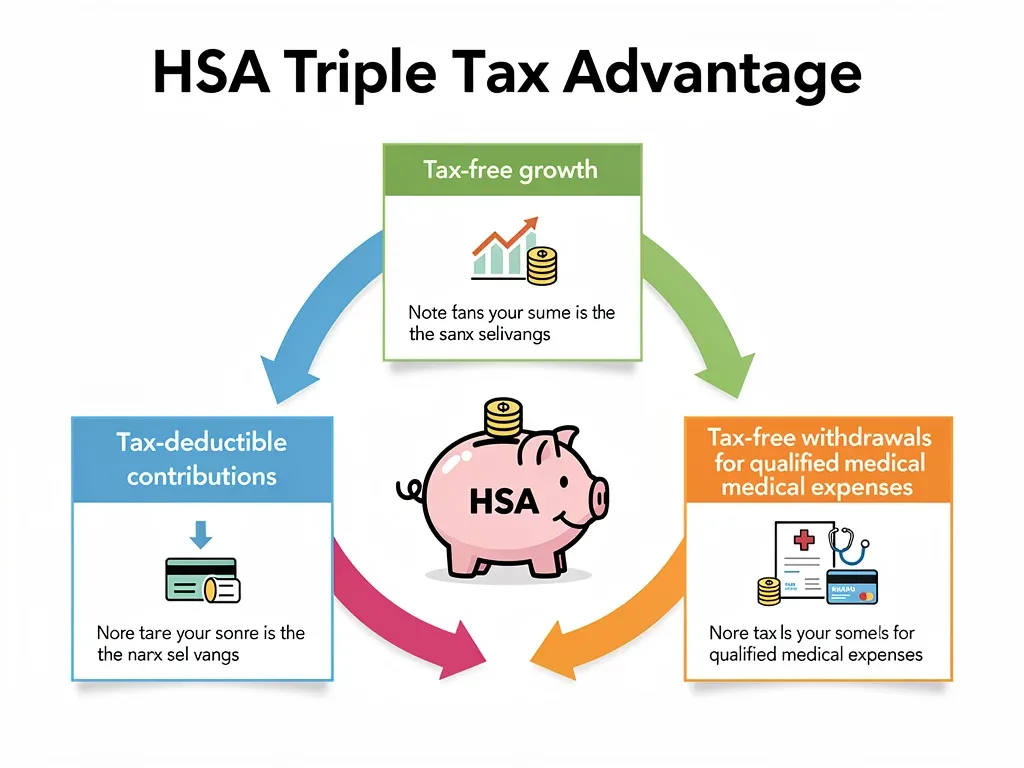
The triple tax benefit comprises three distinct advantages: tax-deductible contributions, tax-free growth of investments, and tax-free withdrawals for qualified medical expenses. Each component works synergistically to create a powerful savings mechanism, not just for healthcare but as a robust long-term investment tool.
Deductible Contributions Explained
When you contribute to an HSA, those contributions are tax-deductible. This means the money you put into your HSA reduces your taxable income for the year, leading to immediate tax savings. For someone in a 25% tax bracket contributing the maximum individual amount, this deduction alone can save hundreds of dollars. It’s essentially free money from the government, incentivizing you to save for your health.
- Direct Tax Reduction: Lowers your adjusted gross income (AGI), potentially reducing your overall tax liability.
- Payroll Deduction Benefits: Contributions made through payroll deductions often bypass FICA taxes (Social Security and Medicare), adding another layer of tax savings.
- Instant Savings: The tax savings are realized in the same year the contributions are made, providing immediate financial relief.
This initial tax break is often overlooked but forms the bedrock of the HSA’s financial power. By reducing your taxable income, you effectively increase your take-home pay or free up funds for other financial goals. It’s a tangible benefit that starts accruing the moment you contribute.

Tax-Free Growth and Withdrawals
Beyond the initial deduction, your HSA funds grow tax-free. Any interest, dividends, or capital gains earned on the investments within your HSA are not subject to annual taxation. This allows your money to compound more rapidly, significantly accelerating your savings growth over time. When you eventually withdraw funds for qualified medical expenses, those withdrawals are also completely tax-free.
This dual tax-free status—growth and withdrawals—is what truly elevates the HSA to a premier financial planning tool. Imagine your investments growing for decades without Uncle Sam taking a cut, and then being able to access that money for healthcare costs without paying taxes on the withdrawals. This combination is a powerful driver of the potential $1,000 annual advantage we’re discussing for 2026 and beyond.
The ability to invest HSA funds is a critical feature that many people don’t fully utilize. Instead of letting money sit in a low-interest savings account, consider investing it in a diversified portfolio. Over time, even modest investment returns can lead to substantial growth, turning your HSA into a significant asset for your retirement years. This long-term growth is where the true financial magic of an HSA unfolds, far surpassing simple savings accounts.
Strategic Contributions: Maximizing Your Annual Limits
To truly maximize your 2026 Health Savings Account (HSA) benefits and realize that $1,000 annual advantage, a strategic approach to contributions is essential. Simply contributing sporadically might not yield the same powerful results as consistently hitting the maximum allowable limits. This section delves into how to plan and execute your contributions effectively for 2026.
Understanding the exact contribution limits for 2026 is the starting point. While the final figures are usually released later in the year, it’s wise to project based on historical increases. The goal is to contribute as much as you can comfortably afford, up to the maximum, to fully leverage the triple tax advantage and accelerate your savings growth.
Planning Your Contributions
Proactive planning is key. Don’t wait until the end of the year to try and make a lump-sum contribution. Instead, consider setting up automatic, recurring contributions, ideally through payroll deductions. This approach makes saving effortless and ensures you consistently contribute throughout the year, making it easier to reach your annual maximum.
- Automate Contributions: Set up direct deposits from your paycheck to your HSA. This “set it and forget it” method ensures consistency.
- Review Limits Annually: Stay updated on the IRS’s announced contribution limits for 2026 to adjust your savings plan accordingly.
- Consider Catch-Up: If you’re 55 or older, remember the additional catch-up contribution. This extra amount can significantly boost your retirement healthcare savings.
Even if you can’t hit the maximum right away, start with an amount that’s feasible and gradually increase it as your financial situation allows. Every dollar contributed to an HSA is a dollar working harder for you, thanks to its unique tax benefits. The sooner you start, the more time your investments have to grow tax-free.
The Power of Consistency
Consistent contributions, even small ones, add up over time. The compound interest effect, combined with the tax-free growth of an HSA, means that early and regular contributions have a disproportionately large impact on your long-term balance. Think of your HSA as a long-term investment vehicle, not just a checking account for medical bills.
By consistently contributing the maximum, or as close to it as possible, you are not only saving for future medical expenses but also building a significant tax-advantaged nest egg. This strategic approach to funding your HSA is a cornerstone of maximizing its financial impact, potentially contributing hundreds of dollars to your annual advantage through tax savings and investment returns.
Eligible Expenses: What Your HSA Covers in 2026
A common misconception about HSAs is that they are only for catastrophic medical events. In reality, the range of eligible expenses for your HSA is quite broad, covering a wide array of healthcare costs you likely incur regularly. Understanding what your HSA covers in 2026 is vital for effective utilization and to avoid unnecessary out-of-pocket spending, further contributing to your $1,000 annual advantage.
The IRS defines qualified medical expenses as those that would generally be deductible as medical expenses on your tax return. This includes much more than just doctor’s visits and hospital stays. From prescriptions to dental care, vision care, and even certain over-the-counter medications, your HSA can be a powerful tool for managing everyday health costs.
Common Qualified Medical Expenses
For 2026, the list of eligible expenses is expected to remain comprehensive, covering essential health services and products. Keeping track of these allows you to pay for them with pre-tax dollars, essentially getting a discount on your healthcare.
- Doctor’s Visits and Co-pays: Standard office visits, specialist appointments, and emergency room co-pays are all covered.
- Prescription Medications: Any prescribed drugs, including insulin, are eligible.
- Dental and Vision Care: This includes routine check-ups, cleanings, braces, eyeglasses, contact lenses, and even laser eye surgery.
- Over-the-Counter (OTC) Medications: Many OTC drugs and health products, including pain relievers, cold medicines, and first-aid supplies, became eligible without a prescription in recent years and are expected to remain so.
- Medical Equipment: Crutches, wheelchairs, and other necessary medical devices.
- Lab Tests and X-rays: Diagnostic services are fully covered.
It’s important to keep meticulous records of all your medical expenses, even if you don’t reimburse yourself immediately. You can choose to let your HSA funds grow and reimburse yourself years later, as long as the expense was incurred after your HSA was established. This strategy allows your money to grow tax-free for longer.
Lesser-Known Eligible Expenses
Beyond the obvious, HSAs also cover some less common but equally important health-related costs. Being aware of these can help you maximize your benefits even further.
For example, acupuncture, chiropractic care, and even certain weight-loss programs prescribed by a doctor can be eligible. Additionally, feminine hygiene products, sunscreen, and even mileage driven to and from medical appointments can often qualify. Always refer to IRS Publication 502 for the most current and complete list of eligible expenses to ensure compliance and full utilization of your HSA funds.
Investing Your HSA: Beyond a Savings Account
While many treat their HSA as a mere savings account for immediate medical needs, its true potential lies in its investment capabilities. To truly maximize your 2026 Health Savings Account (HSA) benefits and achieve that significant $1,000 annual advantage, you must look beyond simply holding cash. Investing your HSA funds can transform it into a powerful, tax-advantaged retirement asset.
Unlike a Flexible Spending Account (FSA), HSA funds roll over year after year and can be invested in various assets, much like a 401(k) or IRA. This long-term growth potential, combined with the triple tax advantage, makes the HSA arguably the most powerful retirement savings vehicle available for healthcare expenses.

Choosing an HSA Provider with Investment Options
Not all HSA providers offer the same investment opportunities. Some may only provide basic savings accounts, while others offer a wide range of investment options, from mutual funds and ETFs to individual stocks. Selecting a provider that aligns with your investment goals is crucial.
- Research Providers: Compare different HSA administrators based on their investment platforms, fees, and available funds.
- Understand Fees: Be aware of administrative fees, investment fees, and expense ratios that can impact your returns.
- Diversify Your Portfolio: Just like any other investment, diversify your HSA investments to mitigate risk and optimize growth.
Many HSA providers offer a threshold amount that must remain in cash before funds can be invested. Once you meet this threshold, you can typically direct additional contributions into investment options. This dual functionality—savings for immediate needs and investments for long-term growth—is a hallmark of a well-managed HSA.
Long-Term Growth Strategy
For those who can afford to pay for current medical expenses out-of-pocket and let their HSA funds grow untouched, the long-term benefits are substantial. Over decades, the tax-free compounding of investment returns can lead to a significant sum, providing a robust financial cushion for healthcare costs in retirement.
Even if you anticipate using your HSA for near-term expenses, dedicating a portion of your contributions to investments can still provide significant growth. The key is to think of your HSA as a dual-purpose account: a spending account for qualified medical expenses and an investment account for future healthcare needs. This strategic balance is fundamental to unlocking the full financial potential of your HSA in 2026 and beyond.
HSA as a Retirement Tool: The Ultimate Savings Vehicle
While primarily designed for healthcare expenses, the HSA’s unique features make it an incredibly powerful, often overlooked, retirement savings vehicle. For those aiming to maximize your 2026 Health Savings Account (HSA) benefits, understanding its role in retirement planning can unlock far more than a $1,000 annual advantage; it can secure your financial future against rising healthcare costs in your golden years.
Once you reach age 65, your HSA essentially functions like a traditional 401(k) or IRA. You can withdraw funds for any purpose without penalty, though withdrawals for non-medical expenses will be taxed as ordinary income. However, if you continue to use the funds for qualified medical expenses, they remain completely tax-free, making it superior to other retirement accounts for healthcare.
Healthcare Costs in Retirement
Healthcare is one of the largest and most unpredictable expenses in retirement. Medicare does not cover everything, and supplemental insurance, deductibles, co-pays, and long-term care can quickly deplete retirement savings. An adequately funded HSA can be a game-changer, providing a dedicated, tax-advantaged fund to cover these costs.
- Supplement Medicare: Use HSA funds to pay for Medicare premiums, deductibles, co-insurance, and co-pays.
- Long-Term Care: Premiums for qualified long-term care insurance can be paid with HSA funds, offering significant tax relief.
- Dental and Vision: Continue to cover dental and vision care, which Medicare typically does not.
By proactively funding your HSA throughout your working years, you’re building a reservoir of tax-free money specifically earmarked for these inevitable retirement healthcare expenses. This foresight can prevent you from dipping into other retirement accounts, like your 401(k) or IRA, which would otherwise be subject to taxes upon withdrawal.
The “Last Resort” Investment Strategy
Many financial advisors recommend treating your HSA as a “last resort” investment. This strategy involves paying for current medical expenses out-of-pocket, if feasible, and allowing your HSA funds to remain invested and grow tax-free for as long as possible. You can then reimburse yourself for those past expenses decades later, as long as you keep accurate records.
This approach maximizes the tax-free growth period, turning your HSA into a super-charged investment account. By the time you reach retirement, the accumulated funds can be substantial, providing immense flexibility for managing healthcare costs without impacting your other retirement savings. It’s a sophisticated strategy that truly unlocks the full potential of an HSA as a powerful retirement planning tool for 2026 and beyond.
Common Pitfalls to Avoid with Your HSA in 2026
While HSAs offer incredible advantages, there are common pitfalls that can diminish their effectiveness if not carefully navigated. To truly maximize your 2026 Health Savings Account (HSA) benefits and ensure you realize that $1,000 annual advantage, it’s crucial to be aware of these potential traps and how to avoid them. Avoiding these mistakes will protect your savings and ensure compliance.
One of the most frequent errors is treating an HSA like a checking account, withdrawing funds for every minor medical expense without considering the long-term growth potential. Another is failing to understand the eligibility rules, which can lead to penalties. Being informed is your best defense against these common missteps.
Misunderstanding Eligibility Requirements
The fundamental requirement for an HSA is enrollment in a High-Deductible Health Plan (HDHP). Many individuals mistakenly contribute to an HSA without being properly enrolled in a qualifying HDHP, leading to tax penalties. Ensure your health plan meets the IRS criteria for deductibles and out-of-pocket maximums for 2026.
- HDHP Enrollment: Confirm your health insurance plan is a qualified HDHP for the entire period you contribute.
- No Other Coverage: Generally, you cannot have other health coverage (like a spouse’s non-HDHP plan) that covers the same expenses.
- Not on Medicare: Once you enroll in Medicare, you can no longer contribute to an HSA, though you can still use existing funds.
It’s also important to note that you cannot be claimed as a dependent on someone else’s tax return. These eligibility rules are strict, and failing to meet them can result in your contributions being treated as taxable income, plus an additional 20% penalty. Always verify your eligibility before contributing.
Improper Use of Funds and Record Keeping
Another significant pitfall is using HSA funds for non-qualified expenses before age 65. While you can withdraw funds for any reason after 65, doing so earlier for non-medical costs incurs both income tax and a 20% penalty. This can quickly erode any financial advantage you’ve built.
Furthermore, poor record-keeping is a common issue. If you plan to pay for expenses out-of-pocket and reimburse yourself years later, you must retain all receipts and documentation proving the medical expense was qualified and incurred after your HSA was established. Without proper records, you could face challenges during an audit.
Always keep detailed records of your contributions, withdrawals, and all qualified medical expenses. This meticulous approach will protect you from potential penalties and ensure you can fully enjoy the tax-free nature of your HSA funds, both now and in retirement. Avoiding these common mistakes is as important as strategic contributing for maximizing your 2026 HSA benefits.
| Key Aspect | Brief Description |
|---|---|
| Triple Tax Advantage | Contributions are tax-deductible, growth is tax-free, and qualified withdrawals are tax-free. |
| Strategic Contributions | Aim to maximize annual limits for individuals and families, including catch-up contributions for those 55+. |
| Investment Potential | Invest HSA funds for long-term, tax-free growth, transforming it into a powerful retirement asset. |
| Retirement Vehicle | After age 65, HSA funds can be withdrawn tax-free for medical or taxed as income for non-medical expenses. |
Frequently Asked Questions About 2026 HSA Benefits
What are the projected 2026 HSA contribution limits?▼While official 2026 HSA contribution limits will be released by the IRS later, they are typically adjusted annually for inflation. Based on historical trends, expect a slight increase from 2025 limits for both individual and family plans, along with the catch-up contribution for those 55 and over.
How does an HSA provide a “triple tax advantage”?▼The triple tax advantage refers to three benefits: contributions are tax-deductible, funds grow tax-free through investments, and withdrawals for qualified medical expenses are tax-free. This combination makes it an exceptionally powerful savings and investment tool.
Can I invest the money in my HSA?▼Yes, one of the most significant benefits of an HSA is the ability to invest your funds, much like a 401(k) or IRA. Many HSA providers offer various investment options, allowing your money to grow tax-free over time, significantly boosting your long-term savings.
What types of expenses are eligible for HSA withdrawals?▼HSA funds can be used for a wide range of qualified medical expenses, including doctor visits, prescriptions, dental care, vision care, and even many over-the-counter medications. It’s crucial to keep records to substantiate all withdrawals for medical purposes.
How does an HSA function as a retirement tool?▼After age 65, an HSA acts like a traditional retirement account. You can withdraw funds for any purpose without penalty, though non-medical withdrawals are taxed as ordinary income. For qualified medical expenses, withdrawals remain entirely tax-free, making it ideal for retirement healthcare costs.
Conclusion
In conclusion, the opportunity to maximize your 2026 Health Savings Account (HSA) benefits is a clear path to achieving a significant financial advantage, potentially exceeding $1,000 annually. By understanding the updated contribution limits, leveraging the powerful triple tax advantage, strategically investing your funds, and utilizing it as a robust retirement vehicle, you can transform your HSA from a simple healthcare account into a cornerstone of your overall financial well-being. Proactive planning, consistent contributions, and diligent record-keeping are essential steps to unlock the full potential of this invaluable tool, securing both your immediate health needs and your long-term financial future.