Secured Credit Cards 2026: Boost Your Score 30 Points in 9 Months
Advertisements
Secured credit cards in 2026 provide an effective tool for individuals to significantly improve their credit score, potentially achieving a 30-point increase within a nine-month timeframe by demonstrating responsible financial behavior.
Are you looking to enhance your financial standing and boost your credit score? Navigating the complexities of credit can be challenging, but understanding the power of secured credit cards in 2026 offers a clear path forward. This comprehensive guide will illuminate how these financial tools can be your most effective ally, helping you achieve a remarkable 30-point increase in your credit score within a focused nine-month period.
Understanding Secured Credit Cards in 2026
Secured credit cards are designed specifically for individuals who are new to credit or are looking to rebuild their credit history. Unlike traditional unsecured credit cards, secured cards require a cash deposit, which typically serves as your credit limit. This deposit acts as collateral, mitigating risk for the issuer and making these cards accessible to a wider range of applicants. In 2026, the landscape of secured credit cards continues to evolve, offering more competitive terms and features tailored to help consumers build credit responsibly.
The primary benefit of a secured credit card is its ability to report your payment activity to the major credit bureaus. Every on-time payment you make contributes positively to your credit report, which is crucial for improving your credit score. This mechanism allows you to demonstrate financial responsibility over time, gradually enhancing your creditworthiness. Many issuers also offer pathways to transition from a secured card to an unsecured card after a period of responsible use, further cementing your credit growth.
How Secured Cards Differ from Unsecured Cards
The fundamental difference lies in the collateral. An unsecured card is issued based solely on your credit history and income, without requiring a deposit. This makes them harder to obtain for those with poor or no credit. Secured cards, conversely, are much more accessible because the deposit minimizes the lender’s risk. This distinction is vital for anyone aiming to establish or repair their credit.
- Collateral Requirement: Secured cards demand a security deposit, unsecured cards do not.
- Eligibility: Secured cards are easier to qualify for, ideal for credit building.
- Credit Limit: Often equals your deposit on a secured card; unsecured limits vary based on creditworthiness.
- Credit Building: Both can build credit, but secured cards are a starting point for many.
Choosing a secured credit card in 2026 means opting for a controlled environment to practice good financial habits. The deposit serves as a safety net, encouraging careful spending while simultaneously reporting positive activity to credit bureaus. This makes them an indispensable tool for anyone serious about elevating their credit score efficiently.
In essence, secured credit cards are a stepping stone. They provide the mechanism to prove your reliability as a borrower, which is then reflected in your credit score. Understanding their core function and how they operate in today’s financial climate is the first critical step toward achieving your credit improvement goals.
Setting the Stage: Your 9-Month Credit Score Boost Plan
Achieving a 30-point credit score increase in nine months requires a strategic and disciplined approach. It’s not merely about getting a secured credit card, but about using it effectively as part of a broader financial plan. This nine-month timeline is realistic and achievable for most individuals when consistent, positive actions are taken. The journey begins with understanding your current credit standing and setting clear, measurable goals.
Before applying for any card, obtain your current credit report and score. This will provide a baseline for your progress and help identify any inaccuracies that might be dragging your score down. Once you have a clear picture, you can select a secured credit card that aligns with your financial capacity and credit-building objectives. The key is to choose a card from an issuer that reports to all three major credit bureaus: Experian, Equifax, and TransUnion.
Key Steps for a 9-Month Improvement
Success hinges on consistent execution of a few core principles. These steps are designed to maximize the impact of your secured credit card on your credit score within the specified timeframe.
- Open a Secured Card: Choose a card with low fees and one that reports to all three major credit bureaus.
- Make Small, Regular Purchases: Use the card for minor expenses you can easily pay off, like groceries or gas.
- Pay on Time, Every Time: Payment history is the most significant factor in your credit score.
- Keep Utilization Low: Aim for a credit utilization ratio below 30%, ideally below 10%.
- Monitor Your Credit: Regularly check your credit report for errors and track your progress.
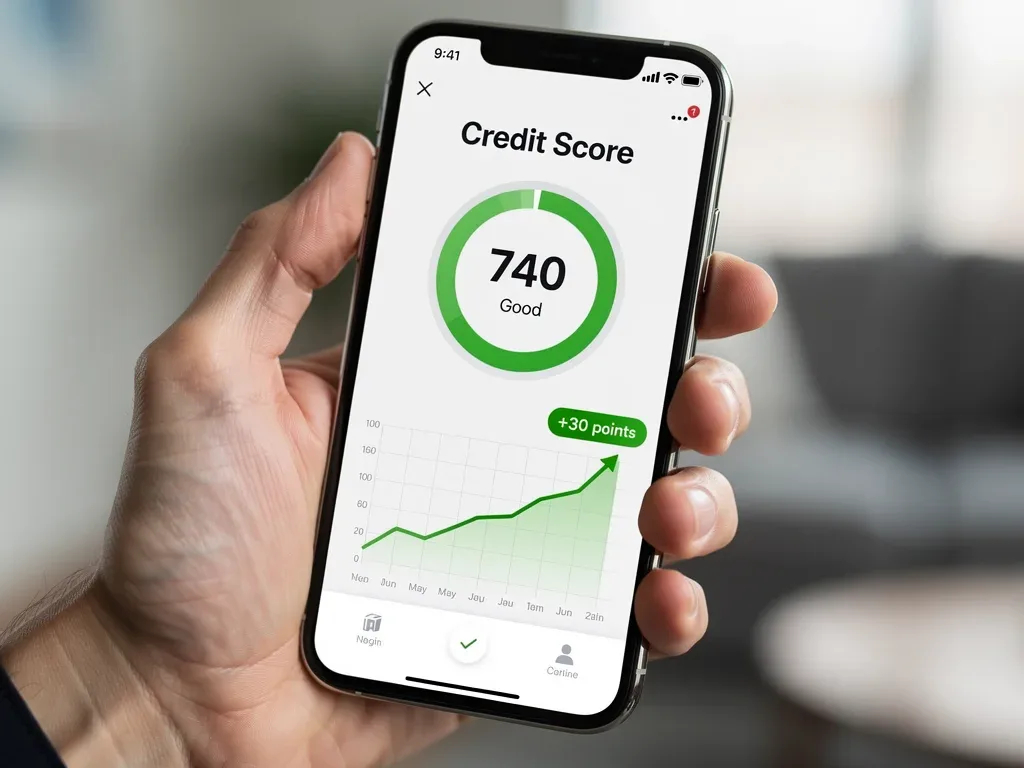
The nine-month plan is a commitment. It demands diligence and a conscious effort to manage your credit responsibly. By adhering to these guidelines, you create a pattern of positive financial behavior that credit bureaus recognize and reward. Remember, consistency is more important than the amount you spend; it’s about proving you can manage credit reliably.
By the end of this nine-month period, not only will you likely see that 30-point jump, but you’ll also have cultivated invaluable financial habits that will serve you well for years to come. This disciplined approach transforms a simple financial product into a powerful credit-building tool.
Choosing the Right Secured Credit Card in 2026
The market for secured credit cards in 2026 offers a variety of options, each with its own set of terms and benefits. Selecting the right card is a crucial decision that can significantly impact your credit-building journey. It’s not just about getting approved; it’s about finding a card that supports your financial goals without imposing unnecessary burdens.
Begin by researching issuers known for their secured card programs. Look for cards with reasonable annual fees, or ideally, no annual fee at all. The security deposit amount is another critical factor; choose one that fits comfortably within your budget, as this will typically determine your initial credit limit. Importantly, confirm that the issuer reports to all three major credit bureaus (Experian, Equifax, and TransUnion) to ensure your responsible usage is fully recognized across the board.
Factors to Consider Before Applying
A careful evaluation of various features will help you pinpoint the best secured card for your situation. Don’t rush this step, as the right choice can streamline your path to a better credit score.
- Annual Fees: Prefer cards with no or low annual fees to maximize savings.
- Security Deposit: Ensure the deposit is affordable and matches your desired credit limit.
- Reporting to Bureaus: Verify that the issuer reports to all three major credit bureaus.
- Path to Unsecured Card: Some cards offer a graduation path to an unsecured card, a significant long-term benefit.
- Interest Rates: While you should aim to pay in full, a lower APR is always better for emergencies.
Read the fine print carefully. Understand the grace period for payments, any potential late fees, and how interest is calculated. Some secured cards even offer rewards, which can be a nice bonus, though credit building should remain your primary focus. The goal is to find a card that acts as a true stepping stone, not a financial trap.
Ultimately, the best secured credit card for you in 2026 will be one that is transparent about its terms, affordable to maintain, and effective in reporting your positive payment history. Taking the time to research thoroughly will pay dividends in your credit-building efforts.
Maximizing Your Credit Score Increase: Best Practices
Once you have your secured credit card, the real work of credit building begins. Maximizing your credit score increase over nine months involves more than just making payments; it requires strategic usage and diligent monitoring. Every action you take with your card sends a signal to credit bureaus, and consistent positive signals are what drive significant score improvements.
The cornerstone of credit building is on-time payments. This cannot be overstated. Even a single late payment can severely undermine months of positive effort. Set up automatic payments or calendar reminders to ensure you never miss a due date. Beyond timeliness, managing your credit utilization is paramount. This refers to the amount of credit you’re using compared to your total available credit.
Strategies for Rapid Credit Improvement
Implementing these practices from day one will accelerate your progress towards a 30-point score increase within the nine-month timeframe.
- Pay in Full and On Time: Always pay your balance in full before the due date to avoid interest and build a strong payment history.
- Keep Credit Utilization Low: Aim to keep your balance below 10% of your credit limit. For example, if your limit is $500, try to keep your balance under $50.
- Regular, Small Transactions: Use the card for small, manageable purchases to show consistent activity without accruing high balances.
- Avoid Opening New Accounts: Limit new credit applications during this nine-month period to prevent multiple hard inquiries on your report.
- Monitor Your Credit Report: Check your reports regularly for accuracy and to track your score’s progress.
These practices work synergistically. On-time payments demonstrate reliability, low utilization shows responsible credit management, and consistent activity proves you’re an active borrower. Together, they paint a picture of a low-risk individual, which is exactly what lenders look for. Remember, your secured credit card is a tool to prove your creditworthiness, so use it wisely and intentionally.
By committing to these best practices, you’re not just aiming for a temporary boost; you’re establishing a foundation for long-term financial health. The 30-point increase is a tangible reward for your discipline and strategic approach to using secured credit cards.
Beyond Payments: Additional Factors for Credit Score Growth
While on-time payments and low credit utilization are the pillars of credit score improvement, other factors also play a significant role. To truly maximize your credit score growth over nine months, it’s essential to address these additional elements. A holistic approach ensures that all aspects of your financial behavior contribute positively to your credit profile, accelerating your journey towards a stronger score.
One often overlooked factor is the length of your credit history. While you’re building new history with your secured card, avoiding the closure of old, positive accounts (if you have any) can be beneficial. A longer average age of accounts generally reflects positively on your credit report. Furthermore, the mix of credit you have, including revolving credit (like credit cards) and installment loans (like student loans or car loans), can also influence your score.
Broader Financial Habits that Impact Credit
Integrating these habits into your financial routine will complement your secured credit card usage and bolster your overall credit health.
- Review Credit Reports Annually: Obtain free copies of your credit report from AnnualCreditReport.com to check for errors and fraudulent activity. Disputing inaccuracies can quickly improve your score.
- Manage Other Debts: Keep balances on other credit accounts (if any) as low as possible. High debt can signal financial strain.
- Avoid New Credit Applications: Each hard inquiry can temporarily ding your score. Limit applications for new credit during your credit-building phase.
- Build Savings: A healthy savings account demonstrates financial stability, indirectly supporting your overall financial health and ability to manage debt.
The goal is to present a consistent image of financial responsibility across all your accounts. This includes paying all bills on time, not just your secured credit card. Utility bills, rent payments, and other financial obligations, though not always directly reported to credit bureaus, can sometimes be factored in through alternative reporting services or in the event of delinquency.
By focusing on these broader financial habits in conjunction with the strategic use of your secured credit card, you create a robust framework for credit score improvement. This comprehensive strategy ensures that you’re not just addressing one aspect of your credit, but building a strong, resilient financial foundation for the future.
Monitoring Progress and Transitioning to Unsecured Credit
Tracking your credit score progress is not just motivating; it’s a critical component of your nine-month plan to boost your score by 30 points. Regular monitoring allows you to see the tangible results of your efforts, identify any potential issues early, and adjust your strategy as needed. Many credit card issuers and financial services offer free access to your credit score, making this step easier than ever in 2026.
As you approach the nine-month mark, and especially if you’ve diligently followed all the best practices, you should start to see significant improvements in your score. This is also the time to consider your next steps, particularly the transition from a secured credit card to an unsecured one. Many secured card programs are designed with this graduation in mind, rewarding responsible users with an upgrade.
Signs You’re Ready for Unsecured Credit
Knowing when to make the leap is important. Look for these indicators that signal your readiness for an unsecured card, which offers more flexibility and often better terms.
- Consistent On-Time Payments: A perfect payment history over the past 9-12 months.
- Low Credit Utilization: Maintaining utilization below 10% consistently.
- Significant Score Improvement: A noticeable increase in your credit score, ideally reaching your 30-point goal or higher.
- Increased Credit Limit on Secured Card: Some issuers automatically increase your limit without requiring an additional deposit, indicating trust.
- Offers for Unsecured Cards: Receiving pre-approved offers for unsecured cards is a strong sign of improved creditworthiness.
If your secured card issuer offers a graduation path, inquire about the process. This can often be the smoothest transition, as they already have a history with you. If not, research entry-level unsecured cards that cater to individuals with fair credit. Be mindful of applying for too many cards at once, as multiple hard inquiries can temporarily depress your score.
The transition to unsecured credit marks a significant milestone in your financial journey. It signifies that you’ve successfully demonstrated responsible credit management and are ready for greater financial freedom. This careful monitoring and strategic planning ensure that your credit-building efforts lead to lasting positive outcomes.
| Key Strategy | Brief Description |
|---|---|
| On-Time Payments | Crucial for building a positive payment history, the largest factor in credit scores. |
| Low Credit Utilization | Keeping balances below 10-30% of your limit signals responsible credit use. |
| Regular Monitoring | Consistently checking credit reports for errors and tracking score changes. |
| Strategic Card Use | Using the card for small, manageable purchases and paying them off quickly. |
Frequently Asked Questions About Secured Credit Cards
What is the typical timeframe to see a credit score increase with a secured credit card?▼While results vary, many users begin to see noticeable improvements in their credit score within 6 to 12 months of consistent and responsible use. Our 9-month plan is an achievable goal for a 30-point increase with diligent effort.
Does the security deposit earn interest?▼Generally, no. Most secured credit card deposits do not earn interest. The primary purpose of the deposit is to secure the credit line for the issuer, not to act as an investment vehicle for the cardholder.
Can I get my security deposit back?▼Yes, typically you can get your security deposit back when you close the account in good standing, or if your card graduates to an unsecured card. This usually requires a history of on-time payments and responsible credit use.
Are there any secured credit cards without an annual fee?▼Yes, several issuers offer secured credit cards with no annual fee. These are often preferred as they reduce the overall cost of credit building. Researching different options is key to finding the best fit for your needs.
How does credit utilization impact my score?▼Credit utilization is a significant factor, accounting for about 30% of your FICO score. Keeping your used credit below 30% of your total available credit, and ideally below 10%, is crucial for a positive impact on your score.
Conclusion
Embarking on the journey to improve your credit score can feel daunting, but with the right tools and a clear strategy, significant progress is entirely achievable. Secured credit cards in 2026 stand out as a highly effective mechanism for individuals to build or rebuild their credit history. By diligently following the nine-month plan outlined, focusing on consistent on-time payments, maintaining low credit utilization, and monitoring your financial health, boosting your score by 30 points is a realistic and attainable goal. This process not only enhances your creditworthiness but also instills valuable financial discipline that will serve you well throughout your life, opening doors to better financial opportunities.