2026 Credit Freeze Guide: Max Security, 0% Fraud Risk
Advertisements
Implementing a credit freeze in 2026 is a crucial step for safeguarding your financial identity against evolving threats, offering maximum security and aiming for a zero percent fraud risk by restricting access to your credit reports.
In an increasingly digital world, protecting your financial identity has never been more critical. This comprehensive guide, The 2026 Guide to Credit Freezes: When and How to Implement for Maximum Security and a 0% Fraud Risk, offers crucial insights into leveraging credit freezes to shield yourself from identity theft and financial fraud.
Understanding the Evolving Threat Landscape in 2026
The year 2026 brings with it an unprecedented level of digital interconnectedness, but also sophisticated cyber threats. Identity thieves and fraudsters are constantly innovating, employing advanced techniques to compromise personal financial information. Understanding these evolving risks is the first step towards robust protection.
Traditional methods of securing personal data are often no longer sufficient. From AI-powered phishing scams to complex data breaches, the avenues for illicit access to your credit information are multiplying. This makes proactive measures like a credit freeze not just advisable, but essential for maintaining financial integrity.
The Rise of AI-Powered Fraud
Artificial intelligence, while a boon in many sectors, has also been weaponized by malicious actors. AI can generate highly convincing phishing emails, mimic voices for social engineering attacks, and even automate the process of sifting through stolen data for valuable financial nuggets. The sheer scale and convincing nature of these attacks demand a higher level of defense.
- Deepfake Technology: Used to create fraudulent identities or authorize illicit transactions.
- Automated Data Exploitation: AI algorithms can quickly identify exploitable data points from large breaches.
- Personalized Phishing: AI crafts highly targeted and believable scam messages.
- Synthetic Identity Fraud: Combining real and fake information to create new, fraudulent identities.
The complexity of these threats means that simply monitoring your credit report might not be enough to prevent damage. A credit freeze acts as a fundamental barrier, preventing unauthorized access to your credit file even if your personal information is compromised.
In conclusion, the 2026 digital landscape necessitates a vigilant and proactive approach to financial security. Recognizing the advanced methods employed by fraudsters is key to appreciating the indispensable role of a credit freeze in your overall protection strategy.
What Exactly is a Credit Freeze and How Does it Work?
A credit freeze, also known as a security freeze, is a powerful tool that restricts access to your credit report. When your credit report is frozen, potential creditors cannot access it, which means new credit accounts cannot be opened in your name without your explicit permission. This effectively stops identity thieves from opening new lines of credit using your stolen information.
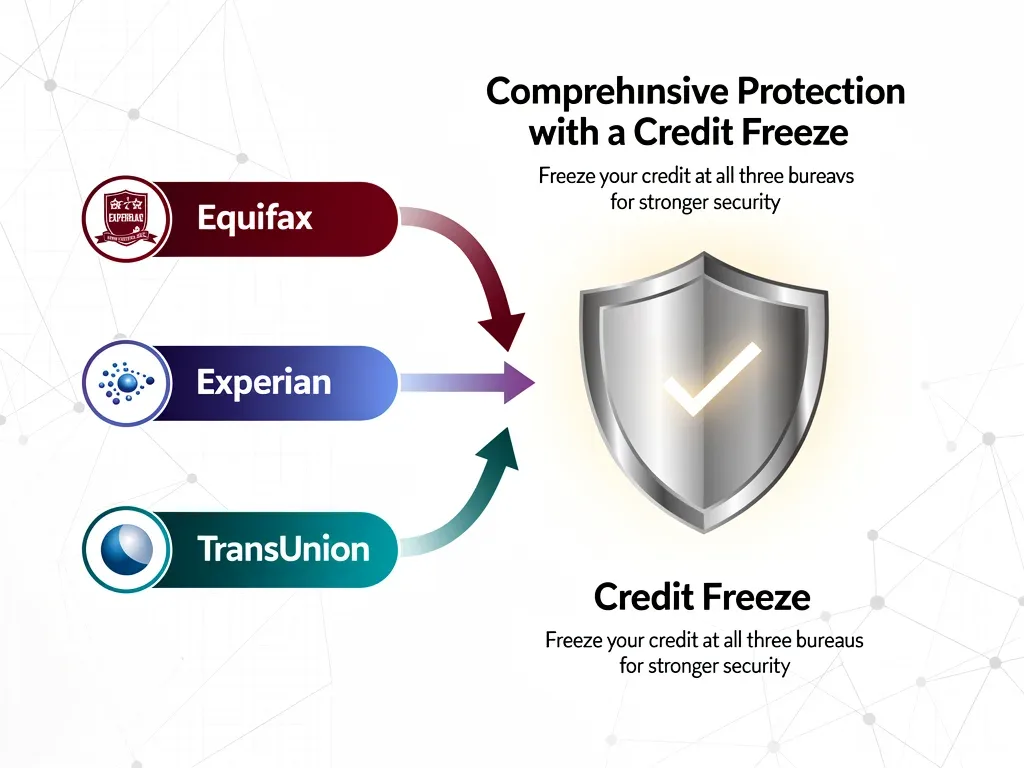
The process involves contacting each of the three major credit bureaus individually: Equifax, Experian, and TransUnion. Each bureau will require you to set up a freeze separately, and each will provide you with a unique PIN or password that you will need to unfreeze your credit in the future. It’s crucial to keep these PINs secure.
When you apply for new credit, a loan, or even some jobs or insurance policies, you will need to temporarily lift or ‘thaw’ your credit freeze to allow the inquiring party to access your report. You can typically do this online, by phone, or by mail, specifying the duration or the specific creditor that can access your report.
The Mechanics of Freezing Your Credit
The mechanism behind a credit freeze is straightforward but highly effective. By placing a freeze, you are essentially telling the credit bureaus to block any inquiries for your credit report. This makes it impossible for new accounts to be opened in your name, even if a fraudster has your Social Security number and other personal details.
- Bureau-Specific Action: Each of the three main bureaus must be contacted independently.
- Unique PINs: A distinct personal identification number is issued by each bureau for managing your freeze.
- Temporary Unfreeze: You control when and for how long your credit report is accessible.
- No Impact on Score: A credit freeze does not affect your credit score.
It’s important to remember that a credit freeze does not prevent you from accessing your own credit report, nor does it prevent pre-approved credit offers from reaching you. It solely restricts third-party access for new credit applications.
In essence, a credit freeze serves as an impenetrable shield, making it significantly harder for fraudsters to exploit your identity for financial gain. Its simplicity and effectiveness make it a cornerstone of modern financial security.
When is the Right Time to Implement a Credit Freeze?
Deciding when to implement a credit freeze is a strategic decision that depends on your personal circumstances and risk tolerance. While it’s always a good idea to consider one, certain situations make it an imperative measure for maximum security and to achieve a 0% fraud risk.
The most opportune time to freeze your credit is before any suspicious activity occurs. Proactive freezing ensures that even if your data is compromised in a breach, fraudsters cannot immediately open new accounts. Waiting until you suspect identity theft means you might already be playing catch-up.
Key Scenarios for Immediate Action
Several events should trigger an immediate consideration for a credit freeze. These are situations where your personal information is at heightened risk of exposure or has already been compromised. Acting swiftly in these instances can mitigate significant potential damage.
- Following a Data Breach: If you receive notification that your personal data has been exposed in a breach.
- After Losing Personal Documents: If your wallet, purse, or other documents containing sensitive information are lost or stolen.
- Suspicious Activity Alerts: If you notice unusual inquiries on your credit report or receive notifications about accounts you didn’t open.
- Proactive Protection: Even without a specific incident, freezing your credit provides continuous protection against future threats.
For individuals who rarely apply for new credit, maintaining a permanent freeze and only thawing it when absolutely necessary is an ideal strategy. This ‘always on’ protection significantly reduces your vulnerability to identity theft.
Ultimately, the best time to implement a credit freeze is now. Don’t wait for a crisis to occur; take control of your financial security proactively to safeguard against the ever-present threat of identity fraud.
Step-by-Step Guide: How to Implement a Credit Freeze
Implementing a credit freeze is a straightforward process, but it requires contacting each of the three major credit bureaus individually. This step-by-step guide will walk you through the necessary actions to secure your credit reports effectively in 2026.
Before you begin, gather all necessary personal identification information, including your full name, current and previous addresses, Social Security number, and date of birth. Having this information readily available will expedite the process with each bureau.
Contacting Each Credit Bureau
You must reach out to Equifax, Experian, and TransUnion separately. Each bureau offers online, phone, and mail options for placing a security freeze. While online is often the fastest, using certified mail provides a paper trail for your records.
- Equifax: Visit their official website, navigate to the security freeze section, and follow the prompts. You can also call their dedicated freeze line.
- Experian: Access their website’s security freeze page or contact their customer service by phone.
- TransUnion: Use their online portal for credit freezes or call their designated phone number.
- Record Keeping: Always save any confirmation numbers, PINs, or passwords provided by each bureau.
Upon successful implementation, each bureau will send you a confirmation and a unique PIN or password. This identifier is crucial for managing your freeze, so store it securely where you can easily retrieve it when needed, but away from other personal documents.
Remember, a credit freeze is free to place and lift, thanks to federal law. There should be no cost associated with this vital security measure. Confirming the freeze with all three bureaus ensures comprehensive protection against unauthorized credit access.
Managing Your Credit Freeze: Thawing and Lifting
While a credit freeze offers unparalleled protection, it’s not a permanent, set-it-and-forget-it measure if you ever need to apply for new credit. Understanding how to effectively manage your freeze, including temporary thaws and permanent lifts, is crucial for maintaining financial flexibility while staying secure.
When you need to apply for a new credit card, a loan, a mortgage, or even certain types of employment or insurance, the lender or employer will need to access your credit report. This requires you to temporarily lift or ‘thaw’ your credit freeze with the relevant credit bureau(s).
Options for Temporarily Lifting a Freeze
Each credit bureau provides multiple methods for managing your credit freeze. The most convenient options are typically online or by phone, allowing for quick adjustments when needed. You will need the PIN or password issued when you initially placed the freeze.
- Temporary Unfreeze: You can specify a date range during which your credit report will be accessible. This is ideal for short-term applications.
- Specific Creditor Access: Some bureaus allow you to grant access to a particular creditor for a one-time inquiry, without fully unfreezing your report.
- Permanent Lift: If you no longer wish to maintain the freeze, you can permanently remove it, though this is generally not recommended for ongoing protection.
- Instant vs. Delayed: Online and phone requests for thawing are often instant, while mail requests can take several business days to process.
It’s important to coordinate your unfreeze request with the timing of your credit application. If you unfreeze your credit too early, it might be accessible to unauthorized parties for longer than necessary. If you unfreeze it too late, it could delay your application.
Effectively managing your credit freeze means balancing robust security with the practicalities of needing to access new financial products. With careful planning, you can navigate these processes seamlessly, maintaining both protection and financial agility.
Distinguishing Credit Freezes from Fraud Alerts and Locks
In the realm of credit protection, various tools are available, and it’s essential to understand the differences between them to choose the most effective strategy. While a credit freeze is arguably the strongest defense, fraud alerts and credit locks serve distinct purposes and offer different levels of security.
A common misconception is that all these terms are interchangeable. However, each offers a unique mechanism for protecting your credit, and knowing their individual strengths and limitations will help you construct a comprehensive security plan for 2026 and beyond.
Credit Freezes vs. Fraud Alerts vs. Credit Locks
Let’s break down the key characteristics of each protection mechanism to clarify their roles in your financial defense strategy. Understanding these distinctions is paramount for achieving maximum security.
- Credit Freeze: This is the most restrictive option. It completely blocks access to your credit report unless you explicitly unfreeze it. It prevents new credit accounts from being opened in your name.
- Fraud Alert: A fraud alert places a note on your credit report, alerting creditors that they should take extra steps to verify your identity before extending credit. It typically lasts for one year and is renewable. It’s less restrictive than a freeze, as creditors can still access your report.
- Credit Lock: Offered by credit bureaus, a credit lock is often a paid service that allows you to lock and unlock your credit file instantly via a mobile app or website. While similar to a freeze in function, its legal protections and implementation can differ slightly by bureau and service agreement.
While a fraud alert is a good first step if you suspect identity theft, it relies on creditors to follow through with verification. A credit lock offers convenience but might come with terms and conditions that differ from the legally mandated protections of a credit freeze. The credit freeze, by federal law, provides the strongest and most comprehensive protection.
For individuals prioritizing a 0% fraud risk, a credit freeze remains the gold standard. It offers robust, legally backed protection that actively prevents unauthorized access to your credit, rather than merely flagging potential issues.
The Long-Term Benefits of a Credit Freeze in 2026
Adopting a credit freeze in 2026 offers significant long-term benefits that extend beyond immediate fraud prevention. It establishes a foundation of financial security, providing peace of mind and protecting your credit health for years to come. In an era of persistent data breaches and evolving cybercrime, this proactive measure becomes an invaluable asset.
The continuous protection offered by a credit freeze means you are less likely to become a victim of new account fraud, which can be incredibly time-consuming and stressful to resolve. This allows you to focus on your financial goals without the constant worry of identity theft.
Sustained Peace of Mind and Financial Stability
The primary long-term benefit is the sustained peace of mind that comes from knowing your credit reports are secure. This translates into greater financial stability and less risk of unexpected financial burdens due to fraudulent activities.
- Reduced Stress: Eliminates the constant worry about identity theft impacting your credit.
- Preserved Credit Score: Prevents fraudulent accounts from negatively affecting your credit score.
- Time Savings: Avoids the arduous process of recovering from identity theft, which can take months or even years.
- Enhanced Control: Gives you direct control over who accesses your credit information.
Furthermore, a credit freeze is a free service, making it an incredibly cost-effective solution for long-term security. Unlike paid credit monitoring services, a freeze actively prevents unauthorized access, rather than just notifying you after an event has occurred.
In conclusion, implementing and maintaining a credit freeze is a strategic investment in your future financial well-being. It’s a powerful, free tool that provides robust protection against identity theft, ensuring that your credit remains secure and your financial future bright in the ever-changing landscape of 2026.
| Key Aspect | Description |
|---|---|
| What is it? | Restricts access to your credit report, preventing new credit accounts from being opened. |
| When to use? | Proactively, after a data breach, or if personal documents are lost/stolen. |
| How to implement? | Contact Equifax, Experian, and TransUnion individually online, by phone, or mail. |
| Key benefit | Maximum security against new account identity fraud with 0% risk if properly managed. |
Frequently Asked Questions About Credit Freezes
Does a credit freeze affect my credit score?▼No, placing or lifting a credit freeze has absolutely no impact on your credit score. It only restricts access to your credit report, preventing new credit inquiries from being made without your permission. Your existing credit accounts and payment history remain unaffected.
How long does a credit freeze last?▼A credit freeze, once placed, remains in effect indefinitely until you choose to lift it. There is no expiration date, providing continuous protection. You must actively unfreeze your credit when you need legitimate access to your report for new applications.
Do I need to freeze my credit with all three bureaus?▼Yes, for maximum security, it is highly recommended to freeze your credit with all three major credit bureaus: Equifax, Experian, and TransUnion. Lenders may use any of these bureaus, and freezing with just one leaves you vulnerable to fraud through the others.
Can I still get my free annual credit report with a freeze?▼Absolutely. A credit freeze does not prevent you from accessing your own credit report. You can still obtain your free annual credit reports from AnnualCreditReport.com, as mandated by federal law, even with a freeze in place at all three bureaus.
What if I forget my PIN or password for unfreezing?▼If you forget your PIN or password, each credit bureau has a recovery process. This usually involves verifying your identity through a series of questions. While it might take a little longer, you will still be able to manage your freeze, so don’t panic.
Conclusion
In the dynamic digital landscape of 2026, protecting your financial identity is more critical than ever. This guide to credit freezes underscores their indispensable role in achieving maximum security and aiming for a 0% fraud risk. By understanding when and how to implement this powerful tool, you equip yourself with the strongest defense against identity theft and unauthorized credit access. Proactive management of your credit freeze, alongside distinguishing it from other protective measures, ensures sustained peace of mind and robust financial health in an increasingly interconnected world.