Credit Utilization in 2026: Boost Your Score by 25 Points Below 10%
Advertisements
Maintaining a credit utilization ratio below 10% is projected to be a critical factor in 2026 for boosting credit scores, potentially increasing them by 25 points, by demonstrating responsible credit management and financial stability.
In the dynamic landscape of personal finance, understanding and optimizing your credit score remains paramount. As we look towards 2026, one factor stands out for its profound impact: credit utilization ratios in 2026: how maintaining below 10% can boost your score by 25 points. This often-underestimated metric holds the key to unlocking significant improvements in your financial standing, influencing everything from loan approvals to interest rates.
Understanding credit utilization ratios
Credit utilization, often referred to as the credit utilization ratio, is a fundamental component of your credit score. It represents the amount of credit you are currently using compared to the total amount of credit available to you. Expressed as a percentage, this ratio offers a snapshot of your reliance on borrowed money and your ability to manage it responsibly.
Lenders and credit bureaus view a low utilization ratio as a strong indicator of financial prudence. It suggests that you are not over-relying on credit and have ample capacity to take on new debt, should the need arise. Conversely, a high utilization ratio can signal financial distress or over-indebtedness, potentially leading to a decrease in your credit score.
The mechanics of calculation
Calculating your credit utilization ratio is straightforward. You simply divide your total outstanding credit card balances by your total available credit across all your credit accounts. For instance, if you have a combined credit limit of $10,000 and your total balances amount to $1,000, your utilization ratio is 10% ($1,000 / $10,000).
- Total Balances: Sum of all outstanding amounts on your credit cards.
- Total Available Credit: Sum of all credit limits across your credit cards.
- Ratio Impact: Lower ratios are generally more favorable for your credit score.
It’s important to monitor this ratio not just on an aggregate level, but also for individual credit accounts. While a low overall ratio is good, a high utilization on a single card could still negatively impact your score.
In conclusion, grasping the concept of credit utilization is the first step toward effective credit management. Its direct correlation with your credit score makes it a vital metric to track and optimize, especially as we approach 2026 with evolving credit assessment models.
Why 10% is the magic number for 2026
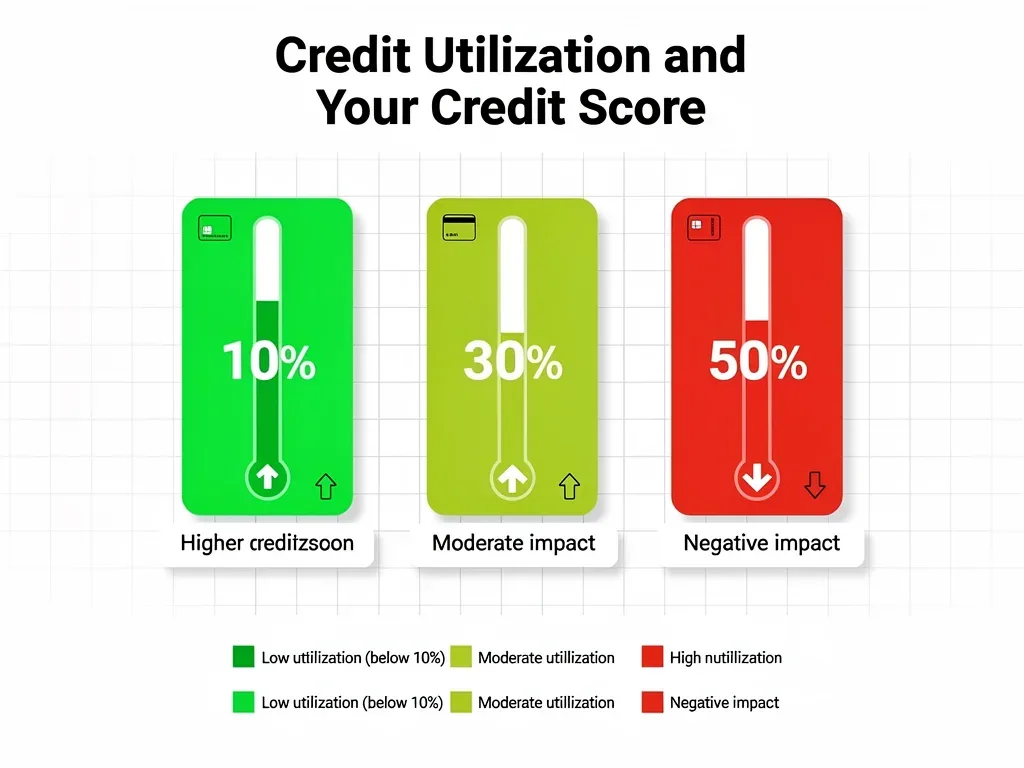
Historically, a credit utilization ratio below 30% has been widely recommended as a healthy benchmark. However, as credit scoring models become more sophisticated and data-driven, the optimal threshold for maximizing your score is shifting. By 2026, evidence suggests that maintaining a ratio below 10% will become increasingly crucial for significant credit score improvements.
This lower threshold reflects a more conservative approach to credit risk assessment. Lenders are increasingly looking for borrowers who not only manage their payments but also demonstrate a minimal reliance on their credit lines, indicating strong financial discipline and lower default risk.
The analytical shift in credit scoring
Advanced algorithms employed by credit bureaus are now capable of analyzing subtle patterns in consumer behavior. A consistent credit utilization below 10% signals exceptional financial health, distinguishing these individuals from those who merely stay below the traditional 30% mark. This distinction is what can translate into an additional boost to your score.
- Enhanced Trust: Low utilization builds trust with lenders, signifying responsible borrowing.
- Reduced Risk Perception: Borrowers with minimal utilization are seen as less likely to default.
- Competitive Edge: A sub-10% ratio can differentiate you in a competitive lending market.
The 10% threshold isn’t arbitrary; it’s a reflection of evolving financial analytics. It suggests that while using credit is good, using it sparingly is even better. This behavior indicates a robust financial foundation, making you a more attractive borrower.
Therefore, aiming for a credit utilization ratio below 10% is not just a recommendation but a strategic imperative for those looking to achieve top-tier credit scores by 2026. This proactive approach will position you favorably for future financial opportunities.
The 25-point boost: reality or myth?
The idea of a specific 25-point credit score boost from maintaining a credit utilization ratio below 10% might seem like a bold claim. However, numerous studies and anecdotal evidence from financial experts suggest this is a very real possibility, especially as credit scoring models continue to refine their assessment criteria. This isn’t a guaranteed outcome for everyone, but it represents the potential impact for individuals with otherwise healthy credit profiles.
The exact increase can vary based on several factors, including your current credit score, the length of your credit history, and the overall composition of your credit report. For someone with an already excellent score, the boost might be less dramatic, but for those in the good to very good range, this targeted strategy can yield significant improvements.
Factors influencing the score increase
While a low utilization ratio is powerful, it doesn’t operate in a vacuum. Other elements of your credit report contribute to the final score increase:
- Payment History: Consistent on-time payments are foundational.
- Credit History Length: Longer histories generally lead to higher scores.
- Credit Mix: A healthy mix of different credit types (e.g., installment loans, revolving credit) is beneficial.
- New Credit: Opening too many new accounts in a short period can temporarily lower your score.
The 25-point potential boost is a synergistic effect. When a low credit utilization ratio is combined with these other positive credit behaviors, the impact is amplified. It signifies a holistic approach to financial responsibility that credit bureaus reward.
Ultimately, the 25-point boost is not a myth but a realistic and achievable goal for many. It underscores the importance of strategic credit management, where every positive action contributes to a stronger financial future.
Strategies to maintain utilization below 10%
Achieving and sustaining a credit utilization ratio below 10% requires deliberate planning and consistent effort. It’s not just about spending less, but about smart credit management that maximizes your available credit while minimizing your reported balances. These strategies are particularly pertinent as we look towards 2026, where this threshold gains even more weight.
One of the most effective methods is to pay down your balances multiple times a month, rather than waiting for your statement due date. This ensures that the balance reported to credit bureaus is always as low as possible, even if you use your card frequently.
Practical tips for low utilization
- Pay Balances Frequently: Make small payments throughout the month instead of one large payment.
- Increase Credit Limits: Request a credit limit increase on existing cards, but only if you trust yourself not to spend more. This instantly lowers your ratio.
- Open New Credit Responsibly: If you have a solid credit history, opening a new card can increase your total available credit, but avoid doing so too frequently.
- Avoid Maxing Out Cards: Even if you pay them off, temporarily high balances can be reported and affect your score.
Another often-overlooked strategy is to understand your credit card’s statement closing date. The balance reported to credit bureaus is typically the one on your statement closing date, not your payment due date. By paying off a significant portion of your balance before the closing date, you can ensure a low utilization is reported.
By implementing these strategies, you can proactively manage your credit utilization and consistently keep it below the crucial 10% mark, setting yourself up for optimal credit health in 2026 and beyond.
Future trends in credit scoring for 2026
The landscape of credit scoring is in a perpetual state of evolution, driven by technological advancements and changing economic realities. As we move closer to 2026, several key trends are emerging that will further emphasize the importance of metrics like credit utilization, while also introducing new considerations for consumers.
One significant trend is the increasing use of alternative data. While traditional factors like payment history and utilization will remain foundational, credit bureaus are exploring data points beyond conventional credit reports. This could include utility payments, rental history, and even banking transaction data, providing a more comprehensive view of financial behavior.
The role of AI and machine learning
Artificial intelligence and machine learning algorithms are at the forefront of this evolution. These technologies enable credit scoring models to process vast amounts of data more efficiently and identify complex patterns that human analysts might miss. This leads to more nuanced and predictive scores, making it even more critical for consumers to maintain excellent financial habits.
- Personalized Scoring: AI can tailor risk assessments to individual financial profiles.
- Dynamic Adjustments: Scores may react more quickly to changes in financial behavior.
- Fraud Detection: Enhanced capabilities for identifying and preventing fraudulent activities.
Another trend is the emphasis on financial wellness beyond just creditworthiness. Lenders are beginning to look at a borrower’s overall financial stability, including savings habits and emergency funds, as indicators of their ability to manage debt. This holistic view means that a low credit utilization ratio will not just be a standalone positive but a component of a larger picture of financial health.
In summary, while the core principles of good credit management will endure, the future of credit scoring in 2026 will be characterized by greater sophistication and a broader scope of data analysis. Adapting to these trends by focusing on metrics like a sub-10% credit utilization will be vital.
Long-term benefits of low credit utilization
The advantages of maintaining a low credit utilization ratio extend far beyond a temporary boost to your credit score. This disciplined approach to credit management cultivates a strong financial foundation that can yield significant long-term benefits, impacting various aspects of your financial life for years to come. It’s an investment in your future financial well-being.
One of the most immediate long-term benefits is access to better financial products. Lenders reserve their most competitive interest rates, favorable terms, and exclusive offers for borrowers with the highest credit scores. A consistently low utilization ratio positions you among this elite group, potentially saving you thousands of dollars over the life of loans and credit lines.
Enhanced financial flexibility and opportunities
A stellar credit score, significantly influenced by low utilization, also provides unparalleled financial flexibility. When unexpected expenses arise or new opportunities present themselves, you’ll have the confidence that you can access credit on favorable terms. This might mean securing a mortgage with a lower interest rate, qualifying for a car loan with minimal payments, or even accessing business financing more easily.
- Lower Interest Rates: Significant savings on mortgages, auto loans, and personal loans.
- Easier Loan Approvals: Quicker and smoother approval processes for various credit products.
- Better Insurance Premiums: Some insurers use credit scores to determine rates, leading to potential savings.
- Renter Advantage: Landlords often check credit scores, giving you an edge in competitive rental markets.
Furthermore, a strong credit history built on responsible utilization can open doors to non-financial benefits, such as easier approval for utility services without large deposits, or even certain employment opportunities where financial responsibility is a key criterion. It essentially acts as a financial passport, granting you access to a world of opportunities.
In essence, cultivating a low credit utilization ratio is not merely a tactic for a quick score boost; it’s a foundational pillar of lasting financial health, ensuring you are prepared for whatever financial journey lies ahead.
Common pitfalls and how to avoid them
While the benefits of maintaining a low credit utilization ratio are clear, many consumers inadvertently fall into common traps that can undermine their efforts. Being aware of these pitfalls and actively working to avoid them is just as crucial as implementing positive strategies, especially in the evolving credit landscape of 2026.
One frequent mistake is focusing solely on the aggregate utilization ratio across all cards, while neglecting individual card utilization. Even if your overall ratio is low, maxing out a single credit card can still send a negative signal to credit bureaus, potentially impacting your score.
Avoiding credit utilization mistakes
- Ignoring Statement Closing Dates: Balances are reported on these dates, not payment due dates. Pay down before the closing date.
- Closing Old Accounts: Closing old, paid-off credit cards reduces your total available credit, which can increase your utilization ratio. Keep them open if they have no annual fee and you don’t need them.
- Applying for Too Much New Credit: While new credit can increase your available credit, multiple hard inquiries in a short period can temporarily lower your score.
- Not Monitoring Your Credit Report: Regularly check your credit report for errors or fraudulent activity that could artificially inflate your reported balances.
Another common pitfall is the misconception that carrying a small balance helps your score. This is false. Paying off your balance in full each month is the best practice. While carrying a balance does show activity, it also incurs interest and doesn’t improve your score more than paying it off completely. In fact, consistently paying interest can be a sign of over-reliance on credit.
By diligently avoiding these common mistakes and staying informed about credit reporting practices, you can effectively navigate the complexities of credit utilization and ensure your efforts to maintain a low ratio translate into the desired credit score improvements.
| Key Point | Brief Description |
|---|---|
| 10% Utilization Target | Aiming for credit utilization below 10% is becoming crucial for optimal credit scores by 2026, moving beyond the traditional 30% benchmark. |
| Potential Score Boost | Maintaining this low ratio can potentially increase your credit score by up to 25 points, especially for those in the good-to-very-good range. |
| Strategic Management | Strategies include frequent payments, requesting credit limit increases, and understanding statement closing dates to report lower balances. |
| Long-Term Benefits | A low utilization ratio leads to better loan terms, increased financial flexibility, and enhanced opportunities for various financial products. |
Frequently asked questions about credit utilization
What is credit utilization and why is it important for my credit score?▼Credit utilization is the percentage of your total available credit that you are currently using. It’s crucial because it accounts for a significant portion (around 30%) of your credit score, signaling to lenders how responsibly you manage your debt. A lower ratio indicates less risk and better financial health.
How can maintaining utilization below 10% specifically boost my score by 25 points?▼While not a guaranteed exact figure for everyone, consistently keeping your utilization below 10% signals exceptional financial discipline. Modern credit scoring models, particularly by 2026, are increasingly rewarding this behavior, differentiating you from those with higher ratios and potentially adding up to 25 points to your score when combined with other good habits.
What are the best strategies to keep my credit utilization below 10%?▼Effective strategies include making multiple payments throughout the month, especially before your statement closing date, requesting credit limit increases (without increasing spending), and being judicious about opening new credit accounts. Always aim to pay your balances in full whenever possible.
Will closing an old credit card help or hurt my credit utilization ratio?▼Closing an old credit card typically hurts your credit utilization ratio. This is because it reduces your total available credit, making your current outstanding balances a larger percentage of your overall limit. It’s generally better to keep old, paid-off accounts open, especially if they have no annual fee.
How often should I check my credit utilization and credit score?▼It’s advisable to monitor your credit utilization at least monthly, particularly before your credit card statement closing dates. Checking your credit score regularly, perhaps quarterly, allows you to track progress and identify any unexpected changes promptly, ensuring you stay on top of your financial health.
Conclusion
As we navigate the evolving financial landscape towards 2026, the significance of credit utilization ratios cannot be overstated. The shift towards a sub-10% benchmark for optimal credit health represents a pivotal development in how creditworthiness is assessed. By understanding and actively managing your credit utilization, not only can you potentially unlock a substantial boost of 25 points to your credit score, but you also lay the groundwork for enduring financial stability and access to a wider array of favorable financial opportunities. This proactive approach to credit management is more than just a tactic; it’s a fundamental pillar of responsible personal finance in the modern era.