Hard Inquiries 2026: Limiting 2 Annually to Prevent 5-Point Credit Drop
Advertisements
Limiting hard inquiries to two annually in 2026 is crucial for protecting your credit score, as each additional inquiry can lead to a noticeable five-point reduction, impacting your financial opportunities significantly.
As we approach 2026, understanding the nuances of credit management becomes more critical than ever, especially regarding hard inquiries in 2026. These seemingly minor actions can have a disproportionately large impact on your credit score, potentially causing a significant five-point drop with each instance. This guide will help you navigate the complexities of hard inquiries and empower you to maintain a robust financial standing.
Understanding Hard Inquiries and Their Impact
Hard inquiries are a fundamental component of the credit scoring system, yet their implications are often misunderstood. When you apply for new credit, be it a loan, a new credit card, or a mortgage, the lender typically requests a copy of your credit report from one of the major credit bureaus. This request is recorded as a hard inquiry, signaling to other lenders and the credit scoring models that you are seeking new credit.
The core issue with hard inquiries lies in their potential to signal increased risk. Lenders view multiple hard inquiries within a short period as a sign of potential financial distress or an over-reliance on credit. This perception can make you appear less creditworthy, leading to higher interest rates or even denial of credit. It’s not just about the number, but also the timing and context of these inquiries.
What Triggers a Hard Inquiry?
Understanding the specific actions that result in a hard inquiry is the first step towards managing them effectively. Many consumers are unaware that certain everyday financial decisions can trigger these score-impacting events.
- Applying for a new credit card, even if you don’t intend to use it immediately.
- Seeking a personal loan for debt consolidation or a significant purchase.
- Applying for a mortgage or a home equity line of credit.
- Leasing a car or applying for an auto loan.
- Opening a new utility account in some cases, particularly for services requiring significant upfront investment.
Each of these actions, when initiated by you, grants a lender permission to pull your credit report, resulting in a hard inquiry. It’s crucial to distinguish these from ‘soft inquiries,’ which do not affect your credit score.
The Five-Point Drop: A Closer Look
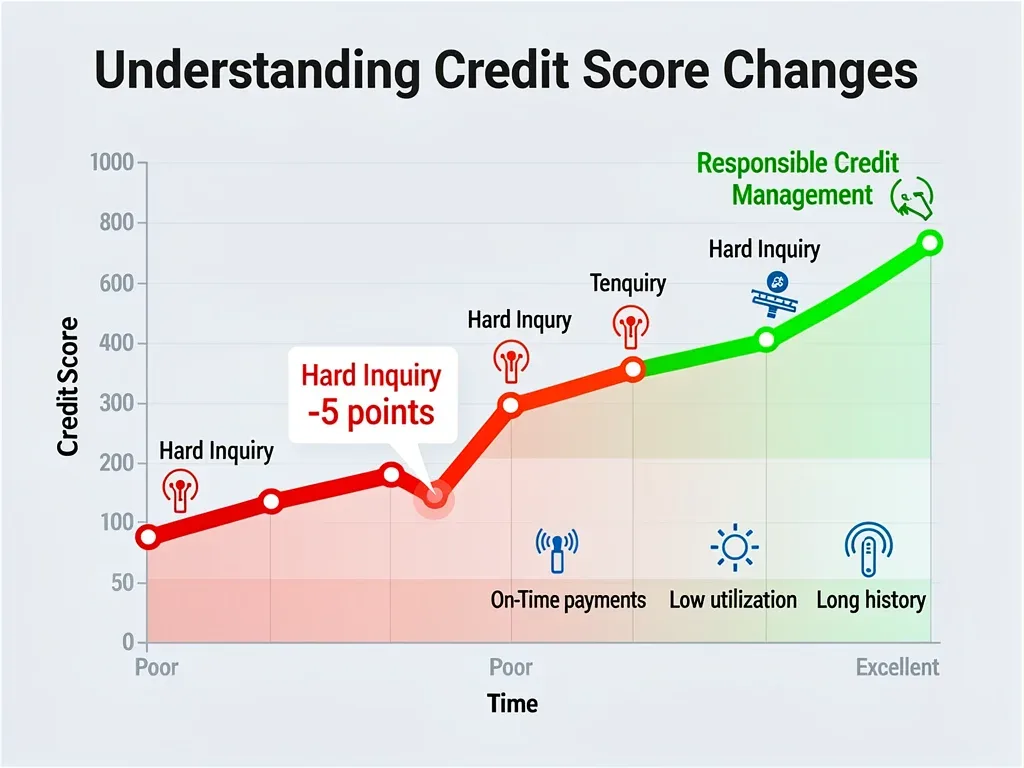
The common wisdom is that a single hard inquiry can shave off a few points from your credit score, typically between 2 and 5 points. While this might seem minor in isolation, the cumulative effect can be substantial, especially for those with already marginal scores or those planning significant financial moves. In 2026, with evolving credit models, this 5-point drop per inquiry could become a more consistent reality, making proactive management essential.
The impact isn’t just immediate; hard inquiries remain on your credit report for two years, though their influence on your score typically diminishes after the first year. However, within that initial year, multiple inquiries can compound the negative effect, making it harder to secure favorable terms for future loans. This emphasizes the importance of strategic credit applications.
The 2026 Landscape: Evolving Credit Models
The financial world is dynamic, and credit scoring models are no exception. As we look towards 2026, it’s reasonable to anticipate further refinements and potentially stricter interpretations of credit behavior. These changes are often driven by economic shifts, technological advancements in data analysis, and a continuous effort to more accurately assess borrower risk. The emphasis on limiting hard inquiries in 2026 is not merely a suggestion but a strategic imperative.
Credit bureaus and lenders are constantly seeking better ways to predict repayment behavior. This means that factors previously considered minor might gain more weight, and conversely, some factors might become less significant. For hard inquiries, the trend suggests a move towards greater scrutiny, especially for consumers who appear to be accumulating debt rapidly.
Anticipated Changes in Credit Scoring
While the core principles of credit scoring remain stable, the weighting of various factors can shift. In 2026, we might see more sophisticated algorithms that can better differentiate between ‘rate shopping’ (where a consumer checks rates from multiple lenders for a single loan) and genuinely seeking multiple lines of credit. However, until such differentiation is universally applied and clearly understood, the safest approach is to minimize inquiries.
- Increased granularity in risk assessment for new credit applications.
- Potential for more immediate and pronounced score drops from multiple inquiries.
- Greater emphasis on the recency and frequency of credit-seeking behavior.
- The introduction of new data points to supplement traditional credit files.
These potential changes underscore the need for consumers to be more vigilant about their credit activity. The old adage ‘knowledge is power’ truly applies here, as understanding these shifts can help you adapt your financial strategies.
Why Limiting Inquiries is Crucial
Limiting hard inquiries isn’t just about avoiding a few lost points; it’s about preserving your financial flexibility and securing the best possible terms on future borrowing. A higher credit score translates directly into lower interest rates on mortgages, car loans, and credit cards, saving you potentially thousands of dollars over the life of a loan. In a competitive lending environment, every point matters.
Furthermore, a strong credit score can open doors to other opportunities, such as lower insurance premiums, better rental agreements, and even certain employment opportunities. By proactively managing your hard inquiries, you are not just protecting your credit score; you are investing in your overall financial well-being. The goal for 2026 should be to approach credit applications with deliberate strategy, not impulsive action.
Strategic Credit Application: Best Practices for 2026
Navigating the credit landscape effectively requires a strategic mindset, particularly as we head into 2026. The goal is to minimize the negative impact of hard inquiries while still accessing the credit you need. This involves careful planning, understanding your financial position, and making informed decisions about when and how to apply for credit. Proactive management of your credit profile is key to limiting hard inquiries in 2026.
One of the most effective strategies is to consolidate your credit-seeking activities. If you know you’ll need multiple types of credit, such as a car loan and a personal loan, try to space them out or apply within a very narrow window if credit scoring models treat them as a single search (like mortgage rate shopping). However, this ‘rate shopping’ grace period typically applies only to specific loan types, so general caution is advised.
Pre-Qualification vs. Full Application
A crucial distinction to understand is between pre-qualification and a full credit application. Many lenders offer pre-qualification processes that involve a soft inquiry. This allows you to gauge your eligibility and potential interest rates without impacting your credit score. It’s an excellent way to shop around and compare offers before committing to a hard inquiry.
- Pre-qualification: Uses a soft inquiry, no impact on credit score. Provides an estimate of eligibility and rates.
- Full Application: Triggers a hard inquiry, potentially lowering your credit score. Required for final approval and funding.
Always opt for pre-qualification whenever available. This allows you to narrow down your options to the most favorable ones, ensuring that when you do submit a full application, it’s for a product you are likely to be approved for and that offers competitive terms. This reduces the need for multiple hard inquiries.
Planning Your Credit Needs Annually
A disciplined approach to credit applications involves looking at your financial needs over a 12-month period. If you anticipate needing a new car, a home renovation loan, or a new credit card, try to plan these applications strategically. The recommendation to limit yourself to two hard inquiries annually is a strong guideline for a reason: it minimizes cumulative damage.
Consider the timing: avoid applying for multiple types of credit simultaneously unless absolutely necessary and within a recognized rate-shopping window. For instance, if you’re buying a home, multiple mortgage inquiries within a 14-45 day period are typically treated as a single inquiry. However, applying for a mortgage and a new credit card at the same time will likely result in two distinct hard inquiries.
Minimizing Unnecessary Hard Inquiries
Beyond strategic planning, there are practical steps you can take to actively minimize the number of hard inquiries on your credit report. Many inquiries are avoidable with a bit of foresight and knowledge about how your credit is accessed. Being proactive in managing your credit file is paramount to limiting hard inquiries in 2026.
One common scenario for unnecessary hard inquiries arises from not being fully prepared when applying for credit. This includes not knowing your current credit score, not understanding what lenders are looking for, or applying for credit you are unlikely to qualify for. Each rejected application still results in a hard inquiry, adding to the negative impact without any benefit.
Checking Your Credit Score Regularly
Regularly monitoring your credit score and report is a powerful preventative measure. Many credit card companies and financial institutions now offer free access to your credit score. Additionally, you are entitled to a free copy of your credit report from each of the three major credit bureaus (Equifax, Experian, and TransUnion) annually via AnnualCreditReport.com.
- Utilize free credit monitoring services offered by banks or credit card providers.
- Obtain your free annual credit report from AnnualCreditReport.com to check for errors or unauthorized inquiries.
- Understand the factors influencing your score so you can address weaknesses before applying for new credit.
By staying informed about your credit health, you can make more strategic decisions about when and where to apply for new credit, reducing the likelihood of unnecessary hard inquiries.
Avoiding Impulsive Credit Applications
It’s easy to be tempted by promotional offers for new credit cards, especially those with enticing sign-up bonuses. However, each application is a hard inquiry. Before applying, ask yourself if you truly need the credit and if it aligns with your long-term financial goals. An impulsive application for a store credit card to save 10% on a single purchase might not be worth the potential credit score drop.
Instead, cultivate a habit of thoughtful consideration before any credit application. Research the terms, assess your need, and evaluate the potential impact on your credit score. This disciplined approach will serve you well in minimizing hard inquiries and maintaining a healthy credit profile as 2026 approaches.
The Long-Term Benefits of Limited Inquiries
While the immediate impact of a hard inquiry might seem small, the cumulative and long-term benefits of limiting them are significant. A consistent strategy of minimizing hard inquiries contributes to a stronger, more stable credit profile, which in turn unlocks better financial opportunities and greater peace of mind. For those focused on their financial future, especially in 2026 and beyond, this is a non-negotiable aspect of credit management.
A high credit score is not just a number; it’s a reflection of your financial responsibility and reliability. Lenders view it as a strong indicator of your ability to manage debt, making you a more attractive borrower. This translates into tangible financial advantages that can save you a substantial amount of money over time.
Improved Borrowing Power and Terms
One of the most direct benefits of a high credit score, maintained by limiting hard inquiries, is improved borrowing power. Lenders are more willing to offer larger loan amounts and more favorable terms, including lower interest rates and longer repayment periods, to individuals with excellent credit.
- Access to lower interest rates on mortgages, auto loans, and personal loans.
- Higher credit limits on credit cards, providing greater financial flexibility.
- Easier approval for various types of credit, reducing stress and uncertainty.
- Potential for better terms on insurance policies, as credit scores can influence premiums.
These benefits are not merely theoretical; they translate into real savings. Over the life of a 30-year mortgage, even a half-percentage point difference in interest can amount to tens of thousands of dollars. By limiting your hard inquiries in 2026, you are essentially investing in these future savings.
Enhanced Financial Stability and Opportunities
Beyond direct borrowing costs, a strong credit score fostered by careful inquiry management contributes to overall financial stability. It provides a buffer against unexpected financial challenges and opens doors to a wider range of financial products and services. This can include premium credit cards with superior rewards programs or exclusive financial services.
Furthermore, a robust credit history can be advantageous in non-lending situations, such as renting an apartment or even securing certain jobs, where employers may review credit reports. By making conscious decisions about hard inquiries, you are building a foundation for a more secure and prosperous financial future, ensuring that you are well-positioned for whatever 2026 and subsequent years may bring.
Dispelling Myths About Hard Inquiries
There are several common misconceptions surrounding hard inquiries that can lead consumers to make less-than-optimal credit decisions. Understanding the reality behind these myths is essential for effective credit management and for successfully limiting hard inquiries in 2026. Accurate information empowers you to protect your credit score more effectively.
One prevalent myth is that all inquiries are equally damaging. While a single hard inquiry typically has a minor impact, the context and frequency are critical. Another common misunderstanding is that checking your own credit report will hurt your score, which is simply not true when done correctly.
Myth 1: All Inquiries Are Equal
Not all hard inquiries are treated the same way by credit scoring models. As mentioned earlier, ‘rate shopping’ for a single loan type, such as a mortgage or an auto loan, within a concentrated period (typically 14 to 45 days, depending on the scoring model) is often grouped and treated as a single inquiry. This allows consumers to compare offers without undue penalty.
- Mortgage inquiries within a specific window are often consolidated.
- Auto loan inquiries within a specific window are often consolidated.
- Credit card applications, personal loans, or other diverse credit products are usually treated as separate inquiries.
The key takeaway is to be aware of these grace periods for specific loan types, but to generally avoid applying for different types of credit simultaneously. Always assume that inquiries for different financial products will be counted individually.
Myth 2: Checking Your Own Credit Hurts Your Score
This is perhaps one of the most persistent myths. When you check your own credit report or score through a reputable service (like your bank, a credit monitoring service, or AnnualCreditReport.com), it results in a ‘soft inquiry.’ Soft inquiries are visible only to you and do not impact your credit score in any way. They are crucial for monitoring your financial health and identifying potential errors or fraud.
Conversely, a hard inquiry occurs when a lender pulls your credit report as part of a credit application process. The distinction between soft and hard inquiries is vital for consumers to understand, as it encourages proactive credit monitoring without fear of negative repercussions. Regular self-checks are a cornerstone of good credit hygiene and will help you prepare for any necessary hard inquiries in 2026.
Future-Proofing Your Credit in 2026
As we advance towards 2026, the emphasis on credit health and responsible financial behavior will only grow. Future-proofing your credit means adopting practices that not only protect your current score but also position you for long-term financial success. This holistic approach goes beyond merely avoiding hard inquiries; it involves cultivating strong financial habits that resonate positively with credit scoring models.
The financial landscape is constantly evolving, with new products, services, and regulatory changes emerging. Staying informed and adaptable is crucial. By building a robust credit foundation now, you ensure that you are well-equipped to handle future financial opportunities and challenges.
Beyond Hard Inquiries: A Holistic Approach
- Payment History: Always pay your bills on time. This is the single most important factor in your credit score.
- Credit Utilization: Keep your credit card balances low relative to your credit limits, ideally below 30%.
- Length of Credit History: The longer your credit accounts have been open and in good standing, the better. Avoid closing old, unused accounts unless absolutely necessary.
- Credit Mix: Having a healthy mix of credit types (e.g., credit cards, installment loans) can be beneficial, but only if managed responsibly.
By focusing on these pillars of credit health, you create a resilient financial profile that can withstand minor fluctuations and position you favorably for significant financial milestones, such as purchasing a home or starting a business.
Embracing Technology for Credit Management
Technology offers powerful tools for managing your credit effectively. Many apps and online platforms provide real-time credit monitoring, alerts for suspicious activity, and personalized advice. Leveraging these resources can help you stay on top of your credit health and proactively address any issues.
Set up payment reminders, utilize budgeting tools, and regularly review your financial statements. These digital tools can act as your personal financial assistant, ensuring you don’t miss payments or inadvertently trigger unnecessary hard inquiries. Embracing these technological aids will be a key differentiator for savvy consumers looking to optimize their credit scores and navigate the complexities of hard inquiries in 2026 with confidence.
| Key Point | Brief Description |
|---|---|
| Hard Inquiry Impact | Each hard inquiry can cause a 5-point credit score drop, visible for two years. |
| 2026 Focus | Anticipated stricter credit models make limiting inquiries crucial for financial health. |
| Strategic Applications | Utilize pre-qualification and plan credit needs annually to avoid unnecessary inquiries. |
| Myth vs. Reality | Soft inquiries (self-checks) do not affect scores, unlike hard inquiries from lenders. |
Frequently Asked Questions About Hard Inquiries
What is a hard inquiry and why does it affect my credit score?▼A hard inquiry occurs when a lender checks your credit report after you apply for new credit, such as a loan or credit card. It signals you’re seeking more debt, which lenders interpret as increased risk, potentially causing a minor, usually 2-5 point, drop in your score.
How long do hard inquiries stay on my credit report?▼Hard inquiries typically remain on your credit report for two years. However, their impact on your credit score usually diminishes after the first year. It’s still important to limit them, especially if you plan major financial applications soon.
Is there a difference between a hard inquiry and a soft inquiry?▼Yes, a significant difference. Hard inquiries, triggered by credit applications, impact your score. Soft inquiries, like checking your own credit or pre-qualifying for a loan, do not affect your score and are only visible to you.
How many hard inquiries are too many in a year?▼While there’s no strict universal limit, generally, more than two hard inquiries in a 12-month period can start to negatively impact your score more significantly. Lenders may view multiple inquiries as a sign of financial instability or over-reliance on credit.
Can I remove hard inquiries from my credit report?▼You can only remove hard inquiries if they are unauthorized or inaccurate. If you legitimately applied for credit, the inquiry will remain for two years. Always dispute any inquiries you don’t recognize by contacting the credit bureau directly.
Conclusion
As we look towards 2026, the importance of carefully managing hard inquiries in 2026 cannot be overstated. Understanding that each hard inquiry can result in a potential five-point credit score drop underscores the necessity of a strategic and informed approach to seeking new credit. By embracing practices like pre-qualification, annual credit planning, and regular credit monitoring, consumers can effectively minimize unnecessary inquiries and safeguard their financial health. A strong credit score is a cornerstone of financial stability, unlocking better borrowing terms and broader opportunities. Proactive credit management, focused on limiting hard inquiries and maintaining overall credit hygiene, is not just a recommendation but a vital strategy for navigating the evolving financial landscape with confidence and securing a prosperous future.