2026 Credit Report Dispute: Remove Errors in 30 Days
Advertisements
Effectively navigating the 2026 credit report dispute process is crucial for financial well-being, enabling consumers to swiftly identify and remove inaccuracies within a 30-day timeframe to safeguard their credit scores.
Understanding and mastering the Navigating the 2026 Credit Report Dispute Process: A Step-by-Step Guide to Removing Errors Within 30 Days is more critical than ever. In an increasingly digital financial landscape, credit reports are the bedrock of financial opportunities, and even a minor error can have significant consequences. This comprehensive guide will walk you through the essential steps to identify, dispute, and swiftly remove inaccuracies from your credit report, aiming for resolution within a month.
Understanding Your 2026 Credit Report: The Foundation of Dispute
Before you can effectively dispute errors, you must first understand what constitutes your credit report and why its accuracy is paramount. In 2026, credit reports continue to be a detailed summary of your credit history, compiled by credit bureaus from information provided by lenders. These reports are used by banks, landlords, employers, and even insurance companies to assess your financial reliability. Any inaccuracies can lead to higher interest rates, denied applications, or missed opportunities, making proactive management indispensable.
The three major credit bureaus in the United States—Equifax, Experian, and TransUnion—each maintain separate reports. While they often contain similar information, discrepancies can and do occur. It’s crucial to obtain a copy from each bureau to ensure a thorough review. Federal law mandates that you are entitled to a free copy of your credit report from each bureau once every 12 months, accessible through AnnualCreditReport.com. This right is your first line of defense against errors and the starting point for the 2026 credit report dispute process.
What to look for in your credit report
When reviewing your credit report, vigilance is key. You’re searching for anything that doesn’t look right or doesn’t belong to you. This includes identifying accounts you don’t recognize, incorrect payment statuses, or outdated information that should have been removed. The details matter, and even small errors can collectively impact your credit score significantly. Pay close attention to personal information, account histories, and public records, as these sections are common sources of inaccuracies.
- Personal Information: Verify your name, address, Social Security number, and date of birth. Any misspellings or incorrect data could indicate identity theft or a mix-up with another consumer.
- Account Information: Check all listed accounts, including credit cards, loans, and mortgages. Confirm that account numbers, balances, payment histories, and opening/closing dates are accurate. Look for accounts you didn’t open or those incorrectly marked as delinquent.
- Public Records and Collections: Ensure that any bankruptcies, foreclosures, or civil judgments listed are correct and belong to you. Also, verify collection accounts, their amounts, and the original creditor.
- Inquiries: Review hard inquiries. These occur when you apply for new credit. Too many inquiries in a short period can negatively affect your score. Ensure all listed inquiries are legitimate and authorized by you.
Understanding the components of your credit report is the foundational step in protecting your financial health. By meticulously examining each section, you empower yourself to identify potential errors that could undermine your creditworthiness. This initial review sets the stage for a successful 2026 credit report dispute, ensuring you only dispute what is genuinely incorrect and have the necessary information to support your claims.
Identifying Common Credit Report Errors in 2026
Even with advancements in data management, credit report errors persist, and knowing what to look for can save you significant time and financial strain. These inaccuracies can range from simple data entry mistakes to more complex issues stemming from identity theft. Being able to quickly pinpoint these discrepancies is crucial for a timely resolution within the 30-day target for your 2026 credit report dispute.
Many errors are surprisingly common and can be overlooked if you’re not careful. These can include incorrect account statuses, such as an account being reported as open when it’s closed, or a payment being marked late when it was on time. Such errors directly impact your payment history, which is a major factor in credit scoring. Furthermore, duplicate accounts or mixed files, where your information is combined with someone else’s, can create a confusing and inaccurate financial picture.
Types of errors to actively seek out
A proactive approach to reviewing your credit report means actively searching for specific types of errors. These often fall into distinct categories, each requiring a particular method of verification and documentation. Recognizing these patterns can streamline your dispute process and increase your chances of a quick and favorable outcome.
- Identity Errors: Incorrect name, address, phone number, or Social Security number. These can lead to mixed files or indicate identity theft.
- Incorrect Account Status: Accounts reported as open when closed, accounts listed as delinquent when payments were on time, or incorrect credit limits/balances.
- Duplicate Accounts: The same account listed multiple times, which can artificially inflate your credit utilization or number of open accounts.
- Outdated Information: Negative information (like bankruptcies or late payments) remaining on your report beyond the legal reporting period (typically 7-10 years).
- Fraudulent Accounts: Accounts opened in your name without your knowledge or authorization, a clear sign of identity theft.
Being familiar with these common errors empowers you to conduct a more effective review of your credit reports. Each identified error is a critical piece of information that you will need to document and present during the dispute process. The clearer your understanding of what constitutes an error, the more efficiently you can proceed with the next steps of your 2026 credit report dispute.
Gathering Evidence: Your Key to a Successful Dispute
Once you’ve identified errors on your credit report, the next critical step in the 2026 credit report dispute process is to gather compelling evidence. Without proper documentation, your dispute may be dismissed or delayed. Think of this stage as building a strong case; the more evidence you have to support your claim, the higher your chances of a successful and swift resolution within the 30-day timeframe. This evidence will directly contradict the inaccurate information reported by the credit bureaus or furnishers.
The nature of the evidence will depend on the type of error you’re disputing. For example, if you’re disputing a late payment, bank statements or canceled checks proving on-time payments are essential. If an account is inaccurately reported as yours, a police report for identity theft or a letter from the actual account holder might be necessary. The goal is to provide clear, irrefutable proof that the information on your report is incorrect. Organize all your documents meticulously, as a well-structured submission can expedite the review process.
Essential documents for your dispute
Having a checklist of necessary documents can simplify this crucial step. Prepare copies of all relevant records, never sending originals, as they may not be returned. It’s also wise to keep a detailed log of all communications, including dates, names of individuals you speak with, and summaries of conversations. This level of organization demonstrates your commitment to resolving the issue and can be invaluable if further action is required.
- Copies of your credit reports: Highlight the specific errors you are disputing on each report.
- Personal identification: A copy of a government-issued ID (driver’s license, passport) and proof of address (utility bill, bank statement) to verify your identity.
- Proof of payment: Bank statements, canceled checks, or payment receipts if disputing late payments or incorrect balances.
- Account statements: Original account statements showing correct balances or account statuses.
- Correspondence with creditors: Any letters or emails exchanged with the creditor regarding the disputed account.
- Police reports or FTC identity theft reports: If the error is due to identity theft or fraud.
The thoroughness of your evidence gathering directly correlates with the effectiveness of your dispute. By preparing a comprehensive package of supporting documents, you significantly increase the likelihood that the credit bureaus and furnishers will investigate and rectify the errors promptly. This diligence is a cornerstone of successfully navigating the 2026 credit report dispute process and achieving a positive outcome within the desired timeframe.
Initiating the Dispute: Sending Your Letters to Bureaus and Furnishers
With your evidence meticulously gathered, the next step is to formally initiate the dispute process. This involves sending dispute letters to both the credit bureaus and, in some cases, directly to the data furnishers (the companies that reported the information, like banks or lenders). This dual approach can often accelerate the resolution, as both parties are then obligated to investigate the reported inaccuracies. A well-crafted dispute letter is professional, clear, and concise, leaving no room for ambiguity regarding the errors you are challenging.
Each credit bureau has its own online dispute process, which can be convenient for initial submissions. However, many experts still recommend sending dispute letters via certified mail with a return receipt requested. This provides a tangible record of when your letter was sent and received, which can be crucial if you need to escalate your dispute. Remember, the Fair Credit Reporting Act (FCRA) mandates that credit bureaus must investigate disputes within 30 days of receiving them, making timely submission vital for your 2026 credit report dispute.
Crafting an effective dispute letter
Your dispute letter should be professional and include all necessary information to facilitate a quick investigation. Avoid emotional language and stick to the facts. Clearly state which items on your credit report are incorrect, why they are incorrect, and what documentation you are providing as proof. Keep a copy of everything you send, including the dispute letter and all supporting documents.
- Your complete contact information: Name, address, phone number, and Social Security number.
- Credit report details: Clearly state which credit report (Equifax, Experian, or TransUnion) the error appears on, and include the report number if available.
- Specific error identification: Clearly identify each incorrect item, including the account number, creditor name, and the specific inaccurate information.
- Explanation of the error: Briefly explain why you believe the information is incorrect.
- Requested action: State clearly that you are requesting the item be removed or corrected.
- List of enclosed documents: Itemize all supporting evidence you are including.
Sending dispute letters to both credit bureaus and furnishers simultaneously can be an effective strategy. While the bureaus are legally required to investigate, the furnisher also has a responsibility to report accurate information. By notifying both, you increase the pressure for a thorough and prompt investigation, significantly improving your chances of resolving your 2026 credit report dispute within the 30-day timeframe. This proactive step demonstrates your commitment to accuracy and can prevent future reporting errors.
Monitoring Progress and Following Up on Your Dispute
Once you’ve submitted your dispute letters, the work isn’t entirely over. Effective monitoring and diligent follow-up are essential to ensure your 2026 credit report dispute stays on track and resolves within the desired 30-day period. The credit bureaus are legally obligated to investigate and respond within this timeframe, but proactive engagement from your side can help prevent delays and ensure that your case receives the attention it deserves. Keeping a detailed record of all communications and deadlines is paramount during this stage.
After submitting your dispute, you should receive a confirmation from the credit bureau, often with a reference number. This number is vital for tracking the status of your dispute online or over the phone. Regularly checking the status allows you to identify any potential roadblocks or requests for additional information promptly. If the 30-day mark approaches without a resolution or communication, it’s time to initiate follow-up actions to reassert your claim and push for a decision.
Strategies for effective follow-up
Your follow-up strategy should be methodical and persistent. Don’t assume that a lack of communication means the issue is being resolved; it could mean your dispute is stalled. Being prepared to re-submit information or escalate your complaint if necessary is a crucial part of maintaining momentum. Each interaction should be documented, noting dates, times, and the content of conversations.
- Track your dispute online: Use the reference number provided by the credit bureau to check the status of your dispute regularly through their online portals.
- Keep detailed records: Maintain a log of all correspondence, including dates sent/received, names of contacts, and summaries of discussions.
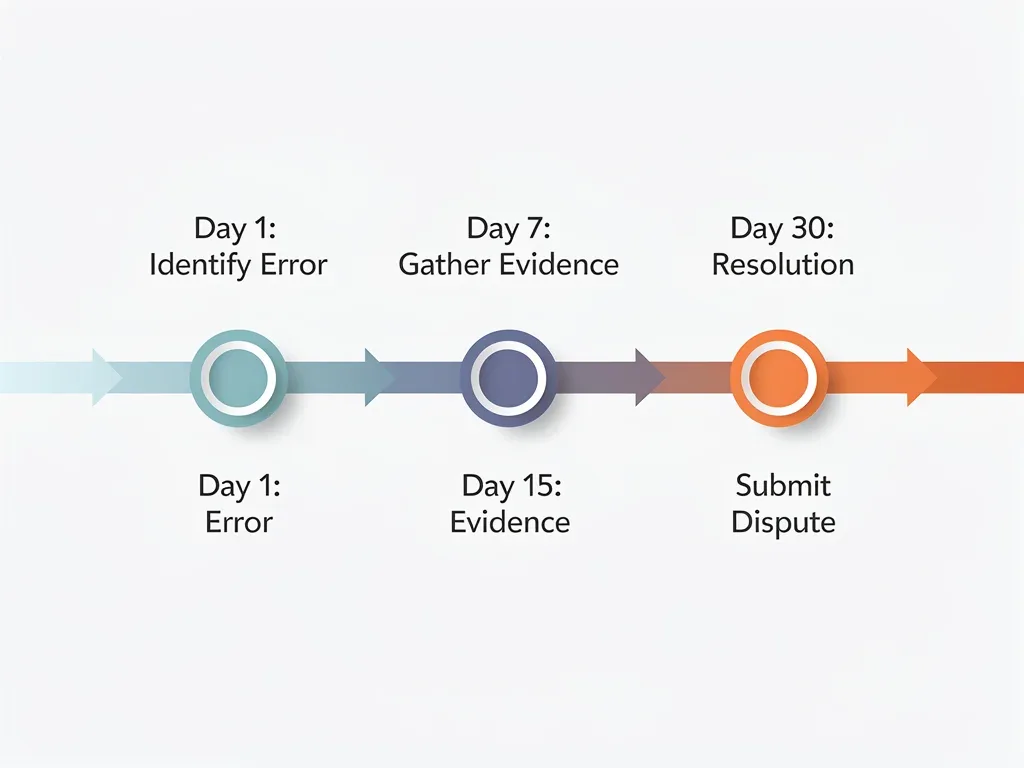
- Follow up after 20-25 days: If you haven’t heard back, consider sending a polite follow-up letter or making a phone call to inquire about the status. Reiterate the urgency of the 30-day resolution.
- Be prepared to resubmit: If information is requested or lost, have copies of your original dispute letter and evidence ready to resubmit quickly.
- Understand the 30-day clock: Remember that the 30-day period starts when the bureau receives your dispute. Be aware of this deadline for timely follow-up.
Diligent monitoring and strategic follow-up are critical components of a successful 2026 credit report dispute. By staying engaged and informed throughout the process, you maximize your chances of achieving a favorable outcome within the stipulated timeframe. This proactive approach not only helps in removing errors but also reinforces your commitment to maintaining an accurate and healthy credit profile.
What Happens After 30 Days? Next Steps if Errors Persist
While the goal of the 2026 credit report dispute process is to resolve errors within 30 days, sometimes disputes take longer or are not resolved to your satisfaction. It’s important to understand your rights and the available avenues for escalation if errors persist beyond this initial period. The Fair Credit Reporting Act (FCRA) provides consumers with significant protections, and knowing how to leverage them can be crucial in compelling credit bureaus and furnishers to act.
If 30 days pass and the errors remain on your report, or if you receive an unfavorable decision, don’t despair. Your options include appealing the decision directly with the credit bureau, filing a complaint with regulatory bodies, or even pursuing legal action. The key is not to give up. Persistent inaccuracies can have long-term financial consequences, so continued advocacy for your credit report’s accuracy is essential. Document every step you take, as this will be vital for any further actions.
Advanced dispute strategies and consumer protection
When initial disputes fail, more advanced strategies come into play. These often involve leveraging consumer protection agencies and understanding the legal framework that governs credit reporting. Knowing who to contact and what information to provide can significantly strengthen your position and increase the pressure on credit bureaus and furnishers to correct their records.
- File an appeal with the credit bureau: If your initial dispute is denied, you have the right to appeal. Provide any new evidence or clarify points from your original dispute.
- Contact the furnisher directly: Even if you initially sent a letter, a direct follow-up with the furnisher (the company that reported the information) can sometimes yield results, especially if you have compelling evidence.
- Submit a complaint to the CFPB: The Consumer Financial Protection Bureau (CFPB) handles complaints about credit reporting issues. They will forward your complaint to the company and work to get a response, often prompting action where direct disputes have failed.
- Contact your state’s Attorney General: Your state’s Attorney General’s office may also be able to assist with consumer protection issues related to credit reporting.
- Consider legal action: If all other avenues fail, and the error is significantly impacting your financial life, consulting with an attorney specializing in consumer law may be an option. They can help you understand if you have grounds for a lawsuit under the FCRA.
Persisting with errors on your credit report can be frustrating, but understanding the steps to take after the initial 30-day period is empowering. By utilizing these advanced dispute strategies and leveraging consumer protection resources, you can continue to advocate for the accuracy of your financial records. This continued effort is crucial for maintaining a healthy credit score and ensuring your financial future remains unhindered by erroneous information in the 2026 credit report dispute landscape.
Preventing Future Errors: Best Practices for Credit Health
Successfully navigating the 2026 credit report dispute process to remove errors is a significant achievement, but preventing future inaccuracies is equally important. Proactive credit health management involves adopting best practices that minimize the chances of errors appearing on your report, ensuring your financial profile remains accurate and strong. This ongoing vigilance is your best defense against the headaches of future disputes and the potential damage to your credit score.
The foundation of prevention lies in consistent monitoring and responsible financial habits. Regularly checking your credit reports, not just annually but perhaps every few months, allows you to catch new errors quickly. Additionally, managing your accounts responsibly—paying bills on time, keeping credit utilization low, and only opening new credit when necessary—reduces the likelihood of legitimate negative information appearing on your report, which can sometimes be misreported as errors.
Essential habits for maintaining an accurate credit report
Cultivating a few key habits can significantly reduce your risk of credit report errors and simplify any future dispute processes, should they arise. These practices are designed to keep you informed, organized, and in control of your financial information. Think of them as an ongoing maintenance plan for your credit health.
- Check your credit reports regularly: Access your free annual reports from each bureau and consider staggered checks throughout the year to catch issues early.
- Review account statements: Cross-reference your monthly bank and credit card statements with what appears on your credit report to ensure consistency.
- Keep meticulous records: Maintain organized files of all financial documents, including loan agreements, payment confirmations, and any correspondence with creditors.
- Be cautious with personal information: Protect your Social Security number and other sensitive data to prevent identity theft, a common source of credit report errors.
- Understand reporting cycles: Be aware of how and when creditors report information to the bureaus, which can help you anticipate updates and identify discrepancies.
- Set up fraud alerts: If you suspect identity theft, place a fraud alert on your credit files to make it harder for fraudsters to open new accounts in your name.
By integrating these best practices into your financial routine, you can significantly reduce the likelihood of encountering errors on your credit report. Prevention is always easier than correction, and a proactive approach to credit health ensures that your financial future remains secure and free from the adverse effects of inaccurate information. This ongoing commitment is the ultimate strategy for long-term success in the evolving landscape of credit reporting and the 2026 credit report dispute environment.
| Key Step | Brief Description |
|---|---|
| Review Reports Annually | Obtain free reports from all three bureaus to identify potential errors. |
| Gather Strong Evidence | Collect all supporting documents to prove the inaccuracy of disputed items. |
| Send Dispute Letters | Formally notify credit bureaus and furnishers via certified mail. |
| Monitor & Follow Up | Track dispute status and follow up diligently to ensure timely resolution. |
Frequently asked questions about credit report disputes
How long does it typically take to resolve a credit report dispute in 2026?▼Under the Fair Credit Reporting Act (FCRA), credit bureaus generally have 30 days to investigate a dispute once they receive it. However, if you provide additional relevant information during that period, they may extend the investigation to 45 days. Aiming for a 30-day resolution requires prompt action and thorough documentation from your side.
Can I dispute errors on my credit report online, or should I mail a letter?▼While online dispute portals offered by credit bureaus are convenient, sending a dispute letter via certified mail with a return receipt requested is often recommended. This creates a clear paper trail, providing undeniable proof of when your dispute was sent and received, which can be crucial if further action is required.
What kind of evidence do I need to support my credit report dispute?▼The evidence needed depends on the error. Common documents include copies of your credit report highlighting errors, personal identification, bank statements, canceled checks, account statements showing correct balances, or police reports for identity theft. The more compelling your evidence, the stronger your case.
What if the credit bureau denies my dispute or doesn’t respond?▼If your dispute is denied or you don’t receive a response within the legal timeframe, you have several options. You can file an appeal with the credit bureau, contact the data furnisher directly, submit a complaint to the Consumer Financial Protection Bureau (CFPB), or consult with an attorney specializing in consumer law.
How can I prevent future errors on my credit report after a successful dispute?▼To prevent future errors, regularly check your credit reports (at least annually), review all account statements meticulously, keep organized financial records, protect your personal information to prevent identity theft, and understand reporting cycles. These habits help maintain an accurate and healthy credit profile.
Conclusion
The ability to effectively navigate the 2026 credit report dispute process: A Step-by-Step Guide to Removing Errors Within 30 Days is an invaluable skill for anyone committed to maintaining financial health. As the financial landscape evolves, the accuracy of your credit report remains a cornerstone of your economic opportunities. By understanding the components of your report, diligently identifying errors, meticulously gathering evidence, and executing a strategic dispute, you empower yourself to rectify inaccuracies swiftly. Remember, the 30-day resolution target is achievable with a proactive and informed approach. Even if challenges arise, persistence and knowledge of your consumer rights provide a clear path forward. Prioritizing the integrity of your credit report is not just about fixing past mistakes, but also about securing a stable and prosperous financial future.