Authorized User Status 2026: 15-Point Credit Score Boost in 6 Months
Advertisements
Authorized user status in 2026 can be a powerful catalyst for credit score improvement, potentially increasing it by 15 points within six months by leveraging the primary cardholder’s positive credit history.
Are you looking for a strategic way to significantly improve your financial standing in the coming year? Understanding how authorized user status in 2026: leveraging it for a 15-point credit score increase in 6 months can be a game-changer for many individuals striving for better credit. This often-underestimated credit-building tool offers a unique pathway to a healthier credit profile, but it requires careful consideration and a clear understanding of its mechanics.
Understanding authorized user status in 2026
The concept of an authorized user has been around for a while, but its implications and effectiveness continue to evolve with credit reporting standards. Essentially, being an authorized user means you are added to someone else’s credit card account, allowing you to make purchases with that card. However, you are not legally responsible for the debt, which remains solely with the primary cardholder.
This arrangement can be particularly beneficial because the primary cardholder’s positive payment history and low credit utilization can reflect positively on your credit report. In 2026, credit bureaus largely still consider this data, making it a viable strategy for credit improvement, provided the primary account is managed responsibly.
What exactly is an authorized user?
An authorized user is someone granted permission by the primary cardholder to use their credit card account. This means you get a card with your name on it, but the account itself belongs to the primary cardholder. Your credit report will typically show the account’s history, including its age, credit limit, and payment behavior.
- Access to credit without direct responsibility for debt.
- Benefits from the primary cardholder’s positive credit behavior.
- No impact on your credit if the primary account is closed (usually).
- Can be removed from the account by the primary cardholder at any time.
The role of credit bureaus in 2026
Credit bureaus like Equifax, Experian, and TransUnion continue to refine how they interpret and weigh authorized user accounts. While some changes have occurred over the years to prevent misuse, the fundamental principle that a well-managed authorized user account can boost a credit score remains relevant. They look for patterns of responsible credit use, which an authorized user account can help establish.
The key for 2026 is that the account’s history, particularly its payment record and credit utilization, is typically factored into your credit score. This means that if the primary cardholder has a long history of on-time payments and keeps their balances low, this positive data can be reported to your credit file, contributing to a higher score.
In essence, authorized user status acts as a bridge, allowing individuals, especially those with limited credit history, to tap into established credit lines and demonstrate their capacity for responsible credit management. It’s a powerful tool, but one that demands a clear understanding of its benefits and potential drawbacks to be truly effective in boosting your credit score.
The mechanics of a 15-point credit score increase
Achieving a 15-point credit score increase within six months through authorized user status is a realistic goal, provided certain conditions are met. This improvement is not magic; it’s a direct result of how positive credit behavior on the primary account influences the various components of your credit score. Understanding these mechanics is crucial for maximizing your gains.
The primary way authorized user status impacts your score is by introducing positive data into your credit report. This data typically includes the age of the account, its credit limit, and its payment history. When these elements are favorable, they can significantly enhance your credit profile, leading to a noticeable score boost.
How authorized user status affects credit factors
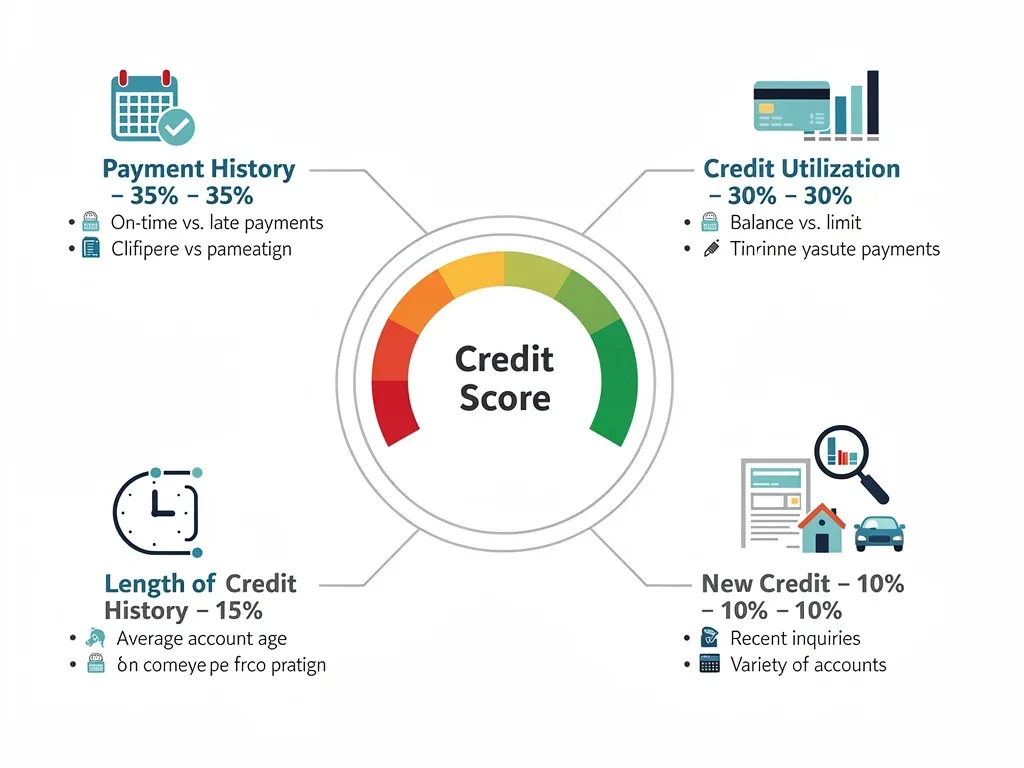
Several key factors contribute to your credit score, and authorized user status can positively influence many of them. The most impactful include payment history, credit utilization, and the length of your credit history. These three components make up a substantial portion of your FICO score, which is widely used by lenders.
- Payment History (35%): If the primary cardholder consistently makes on-time payments, this excellent history will be reported to your credit file.
- Credit Utilization (30%): A low utilization ratio on the primary account (e.g., keeping balances below 30% of the limit) will be beneficial.
- Length of Credit History (15%): Older, well-managed accounts contribute to a longer average credit history, which is positive.
- Credit Mix (10%): Adding a credit card can diversify your credit types, though this is less impactful for a 15-point jump.
The timeline for score improvement
The six-month timeframe for a 15-point increase is achievable because credit reporting typically occurs monthly. As soon as you are added as an authorized user, the account’s history often appears on your credit report within one to two billing cycles. Consistent positive reporting over several months allows these favorable factors to build momentum and influence your score.
Initial changes might be subtle, but over time, the steady influx of positive payment history and low credit utilization data can lead to a measurable increase. It’s not uncommon for individuals to see a 10-20 point jump within this period, especially if they have a thin credit file or are recovering from past credit challenges. The key is consistency and ensuring the primary account holder maintains impeccable credit habits.
By strategically becoming an authorized user on an account with a strong credit profile, you are essentially leveraging someone else’s good financial behavior to your advantage. This method provides a relatively quick and effective way to bolster your credit score, laying a foundation for future financial opportunities.
Choosing the right primary cardholder
The success of leveraging authorized user status hinges almost entirely on the credit habits of the primary cardholder. This is not a decision to be taken lightly, as their financial discipline directly impacts your credit score. In 2026, just as in previous years, selecting the right person is paramount to achieving your credit-building goals.
Ideally, the primary cardholder should be someone you trust implicitly, such as a close family member who has a long history of responsible credit management. Their account should demonstrate consistent on-time payments, low credit utilization, and a substantial credit limit to provide the most benefit to your credit report.
Key characteristics of an ideal primary cardholder
When considering who to ask to add you as an authorized user, look for specific financial characteristics that will maximize the positive impact on your credit score. It’s not just about trust; it’s about their financial track record. A casual acquaintance, no matter how trustworthy, might not have the optimal credit profile to help you.
- Excellent Payment History: The primary cardholder should have a spotless record of paying their bills on time, every time. Late payments on their account will negatively affect your score.
- Low Credit Utilization: They should ideally keep their credit card balances below 30% of their total credit limit, or even lower (10% is ideal), to demonstrate responsible credit use.
- Long Credit History: An older account with a lengthy history of good standing can significantly boost the average age of your accounts, which is a positive credit factor.
- High Credit Limit: A high credit limit on the primary account, combined with low utilization, helps to keep the utilization ratio low, which is beneficial.
Avoiding common pitfalls
While authorized user status can be highly beneficial, there are potential pitfalls that you must be aware of. The biggest risk is that the primary cardholder’s negative financial behavior could harm your credit score. If they start missing payments or maxing out their card, that negative activity will also appear on your credit report.
It’s crucial to have an open and honest conversation with the potential primary cardholder about their financial habits and your expectations. Establish clear ground rules, even if you don’t plan on using the card yourself. Regularly monitor your credit report to ensure that the account is being managed responsibly and that no unexpected issues arise.
Choosing the right primary cardholder is a critical step in this credit-building strategy. A well-chosen account can propel your credit score upwards, while a poorly chosen one can set you back. Due diligence and clear communication are your best allies in this process.
Maximizing your 15-point increase: strategies for success
Simply being added as an authorized user isn’t a guaranteed path to a 15-point credit score increase. While it provides a strong foundation, strategic actions on your part, combined with the primary cardholder’s responsible behavior, are necessary to maximize the benefits. In 2026, a proactive approach to credit building remains essential.
The goal is to ensure that the positive aspects of the authorized user account are fully reflected in your credit report and that you are also taking steps to build your own independent credit history. This multi-pronged approach offers the best chance for significant and sustainable credit score improvement.
Monitoring credit reports and scores
Regularly checking your credit reports from all three major bureaus (Equifax, Experian, TransUnion) is non-negotiable. This allows you to confirm that the authorized user account is being reported correctly and that the positive history is indeed appearing on your file. You can access free weekly credit reports until 2026 through annualcreditreport.com.
- Verify the authorized user account appears on your reports.
- Check for accurate payment history and credit limits.
- Dispute any errors immediately to prevent negative impacts.
- Monitor your credit score regularly using free tools or services.
Building your own credit history concurrently
While authorized user status is an excellent boost, it should ideally be a stepping stone, not your sole credit-building strategy. Lenders prefer to see that you can manage your own credit accounts responsibly. Consider opening a secured credit card or a small credit-builder loan in your name, if your credit profile allows.
Making small, consistent purchases on your own credit accounts and paying them off in full and on time each month will demonstrate your ability to handle credit independently. This diversified approach to credit building will strengthen your overall credit profile, making you a more attractive borrower in the long run.
By combining the positive influence of an authorized user account with your own efforts to establish and manage credit, you create a robust credit-building strategy. This synergistic approach is key to not only achieving that 15-point increase but also sustaining a healthy credit score well into the future, opening doors to better financial opportunities.
Potential risks and how to mitigate them
While authorized user status offers a compelling pathway to credit improvement, it’s not without its risks. These risks primarily stem from the actions of the primary cardholder, as their financial behavior directly reflects on your credit report. Understanding these potential pitfalls and knowing how to mitigate them is crucial for a successful credit-building journey in 2026.
The most significant concern is that negative activity on the primary account, such as late payments or high credit utilization, could negatively impact your credit score. This is why trust and open communication with the primary cardholder are paramount, along with diligent monitoring of your own credit reports.
Negative impact from primary cardholder’s actions
If the primary cardholder begins to mismanage their account, your credit score could suffer. This includes scenarios where they:
- Miss Payments: A single late payment can drop a credit score significantly, and this could be reflected on your report.
- Max Out the Card: High credit utilization, even if payments are made on time, signals higher risk and can lower your score.
- Default on the Account: In extreme cases, if the primary cardholder defaults, this severe negative mark could appear on your credit.
Because you are not legally responsible for the debt, you cannot directly intervene or make payments to prevent these issues. Your recourse is limited to requesting removal as an authorized user.
Strategies for risk mitigation
Mitigating these risks requires a proactive and communicative approach. Before being added, have a frank discussion with the primary cardholder about their financial habits and your expectations. Ensure they understand the potential impact on your credit should their account fall into disarray.
Regularly check your credit reports from all three bureaus. This allows you to identify any negative reporting from the authorized user account promptly. If you notice any adverse activity, you can immediately request to be removed as an authorized user. Most credit card issuers will remove you upon request from either you or the primary cardholder. Once removed, the account may eventually drop off your credit report, or its impact may diminish over time, depending on the credit bureau’s policies.
Additionally, consider the length of time you need to be an authorized user. Once your credit score has improved sufficiently and you’ve established some independent credit, you might choose to be removed to eliminate future risk. This strategic exit ensures you reap the benefits without prolonged exposure to potential downsides.
Beyond the 15 points: long-term credit health
While a 15-point credit score increase in six months is a fantastic immediate goal, the true power of leveraging authorized user status lies in its contribution to your long-term credit health. In 2026, building a robust and sustainable credit profile is more important than ever for accessing favorable loan terms, housing, and even certain employment opportunities.
Authorized user status is a valuable tool, but it’s part of a broader strategy for financial wellness. The habits you cultivate and the understanding you gain about credit during this period will serve you well for years to come, far beyond the initial score bump.
Establishing independent credit
The ultimate goal after benefiting from authorized user status should be to establish and maintain your own strong credit history. This involves opening and responsibly managing your own credit accounts. Start with a secured credit card or a small personal loan if necessary, then gradually move to unsecured credit as your score improves.
Demonstrating your ability to manage various types of credit (credit mix) and maintaining a long average age of accounts are crucial for a truly excellent credit score. The authorized user account helps kickstart this, but your independent efforts will solidify your credit standing.
Sustaining positive credit habits
Long-term credit health is built on consistent positive habits. These include:
- Paying all bills on time: This is the single most important factor. Set up automatic payments to avoid missing due dates.
- Keeping credit utilization low: Aim to keep your balances below 30% of your credit limits across all accounts.
- Regularly reviewing credit reports: Check for errors and fraudulent activity at least once a year.
- Avoiding unnecessary new credit applications: Each application can result in a hard inquiry, temporarily lowering your score.
These habits, once ingrained, will ensure that your credit score continues to grow and remain healthy, providing you with financial flexibility and opportunities. The authorized user experience is a lesson in the importance of responsible credit management, which you can then apply to your own financial journey.
By viewing authorized user status as a launchpad rather than a destination, you can effectively leverage it for immediate gains while setting yourself up for enduring financial success. This holistic approach to credit building is what truly defines long-term credit health in 2026 and beyond.
Navigating the future of credit: 2026 outlook
The credit landscape is dynamic, constantly evolving with new technologies, regulatory changes, and economic shifts. As we look towards 2026, understanding these trends is vital for anyone leveraging authorized user status or engaging in any form of credit building. The fundamental principles remain, but their application and impact can be influenced by external factors.
While the core benefits of authorized user status are expected to persist, keeping an eye on how credit bureaus refine their scoring models and how lenders assess risk will ensure your strategies remain effective. Adaptability is key in navigating the future of personal finance.
Emerging trends in credit scoring
In 2026, we may see further integration of alternative data into credit scoring models. While traditional factors like payment history and credit utilization will remain dominant, data points such as utility payments, rent payments, and banking transaction history might gain more prominence. This could offer new avenues for individuals with thin credit files to establish credibility.
- Increased use of AI and machine learning in credit assessments.
- Potential for more personalized credit offers based on wider data sets.
- Continued focus on financial inclusion for underserved populations.
- Emphasis on predictive analytics for future payment behavior.
For authorized users, this means that while the traditional benefits are strong, having a comprehensive financial footprint that includes positive alternative data could further enhance their credit profile. It reinforces the idea that overall financial responsibility is increasingly valued.
Regulatory considerations and consumer protections
Regulatory bodies continually review and update consumer protection laws related to credit. In 2026, there might be further refinements to how authorized user accounts are reported or how consumers can dispute inaccuracies. Staying informed about these changes is crucial for protecting your credit health.
The emphasis on transparency and fairness in credit reporting is likely to continue. This means consumers should have clear avenues to understand their credit reports, dispute errors, and understand the factors influencing their scores. For authorized users, this translates to continued access to their credit reports and the ability to address any discrepancies related to the primary account.
The future of credit in 2026 promises both continuity and evolution. Authorized user status will likely remain a powerful tool for credit building, but its effectiveness will be amplified by staying informed about broader credit trends and maintaining a holistic approach to financial health. Proactive engagement with your credit profile will always be your strongest asset.
| Key Point | Brief Description |
|---|---|
| Authorized User Benefit | Leverages primary cardholder’s positive credit history to boost your score. |
| 15-Point Increase Goal | Achievable within 6 months with responsible primary account management. |
| Primary Cardholder Selection | Crucial to choose someone with excellent payment history and low utilization. |
| Risk Mitigation | Monitor credit reports and communicate openly with the primary cardholder. |
Frequently asked questions about authorized user status
How quickly can I see a credit score increase as an authorized user?▼You can typically start seeing changes within one to two billing cycles after being added to an account. Significant increases, like 15 points, usually manifest over three to six months as positive payment history accumulates on your credit report, demonstrating consistent responsible credit behavior.
What are the risks of being an authorized user?▼The main risk is that the primary cardholder’s negative actions, such as late payments or high credit utilization, will negatively impact your credit score. You have no legal responsibility for the debt, but their mismanagement can still harm your credit report, making careful selection essential.
Can I be removed as an authorized user if needed?▼Yes, either you or the primary cardholder can request your removal from the account at any time. Once removed, the account may eventually stop appearing on your credit report or its impact will diminish, protecting you from future negative activity.
Does authorized user status count towards my own credit history length?▼Yes, for FICO scores, the account’s age can contribute to the length of your credit history, which is a positive factor. This is particularly beneficial for individuals with a thin credit file, as it adds an established account to their report, improving their average account age.
Is it better to get a secured credit card or become an authorized user?▼Both have benefits. Authorized user status offers a quick boost without requiring a deposit. A secured card builds independent credit directly. Ideally, use authorized user status for an initial boost, then open a secured card to establish your own strong credit history concurrently for optimal results.
Conclusion
Leveraging authorized user status in 2026: leveraging it for a 15-point credit score increase in 6 months stands as a potent, yet nuanced, strategy for credit enhancement. While it offers a valuable shortcut to improving your credit profile, particularly for those with limited credit history, its success hinges on careful selection of the primary cardholder and diligent monitoring. This approach, when combined with your own proactive credit-building efforts, forms a robust foundation for long-term financial health. By understanding the mechanics, mitigating risks, and staying informed about evolving credit trends, you can effectively harness this tool not just for an immediate score boost, but for sustainable financial well-being in the years to come.