Global Semiconductor Shortage: 2026 Tech Production Impact & Updates
Advertisements
The global semiconductor shortage is projected to significantly affect 2026 tech production, with ongoing supply chain reconfigurations and geopolitical factors continuing to shape the availability and cost of essential electronic components.
The persistent challenge of the global semiconductor shortage: updates and impact on 2026 tech production (recent updates) continues to cast a long shadow over the technology landscape. As we navigate through the mid-2020s, understanding the intricate dynamics of chip supply and demand becomes crucial for businesses and consumers alike. How will this shortage evolve, and what does it mean for the devices and innovations we anticipate in 2026?
Understanding the Roots of the Semiconductor Shortage
The origins of the global semiconductor shortage are multifaceted, stemming from a confluence of unforeseen events and long-standing industry trends. While the COVID-19 pandemic acted as a significant catalyst, exacerbating existing vulnerabilities, the foundational issues run deeper into the very structure of the semiconductor ecosystem. Analyzing these roots is essential to grasp the current situation and project its future trajectory.
Initially, the pandemic-driven lockdowns led to an unexpected surge in demand for personal electronics as work-from-home and remote learning became the norm. This sudden spike caught manufacturers off guard, as many had scaled back production in anticipation of an economic slowdown. Simultaneously, disruptions in logistics and labor further complicated the supply chain, creating a perfect storm for chip scarcity.
The Role of Just-in-Time Manufacturing
For decades, the semiconductor industry, like many others, adopted just-in-time manufacturing principles. This strategy minimizes inventory holding costs by producing goods only as they are needed. While efficient in stable times, it proved brittle when faced with unpredictable demand swings and supply disruptions.
- Reduced inventory buffers meant no immediate stock to meet sudden demand increases.
- Reliance on lean supply chains made them vulnerable to single points of failure.
- Limited flexibility to quickly ramp up production without significant lead times.
Geopolitical Tensions and Trade Policies
Beyond the pandemic, geopolitical tensions, particularly between the United States and China, have played a considerable role. Tariffs, export controls, and restrictions on technology transfers have forced companies to re-evaluate their supply chains, often leading to costly and time-consuming diversifications. This fragmentation, while aiming for security, can sometimes inadvertently reduce overall efficiency and increase lead times for certain components.
The desire for national self-sufficiency in chip manufacturing, driven by strategic concerns, has also influenced investment decisions and policy interventions, further shaping the landscape of semiconductor production and availability.
Current State of the Semiconductor Market: Recent Updates
As of late 2024 and early 2025, the semiconductor market remains in a state of flux, though some sectors are showing signs of stabilization while others continue to face significant challenges. Recent updates indicate a nuanced recovery, far from a uniform return to pre-shortage conditions. The market’s resilience is being tested by persistent demand for advanced chips, especially those powering AI, data centers, and automotive innovation.
While certain legacy chips, particularly those used in older automotive systems or simpler consumer electronics, have seen some easing of supply constraints, leading-edge chips remain highly sought after. This disparity highlights the increasing technological divide within the semiconductor landscape, where not all chips are created equal in terms of demand or manufacturing complexity.
Regional Manufacturing Expansion Efforts
Governments worldwide are investing heavily in domestic chip manufacturing capabilities to reduce reliance on a few key regions. Initiatives like the U.S. CHIPS and Science Act and similar efforts in Europe and Japan are spurring the construction of new fabs and R&D facilities. These long-term investments aim to bolster supply chain resilience but will take several years to come online and meaningfully impact global supply.
- Significant government subsidies are attracting major chipmakers to build new plants.
- Focus on diversifying manufacturing geographically to mitigate future disruptions.
- Challenges include skilled labor shortages and high initial investment costs.
Inventory Adjustments and Demand Shifts
Some industries, particularly consumer electronics, experienced a period of inventory correction in late 2023 and early 2024 as companies adjusted to slower consumer spending post-pandemic boom. This temporarily reduced demand for certain chip types, offering a brief respite. However, sectors like automotive and industrial applications continue to see robust demand, keeping pressure on their specific chip categories.
The shift towards higher-performance computing and specialized AI chips means that even if overall chip production increases, the specific types of chips most in demand are still under considerable strain, requiring advanced manufacturing processes that are capacity-constrained.
Projected Impact on 2026 Tech Production
Looking ahead to 2026, the global semiconductor shortage is expected to have a continued, albeit evolving, impact on tech production. While the most acute bottlenecks might ease for some standard components, the pressure on advanced and specialized chips will likely persist, influencing product availability, innovation cycles, and pricing across various industries. Companies are already planning their 2026 strategies with this constraint in mind.
The tech landscape in 2026 will be characterized by a dual reality: more readily available foundational components for everyday devices, but potentially continued scarcity and higher costs for cutting-edge technologies. This will necessitate strategic choices in product design, market focus, and supply chain management for manufacturers.
Automotive Industry Challenges
The automotive sector, a significant consumer of semiconductors, will likely continue to face challenges. Modern vehicles are increasingly software-defined and rely on a vast array of chips for everything from engine management to advanced driver-assistance systems (ADAS) and infotainment. The transition to electric vehicles (EVs) further amplifies this demand.
Even with new fabs coming online, the specialized nature of automotive-grade chips, which require higher durability and reliability standards, means their production ramp-up can be slower. This could lead to extended lead times for new vehicle models and specific features.
Consumer Electronics and Device Availability
For consumer electronics, 2026 might see a more stable supply for mainstream devices like smartphones and laptops, but high-end gaming consoles, virtual reality headsets, and other devices requiring the latest GPUs and CPUs could still experience intermittent supply issues. Manufacturers will prioritize their most profitable lines, potentially leaving niche products with longer wait times.
- Improved availability for standard consumer devices.
- Continued potential for scarcity in high-performance or niche gadgets.
- Pricing pressures may remain due to increased manufacturing costs.
Strategic Responses from Tech Companies
In response to the prolonged semiconductor shortage, tech companies are implementing a range of strategic measures to mitigate risks and secure their supply chains. These strategies reflect a fundamental shift from just-in-time efficiency to a more resilient, diversified approach, prioritizing supply security over minimal inventory costs. The lessons learned from the past few years are driving significant long-term investments and operational changes.
Many companies are moving beyond simple supplier diversification to more deeply integrate with their chip partners, sometimes even co-investing in manufacturing capacity. This closer collaboration aims to provide greater visibility into production schedules and ensure preferential allocation during periods of high demand.
Long-Term Supplier Agreements and Partnerships
A key strategy involves forging long-term agreements with semiconductor manufacturers (foundries). These multi-year contracts provide foundries with guaranteed demand, encouraging them to allocate production capacity to specific customers. Some tech giants are even investing directly in chip foundries or forming joint ventures to secure a dedicated supply.
- Securing guaranteed capacity through multi-year contracts.
- Direct investments in foundries to influence production.
- Collaborative R&D efforts to co-design chips and optimize manufacturing.
Reshoring and Nearshoring Initiatives
To reduce geopolitical risks and transportation costs, many companies are exploring reshoring (bringing manufacturing back to their home country) or nearshoring (moving it to neighboring countries). While this is a costly and complex endeavor, the long-term benefits of a more resilient and geographically diversified supply chain are becoming increasingly apparent.
This trend is supported by government incentives and a renewed focus on national security surrounding critical technologies. However, building new fabs takes years and requires a highly skilled workforce, presenting its own set of challenges.
Geopolitical Factors and Supply Chain Resilience
Geopolitical factors are inextricably linked to the future of the semiconductor supply chain and its resilience against future shocks. The concentration of advanced chip manufacturing in a few key regions, particularly Taiwan, makes the global tech industry vulnerable to regional instabilities and international disputes. Nations are increasingly viewing semiconductor capabilities as a matter of national security and economic competitiveness.
The ongoing competition between major global powers, particularly concerning technological supremacy, continues to shape trade policies, investment flows, and the overall landscape of chip production. This dynamic environment necessitates a constant re-evaluation of supply chain strategies by all stakeholders.
Governmental Interventions and Subsidies
Governments worldwide are actively intervening to bolster domestic semiconductor production through substantial subsidies, tax incentives, and regulatory frameworks. The U.S. CHIPS and Science Act, the European Chips Act, and similar initiatives in Asia aim to attract significant investment in new fabrication plants (fabs) and R&D facilities within their borders.
These interventions are designed not only to secure future supply but also to create high-tech jobs and foster innovation locally. However, the effectiveness of these policies will depend on sustained political will, efficient execution, and the ability to cultivate a skilled workforce.
Diversification and Redundancy
Companies are no longer solely focused on cost efficiency but are increasingly prioritizing supply chain resilience through diversification and redundancy. This involves sourcing chips from multiple regions and suppliers, even if it means slightly higher costs. The goal is to build a robust network that can withstand disruptions in any single point.
Furthermore, some firms are exploring the possibility of maintaining buffer inventories for critical components, moving away from the strict just-in-time model for essential parts. This strategic shift acknowledges that the cost of a production halt far outweighs the cost of holding extra stock.
Technological Advancements and Future Outlook
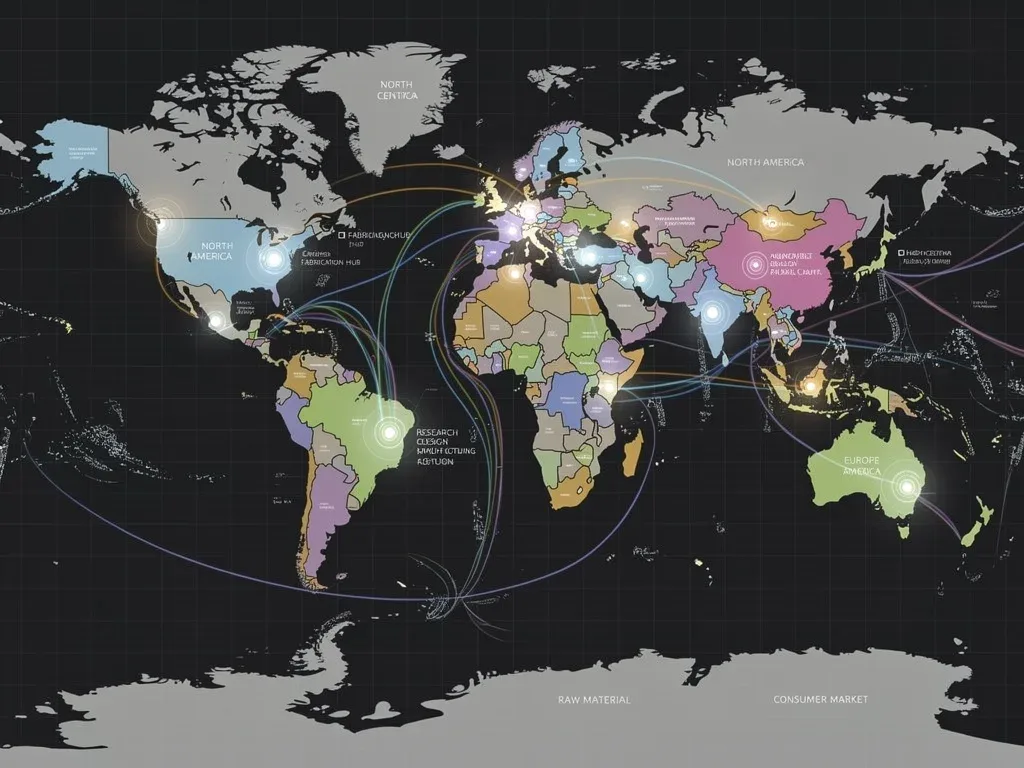
Technological advancements in semiconductor manufacturing and design are playing a crucial role in shaping the future outlook of the industry, offering both solutions to current shortages and new challenges. Innovations are not just about making chips smaller and faster but also about improving manufacturing efficiency, exploring alternative materials, and developing new chip architectures that can optimize performance and reduce reliance on single-source components.
The drive towards greater automation and the application of artificial intelligence in chip design and fabrication processes promise to enhance productivity and reduce human error, contributing to a more stable and efficient supply chain in the long run. These advancements are critical for meeting the ever-growing demand for computing power.
New Manufacturing Techniques
Research and development in manufacturing techniques, such as advanced packaging and new lithography processes, are continuously pushing the boundaries of what’s possible. These innovations can help increase the yield of existing fabs and enable the production of more complex chips, potentially alleviating some pressure on current capacity. Extreme Ultraviolet (EUV) lithography, for instance, is central to producing the most advanced chips.
- Development of more efficient and precise lithography technologies.
- Advancements in 3D stacking and heterogeneous integration for higher performance.
- Exploration of alternative materials to silicon for specialized applications.
Rise of Chiplet Architecture
The adoption of chiplet architecture is another significant technological trend. Instead of manufacturing a single, large monolithic chip, chiplets allow for the integration of multiple smaller, specialized chips (chiplets) onto a single package. This modular approach offers several advantages, including improved yield, greater design flexibility, and potentially reduced manufacturing costs.
Chiplets can also help mitigate the impact of shortages by allowing manufacturers to mix and match components from different suppliers or production lines, reducing dependence on a single, perfectly functioning large die. This modularity enhances overall supply chain flexibility and resilience.
Implications for Businesses and Consumers by 2026
By 2026, the ongoing semiconductor situation will have distinct implications for both businesses and consumers, shaping market dynamics, product availability, and pricing. Businesses will need to continue adapting their strategies, while consumers may experience shifts in product offerings and potentially higher costs for certain advanced technologies. The era of cheap, readily available chips for all applications might be behind us, at least for the foreseeable future.
For businesses, resilience and adaptability will remain paramount. Those that have successfully diversified their supply chains and invested in strategic partnerships will be better positioned to navigate the evolving landscape. Consumers, on the other hand, might need to adjust their expectations regarding product launches and pricing, especially for devices at the bleeding edge of innovation.
Business Strategies and Investment
Companies will continue to prioritize investments in supply chain visibility tools, AI-powered demand forecasting, and inventory management systems. The focus will shift from purely cost-driven decisions to a balance between cost, resilience, and geopolitical risk. This may include carrying higher buffer stocks for critical components and exploring regional manufacturing hubs, even if it entails higher operational expenses.
Innovation will also be influenced, with companies potentially designing products that can accommodate a wider range of chip suppliers or using more modular architectures to reduce dependency on specific, hard-to-find components.
Consumer Experience and Product Access
Consumers in 2026 can expect a more stable supply of mainstream tech products, but premium devices incorporating the latest, most advanced chips might still face occasional delays or come with higher price tags. The demand for AI-driven features in personal devices, for example, will likely keep pressure on the supply of specialized AI accelerators.
- More consistent availability for everyday electronics.
- Potential for price increases on cutting-edge tech due to higher component costs.
- Increased awareness among consumers regarding supply chain challenges.
| Key Aspect | 2026 Outlook |
|---|---|
| Overall Supply | Easing for some legacy chips, persistent tightness for advanced nodes. |
| Automotive Sector | Continued challenges due to specialized chip requirements and EV demand. |
| Geopolitical Influence | Significant driver of regional manufacturing and supply chain diversification. |
| Consumer Electronics | Improved stability for mainstream devices, potential for high-end scarcity. |
Frequently Asked Questions About the Semiconductor Shortage
Will the semiconductor shortage be over by 2026?▼While some easing for certain chip types is expected, a complete end to the semiconductor shortage across all sectors by 2026 is unlikely. Advanced chips, crucial for AI and high-performance computing, will likely remain constrained due to high demand and complex manufacturing processes, requiring ongoing strategic management by industries.
What industries are most affected by the semiconductor shortage in 2026?▼The automotive industry is expected to remain significantly impacted due to increasing chip content in modern vehicles and EVs. Additionally, sectors relying on cutting-edge processors for AI, data centers, and advanced consumer electronics will likely experience continued supply pressures, influencing product development and market availability.
How are governments addressing the semiconductor shortage?▼Governments are responding with substantial investments and incentives, such as the U.S. CHIPS Act and the European Chips Act. These initiatives aim to boost domestic manufacturing capabilities, promote R&D, and diversify global supply chains to reduce reliance on specific regions and enhance national security in critical technology sectors.
What role do technological advancements play in resolving the shortage?▼Technological advancements, including new manufacturing techniques like EUV lithography, advanced packaging, and chiplet architectures, are vital. These innovations enhance production efficiency, allow for more modular designs, and can potentially increase chip yields, helping to meet growing demand and improve overall supply chain resilience in the long term.
How will the shortage impact consumer prices and product availability?▼Consumers can anticipate more stable availability for many standard tech products. However, devices requiring the latest, most advanced chips may still face intermittent supply delays and potentially higher prices due to increased manufacturing costs and persistent demand. This will influence purchasing decisions and product upgrade cycles.
Conclusion
The journey through the global semiconductor shortage: updates and impact on 2026 tech production (recent updates) reveals a landscape of complex challenges intertwined with strategic adaptations. While the most critical bottlenecks might gradually ease for some sectors, the overarching narrative for 2026 suggests a continued state of careful management, innovation, and geopolitical interplay. Industries are recalibrating their supply chains, investing in diversified manufacturing, and fostering closer partnerships to build resilience against future disruptions. Consumers should anticipate a market that, while more stable for everyday devices, may still present unique considerations for access to cutting-edge technologies. The semiconductor industry is not just recovering; it is fundamentally transforming, setting the stage for a more robust, albeit more complex, future for global tech production.