Federal Reserve’s March 2026 Statement: Impact on Rates
Advertisements
The Federal Reserve’s March 2026 statement significantly influences interest rates, shaping borrowing costs and investment returns across the U.S. economy, with recent updates indicating potential shifts in monetary policy.
The financial world holds its breath with every pronouncement from the nation’s central bank. The Federal Reserve’s March 2026 statement: analyzing the impact on interest rates (recent updates) is no exception, carrying profound implications for every facet of the U.S. economy, from mortgage payments to investment strategies. Understanding these nuanced decisions is crucial for businesses and individuals alike.
Understanding the Federal Reserve’s Mandate
The Federal Reserve, often simply called ‘the Fed,’ operates with a dual mandate from Congress: to achieve maximum employment and stable prices. These two objectives guide all monetary policy decisions, including those made in March 2026. The Fed’s actions are not arbitrary; they are the result of extensive economic analysis, forecasting, and a deep understanding of market dynamics. Its role as the central bank is critical in maintaining the health and stability of the U.S. financial system.
To fulfill its mandate, the Federal Open Market Committee (FOMC) meets eight times a year, or more if necessary, to assess economic conditions and determine the appropriate course of action for monetary policy. These meetings culminate in statements that outline their decisions on the federal funds rate, quantitative easing or tightening, and their economic outlook. The March 2026 meeting was particularly anticipated due to ongoing global economic shifts and domestic inflation pressures.
The Dual Mandate Explained
The dual mandate is the bedrock of the Fed’s policy-making. Maximum employment means striving for an unemployment rate that is consistent with a stable inflation rate, essentially ensuring as many people as possible who want to work can find jobs. Stable prices, on the other hand, means keeping inflation at a low and predictable level, typically around 2% over the long run, to preserve the purchasing power of the dollar and prevent economic uncertainty.
- Maximum Employment: Aiming for full utilization of labor resources without triggering excessive inflation.
- Stable Prices: Controlling inflation to maintain the value of the currency and foster economic predictability.
- Balancing Act: Often, there’s a delicate balance between these two goals, requiring careful consideration of trade-offs.
The Fed’s decisions are rarely simple, as economic indicators can often pull in different directions. For instance, strong employment growth might signal an overheating economy, potentially leading to higher inflation, thus requiring the Fed to consider raising interest rates. Conversely, a slowdown in economic activity might necessitate lower rates to stimulate growth and employment, even if inflation is slightly above target.
In essence, the Federal Reserve’s mandate ensures that its decisions are grounded in a commitment to broad economic well-being, rather than short-term political or market pressures. This institutional independence is vital for its credibility and effectiveness in steering the economy.
Key Takeaways from the March 2026 Statement
The March 2026 statement from the Federal Reserve was keenly observed by economists, investors, and the general public. It provided crucial insights into the Fed’s current assessment of the economy and its forward guidance on monetary policy. The statement’s language, often meticulously chosen, offered signals about the potential trajectory of interest rates and the Fed’s approach to managing inflation and employment.
One of the primary focuses of the statement was the federal funds rate target. Any adjustment, or even a strong indication of future adjustments, can ripple through financial markets. The committee’s assessment of economic data, including inflation figures, employment reports, and GDP growth, formed the basis of their decisions. Markets often react swiftly to these announcements, adjusting asset prices and borrowing costs.
Inflationary Pressures and Economic Growth
The Fed’s statement highlighted persistent inflationary pressures, albeit with some signs of moderation in certain sectors. While the overall inflation rate remained a concern, the committee noted improvements in supply chain dynamics and a gradual easing of commodity prices. Economic growth, though resilient, showed signs of slowing from its previous robust pace, suggesting that prior monetary tightening measures were having their intended effect.
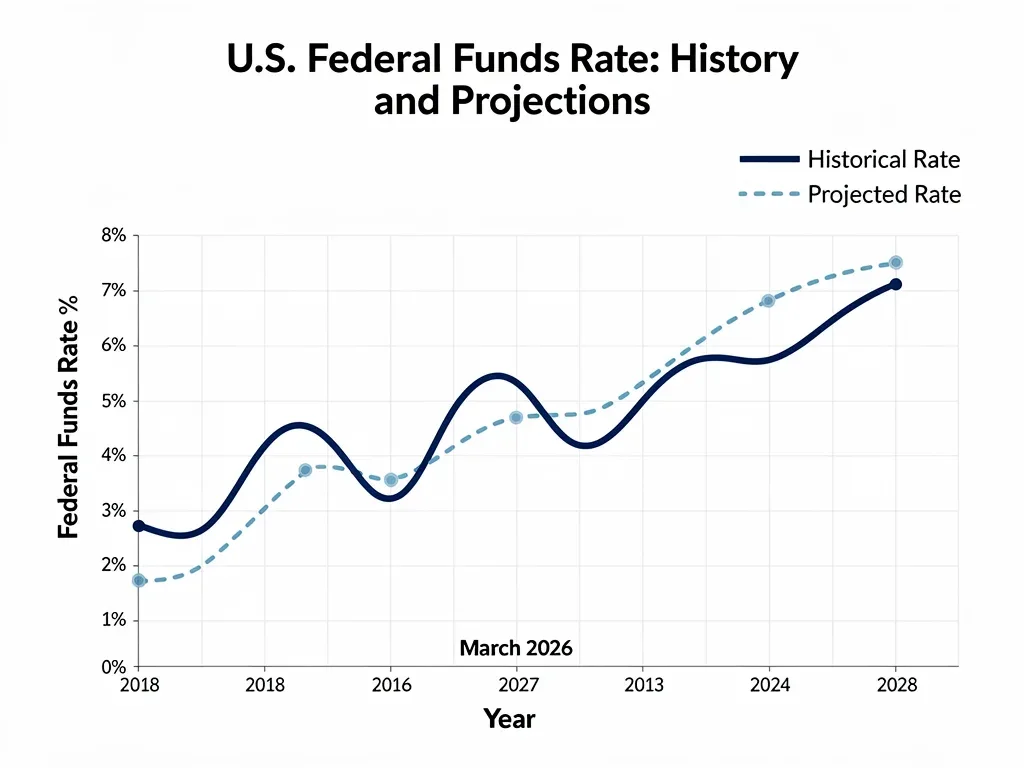

The labor market continued to be a point of strength, with low unemployment rates and steady wage growth. However, the statement also acknowledged some cooling in job openings, indicating a gradual rebalancing between labor supply and demand. This nuanced view of the economy allowed the Fed to communicate a cautious but data-dependent approach to future policy decisions.
Forward Guidance and Market Expectations
Forward guidance, the Fed’s communication about the future path of monetary policy, is a powerful tool. The March 2026 statement reiterated the Fed’s commitment to bringing inflation back to its 2% target, emphasizing that future decisions would remain data-dependent. This implies flexibility, allowing the Fed to adapt to evolving economic conditions rather than committing to a rigid pre-set course.
- Data Dependency: Future rate decisions will be contingent on incoming economic data.
- Inflation Target: Continued focus on achieving the long-term 2% inflation goal.
- Cautious Optimism: Acknowledgment of economic resilience alongside ongoing risks.
Markets interpreted this guidance as a signal that while the tightening cycle might be nearing its end, the Fed was not yet ready to commit to rate cuts. The emphasis on data dependency means that upcoming inflation reports, employment figures, and global economic developments will heavily influence the Fed’s next moves. This creates a degree of uncertainty but also allows for a more responsive monetary policy.
Impact on Interest Rates: Short-Term vs. Long-Term
The Federal Reserve’s March 2026 statement directly influenced short-term interest rates and indirectly affected long-term rates. The federal funds rate, which the Fed targets, is a short-term rate that banks charge each other for overnight lending. Changes to this rate cascade through the financial system, impacting a wide array of borrowing costs for consumers and businesses.
When the Fed adjusts the federal funds rate, it influences prime rates, credit card interest rates, adjustable-rate mortgages, and short-term business loans. A hike in the federal funds rate typically leads to an increase in these short-term rates, making borrowing more expensive. Conversely, a reduction tends to lower these costs, stimulating economic activity. The March 2026 statement provided clarity on the Fed’s current stance, offering a benchmark for these short-term borrowing costs.
Direct Effects on Short-Term Rates
The most immediate and direct impact of the Fed’s decisions is on the federal funds rate. If the Fed decided to raise this rate, banks would face higher costs for borrowing reserves, which they would then pass on to their customers. This is why changes to the federal funds rate are so closely watched. The March 2026 statement indicated the Fed’s continued vigilance in managing this key rate to steer the economy.
- Credit Card Rates: Often tied to the prime rate, which moves in lockstep with the federal funds rate.
- Adjustable-Rate Mortgages (ARMs): Interest rates can fluctuate based on the federal funds rate.
- Short-Term Business Loans: Costs for businesses borrowing for operational needs are directly affected.
For consumers, this means that the cost of carrying credit card debt or financing short-term loans can change relatively quickly after a Fed announcement. Businesses, particularly small and medium-sized enterprises (SMEs), also feel the immediate impact on their working capital and investment decisions.
Indirect Influence on Long-Term Rates
Long-term interest rates, such as those on 10-year Treasury bonds or fixed-rate mortgages, are influenced by a broader set of factors beyond just the federal funds rate. These include inflation expectations, economic growth outlooks, and global capital flows. However, the Fed’s forward guidance and its overall monetary policy stance play a significant role in shaping these expectations.
The March 2026 statement, by providing clarity on the Fed’s commitment to inflation control and its economic outlook, helped to anchor long-term inflation expectations. If markets believe the Fed is credible in its fight against inflation, long-term bond yields may remain more stable. Conversely, if there’s skepticism, long-term rates could rise as investors demand higher compensation for future inflation risk. Therefore, while not directly controlled, long-term rates are heavily influenced by the Fed’s communication and perceived effectiveness.
Sector-Specific Implications of Rate Changes
Interest rate changes initiated by the Federal Reserve do not affect all sectors of the economy equally. Some industries are inherently more sensitive to borrowing costs and consumer spending patterns, making them particularly vulnerable or resilient to shifts in monetary policy. The March 2026 statement’s implications for interest rates will undoubtedly create winners and losers across various economic sectors.
For instance, sectors that rely heavily on consumer financing, such as housing and automotive, tend to be highly sensitive to interest rate fluctuations. Higher rates can deter potential buyers by increasing monthly payments, leading to a slowdown in sales. Conversely, industries that benefit from higher interest income, such as banking, might see an improvement in their profit margins. Analyzing these sector-specific implications is crucial for investors and business leaders.
Housing and Real Estate
The housing market is arguably one of the most sensitive sectors to interest rate changes. Mortgage rates, particularly for fixed-rate loans, are closely tied to long-term bond yields, which are influenced by the Fed’s policy outlook. A higher interest rate environment makes homeownership more expensive, potentially cooling demand and leading to price adjustments. The March 2026 statement’s stance on rates will therefore have a direct bearing on affordability and market activity.
- Mortgage Rates: Direct impact on monthly payments for new homeowners and refinancers.
- Affordability: Higher rates reduce purchasing power, potentially slowing sales.
- Construction Sector: Developers may face higher borrowing costs for projects, impacting new housing supply.
Existing homeowners with adjustable-rate mortgages may also see their monthly payments increase, adding financial strain. The real estate sector, including ancillary businesses like home improvement and furniture sales, could experience a ripple effect from these changes. The Fed’s commitment to tackling inflation, even at the cost of higher rates, signals a challenging period for housing.
Financial Services and Banking
Conversely, the financial services sector, especially banks, often benefits from a rising interest rate environment. Banks earn revenue from the spread between the interest they pay on deposits and the interest they charge on loans. When the Fed raises rates, this spread can widen, leading to increased net interest income. The March 2026 statement could therefore be seen as a positive for bank profitability, assuming loan demand remains robust.

However, higher rates can also lead to increased loan defaults if borrowers struggle to meet higher payment obligations, particularly in sectors sensitive to economic downturns. Banks must carefully manage their loan portfolios and risk exposure in such an environment. The statement provided a clearer picture for financial institutions to adjust their lending strategies and asset-liability management.
Global Economic Repercussions
The Federal Reserve’s monetary policy decisions, particularly those impacting interest rates, extend far beyond the borders of the United States. As the world’s largest economy and holder of the primary reserve currency, the U.S. Fed’s actions have significant global economic repercussions. The March 2026 statement, therefore, was not only analyzed domestically but also scrutinized by central banks and financial institutions worldwide.
A change in U.S. interest rates can influence capital flows, exchange rates, and monetary policy decisions in other countries. For emerging markets, a stronger U.S. dollar, often a consequence of higher U.S. rates, can make dollar-denominated debt more expensive to service and lead to capital outflows. This can create financial instability and necessitate policy responses from their respective central banks.
Impact on Exchange Rates and Capital Flows
Higher U.S. interest rates tend to strengthen the U.S. dollar relative to other currencies. This is because higher returns on dollar-denominated assets attract foreign investment, increasing demand for the dollar. A stronger dollar makes U.S. exports more expensive for foreign buyers and imports cheaper for U.S. consumers. This can impact trade balances and corporate earnings for multinational companies.
- Currency Appreciation: U.S. dollar strengthens against other major currencies.
- Trade Balance: Can lead to larger trade deficits as imports become cheaper.
- Investment Flows: Attracts foreign capital seeking higher returns in the U.S.
For countries with significant trade ties to the U.S., these exchange rate movements can have a profound effect on their economic competitiveness. Central banks in these nations often face the difficult decision of whether to adjust their own interest rates to maintain currency stability or to allow their currencies to fluctuate, absorbing the impact on their economies.
Monetary Policy Abroad
When the Federal Reserve tightens monetary policy, central banks in other countries may feel pressure to follow suit, especially if they are battling their own inflation or trying to prevent significant capital outflows. This phenomenon, sometimes referred to as ‘monetary policy contagion,’ can lead to a synchronized global tightening cycle, potentially slowing global economic growth. The March 2026 statement likely triggered similar policy considerations in major global economies.
Conversely, if the Fed signals a more dovish stance, it could allow other central banks more room to ease their own policies if their domestic conditions warrant it. The interconnectedness of the global financial system means that the Fed’s decisions are never made in a vacuum; their effects ripple through international markets, influencing everything from commodity prices to sovereign debt yields.
Forecasting Future Federal Reserve Actions
Forecasting the future actions of the Federal Reserve is a complex endeavor, heavily reliant on interpreting economic data and the Fed’s own communications. While the March 2026 statement provided a snapshot of the Fed’s current thinking, subsequent economic reports and global events will undoubtedly shape their future decisions. Investors, businesses, and policymakers constantly seek to anticipate these moves to position themselves accordingly.
The Fed’s forward guidance, while helpful, is always conditional on the evolving economic landscape. Unexpected shocks, such as geopolitical tensions, new inflation surges, or significant shifts in labor market dynamics, can quickly alter the Fed’s trajectory. Therefore, a dynamic and flexible approach to forecasting is essential, rather than relying on static predictions.
Key Economic Indicators to Watch
Several key economic indicators will be paramount in influencing the Fed’s future decisions. Inflation data, particularly the Consumer Price Index (CPI) and the Personal Consumption Expenditures (PCE) price index, will remain central. The Fed prefers the PCE as its primary inflation gauge, and any significant deviation from the 2% target will prompt a response.
- Inflation Data: CPI and PCE reports for signs of persistent or moderating price pressures.
- Employment Reports: Unemployment rate, job growth, and wage inflation for labor market health.
- GDP Growth: Quarterly reports on economic expansion or contraction.
- Consumer Spending: Retail sales and consumer confidence indices for demand trends.
Labor market data, including the unemployment rate, non-farm payrolls, and wage growth, will also be crucial. A persistently tight labor market with strong wage growth could signal continued inflationary pressures, potentially leading to further rate hikes. Conversely, a weakening labor market might prompt the Fed to consider easing policy. GDP growth figures and consumer spending trends will provide a broader picture of economic health.
The Role of External Factors
Beyond domestic economic data, external factors can also significantly influence the Fed’s decisions. Global economic growth, geopolitical events, and commodity price movements can all have spillover effects on the U.S. economy. For example, a global slowdown could reduce demand for U.S. exports, while an oil price shock could reignite inflationary pressures.
The Fed’s policymakers are constantly monitoring these international developments, recognizing that the U.S. economy is not isolated. Their decisions are made with a comprehensive view of both domestic and global economic conditions, aiming to achieve their dual mandate while navigating a complex and interconnected world. The March 2026 statement reflected this broad perspective, acknowledging the various forces at play.
Strategies for Businesses and Individuals
In light of the Federal Reserve’s March 2026 statement and its implications for interest rates, both businesses and individuals need to adapt their financial strategies. Understanding the likely trajectory of borrowing costs and investment returns can help in making informed decisions, minimizing risks, and maximizing opportunities. Proactive planning is key in navigating an evolving economic landscape.
For businesses, this might involve re-evaluating financing structures, managing debt, and adjusting investment plans. For individuals, it could mean reviewing personal budgets, considering mortgage refinancing options, and optimizing savings and investment portfolios. The goal is to build resilience and capitalize on the prevailing economic conditions, whatever they may be.
Business Strategies in a Changing Rate Environment
Businesses should carefully assess their debt exposure, particularly if they have significant variable-rate loans. Considering options to lock in fixed rates or hedging against future rate increases might be prudent. Furthermore, managing cash flow effectively becomes even more critical when borrowing costs are higher. Companies should also evaluate their capital expenditure plans, prioritizing projects with strong returns on investment.
- Debt Management: Refinance variable-rate loans to fixed rates if advantageous.
- Cash Flow Optimization: Focus on efficient working capital management.
- Investment Prioritization: Evaluate projects based on higher hurdle rates due to increased cost of capital.
For businesses involved in international trade, monitoring exchange rate movements is essential. A stronger dollar can impact export competitiveness, while a weaker dollar might make imports more expensive. Adjusting pricing strategies and supply chain management can help mitigate these effects. The March 2026 statement serves as a reminder for businesses to remain agile and responsive to market changes.
Individual Financial Planning
Individuals should also review their personal finances in light of the Fed’s stance. For those with variable-rate debt, such as credit cards or adjustable-rate mortgages, understanding the potential for increased payments is crucial. Exploring options to consolidate debt or refinance mortgages might be beneficial, depending on individual circumstances and market rates.
On the savings front, higher interest rates can be good news for savers, as deposit accounts and money market funds may offer improved returns. However, investors should re-evaluate their portfolios, considering how different asset classes perform in a higher-rate environment. Bonds, for example, typically see their prices fall when interest rates rise, while certain equity sectors might thrive or struggle. Diversification and professional financial advice remain paramount.
| Key Point | Brief Description |
|---|---|
| Federal Funds Rate | Directly influenced by the Fed, impacting short-term borrowing costs for banks, consumers, and businesses. |
| Inflation Control | Core focus of the Fed’s dual mandate, guiding decisions to achieve stable prices. |
| Economic Data Dependency | Future policy moves are contingent on incoming inflation, employment, and growth data. |
| Global Repercussions | U.S. rate changes impact global capital flows, exchange rates, and international monetary policies. |
Frequently Asked Questions About the Fed’s March 2026 Statement
What was the primary focus of the Federal Reserve’s March 2026 statement?▼The primary focus of the Federal Reserve’s March 2026 statement was on balancing persistent inflationary pressures with signs of moderating economic growth. The Fed reiterated its commitment to achieving its 2% inflation target while closely monitoring labor market conditions and global economic developments to guide future policy decisions.
How might the March 2026 statement affect mortgage rates?▼The March 2026 statement could influence mortgage rates, especially fixed-rate mortgages, which are tied to long-term bond yields. If the Fed signals a sustained higher-for-longer interest rate environment to combat inflation, mortgage rates could remain elevated or even increase, impacting housing affordability and market activity for potential buyers.
What does ‘data-dependent’ mean for future Fed decisions?▼‘Data-dependent’ means that the Federal Reserve’s future interest rate decisions will be primarily driven by incoming economic data, including inflation reports, employment figures, and GDP growth. This approach allows the Fed flexibility to adjust its monetary policy in response to real-time economic conditions rather than adhering to a rigid, predetermined path.
How do U.S. interest rate changes impact the global economy?▼U.S. interest rate changes have significant global repercussions, particularly affecting exchange rates and capital flows. Higher U.S. rates often strengthen the dollar, making dollar-denominated debt more expensive for foreign entities and potentially leading to capital outflows from emerging markets, influencing global monetary policies and economic stability.
What should individuals do in response to the Fed’s March 2026 statement?▼Individuals should review their personal finances, especially variable-rate debts like credit cards and ARMs, as payments might increase. It’s also a good time to re-evaluate investment portfolios and savings strategies, potentially taking advantage of higher returns on deposits, and considering professional financial advice for tailored guidance.
Conclusion
The Federal Reserve’s March 2026 statement provides a critical barometer for the health and direction of the U.S. economy, with its implications for interest rates reverberating across all sectors. The Fed’s ongoing commitment to its dual mandate of maximum employment and stable prices, coupled with its data-dependent approach, underscores the dynamic nature of monetary policy. While the path ahead remains subject to evolving economic conditions and global events, understanding these pronouncements is paramount for informed decision-making. Both businesses and individuals must remain vigilant, adapting their financial strategies to navigate the changing landscape shaped by the Fed’s actions. The March 2026 statement serves as a potent reminder of the central bank’s profound influence on our financial lives and the broader economic environment.