October 2026 Manufacturing PMI: Industrial Output Updates
Advertisements
The October 2026 Manufacturing PMI report offers crucial insights into the health of the US industrial sector, reflecting production levels, new orders, employment, and inventory changes, all vital for economic forecasting and business strategy.
Understanding the October 2026 Manufacturing PMI: A Look at Industrial Output (RECENT UPDATES) is essential for businesses, investors, and policymakers alike. This critical economic indicator provides a timely snapshot of the health and direction of the manufacturing sector, offering valuable foresight into broader economic trends and potential shifts in market dynamics. Let’s delve into what this latest report reveals about the industrial landscape.
Decoding the Manufacturing PMI: What It Means
The Purchasing Managers’ Index (PMI) is a leading economic indicator derived from monthly surveys of supply chain managers across various industries. For manufacturing, it gauges the health of the sector by assessing five key areas: new orders, production levels, employment, supplier deliveries, and inventories. A PMI reading above 50 generally indicates expansion, while a reading below 50 suggests contraction. The October 2026 report, therefore, serves as a crucial benchmark for evaluating the current state and near-term outlook for industrial production.
Analyzing the individual components of the PMI offers a more granular understanding of the manufacturing environment. For instance, a rise in new orders signals increasing demand, which often precedes higher production levels. Conversely, slower supplier deliveries might indicate supply chain strain or increased demand outstripping current capacity. Each data point contributes to a comprehensive picture, helping economists and businesses anticipate future economic conditions and make informed decisions.
Key Components of the PMI
- New Orders: Reflects the demand for manufactured goods.
- Production: Indicates the actual output levels of factories.
- Employment: Shows changes in manufacturing workforce numbers.
- Supplier Deliveries: Measures the speed of input deliveries, an inverse indicator.
- Inventories: Tracks the level of raw materials and finished goods held by manufacturers.
Understanding how these components interact is vital. A strong new orders index coupled with declining inventories could suggest robust demand that manufacturers are struggling to meet, potentially leading to price increases or production bottlenecks. Conversely, high inventories and falling new orders might signal an impending slowdown. The holistic view provided by the PMI is why it remains such a closely watched economic metric.
October 2026 Highlights: Initial Findings and Surprises
The initial release of the October 2026 Manufacturing PMI brought several noteworthy points to light, offering both expected trends and some unexpected shifts. Early indications suggest a mixed landscape, with certain sectors showing robust growth while others grapple with persistent challenges. The headline figure itself provides the first signal, but the underlying data paints a more nuanced picture of the industrial output.
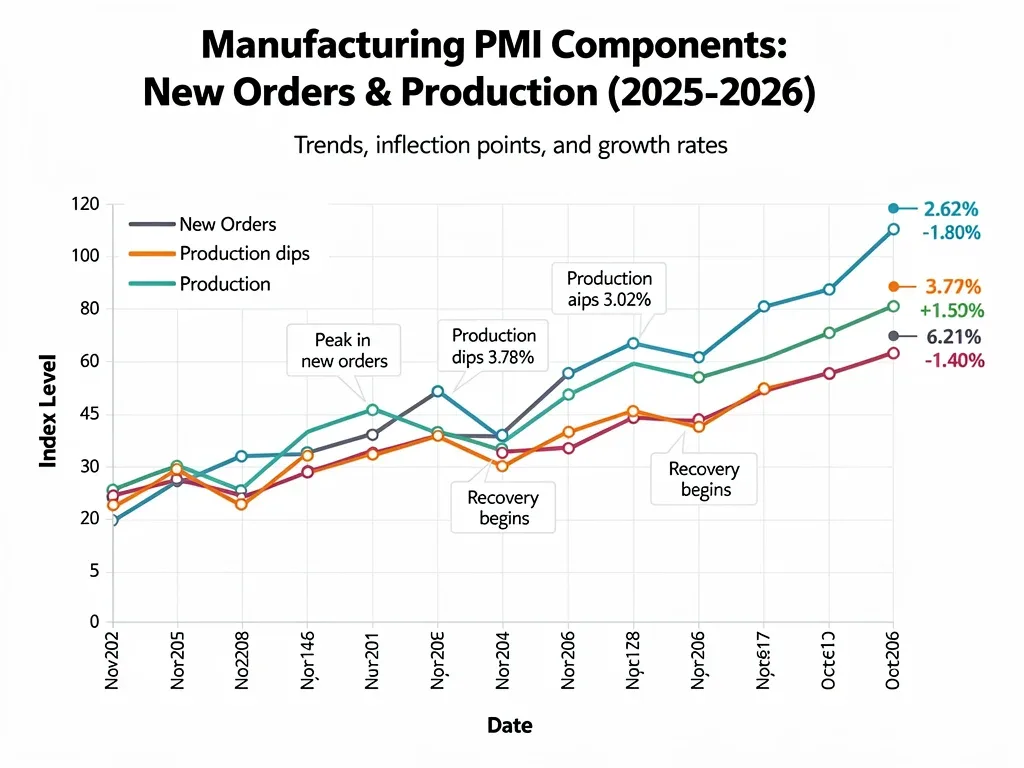
One of the most immediate observations from the report concerns the new orders component. Analysts were keen to see if the momentum from Q3 2026 carried over into the final quarter. The data revealed a slight deceleration in new order growth, though still maintaining an expansionary stance. This indicates a moderating, rather than a sharp decline, in demand, suggesting a more stable, albeit slower, pace of expansion in the coming months.
Sectoral Performance Breakdown
- Technology Manufacturing: Continued strong performance, driven by demand for advanced electronics and AI infrastructure.
- Automotive Industry: Showed signs of recovery, with improved semiconductor availability mitigating previous production constraints.
- Textile and Apparel: Faced ongoing headwinds from shifting consumer preferences and international competition.
- Food and Beverage: Remained resilient, reflecting stable consumer demand for essential goods.
Another significant highlight was the employment sub-index. While overall manufacturing employment remained positive, the rate of hiring appeared to slow, pointing to potential labor market tightness or a more cautious approach from businesses regarding workforce expansion. This could be a response to rising labor costs or anticipation of future economic uncertainties. The report also touched upon inventory levels, which saw a slight build-up, potentially indicating a proactive strategy by manufacturers to guard against future supply chain disruptions.
Supply Chain Dynamics: Persistent Challenges and Adaptations
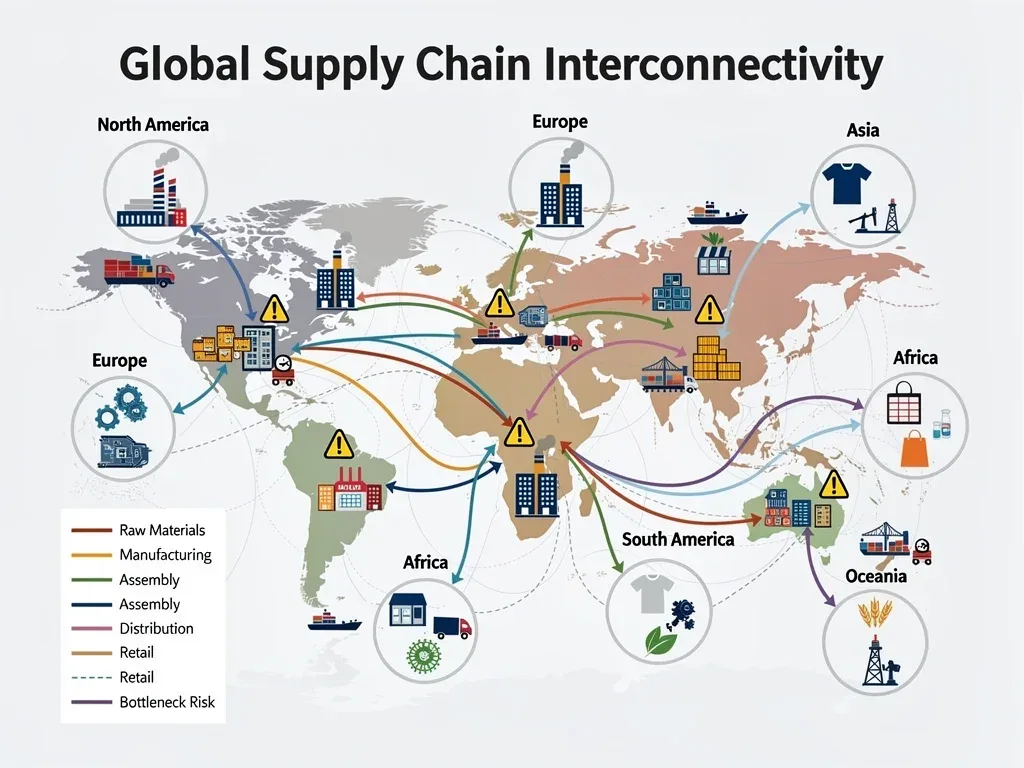
The global supply chain continues to be a central theme impacting industrial output, and the October 2026 Manufacturing PMI report underscored its persistent influence. While some of the acute disruptions seen in previous years have eased, new complexities have emerged, requiring manufacturers to continuously adapt their strategies. The report meticulously detailed the state of supplier deliveries and input prices, offering vital clues into the ongoing health of global logistics.
Supplier delivery times, often an inverse indicator, showed a marginal improvement, suggesting a slight loosening of bottlenecks compared to earlier in the year. However, they still remain elevated relative to pre-pandemic levels, indicating that the system is not yet fully optimized. This continued pressure on delivery times highlights the vulnerability of just-in-time manufacturing models and the ongoing need for diversified sourcing and robust inventory management.
Navigating Supply Chain Hurdles
- Geopolitical Shifts: Increased regionalization and friend-shoring strategies to mitigate risks.
- Logistical Innovations: Greater adoption of AI and automation in warehousing and transportation.
- Raw Material Volatility: Fluctuations in commodity prices continue to impact production costs.
- Labor Availability: Shortages in trucking and logistics personnel still pose challenges.
Furthermore, the report noted that input price inflation, while moderating from its peaks, remains a concern for many manufacturers. Energy costs, in particular, continue to exert upward pressure, forcing businesses to consider alternative energy sources or more efficient production processes. The cumulative effect of these supply chain dynamics means that manufacturers are constantly balancing cost efficiencies with resilience, a delicate act in the current economic climate. The ability to successfully navigate these complexities will largely determine the profitability and competitiveness of industrial firms in the coming period.
Economic Implications for the US Market
The findings from the October 2026 Manufacturing PMI carry significant economic implications for the broader US market. As a bellwether for economic activity, the manufacturing sector’s performance often foreshadows trends in employment, consumer spending, and investment. The report’s data points, therefore, provide crucial insights for economists, financial analysts, and policymakers in assessing the nation’s economic trajectory.
A sustained expansion in manufacturing, even if at a moderating pace, typically translates into continued job creation, albeit potentially at a slower rate, within the industrial sector and its related services. This contributes to overall employment stability and supports household incomes, which are vital for consumer confidence and spending. Conversely, any signs of contraction in the PMI would raise concerns about potential layoffs and a slowdown in economic growth.
Impact on Key Economic Indicators
- Inflation: Input price changes in manufacturing can directly influence broader inflation rates.
- GDP Growth: Manufacturing output is a significant component of the Gross Domestic Product.
- Interest Rates: Central banks closely monitor PMI for clues on economic health, influencing monetary policy decisions.
- Stock Market Performance: Industrial sector health impacts investor sentiment and corporate earnings.
Moreover, the manufacturing sector’s health has direct implications for corporate earnings. Companies operating within or supplying to the industrial base will see their revenues and profitability influenced by the trends highlighted in the PMI report. This, in turn, affects investor sentiment and stock market performance, particularly for industrial and technology-heavy indices. The report also provides valuable data for assessing inflationary pressures, especially through its sub-indices related to input and output prices, offering central banks critical information for their monetary policy decisions. The interconnectedness of these factors underscores the profound impact of manufacturing performance on the overall economic landscape.
Future Outlook: Projections and Potential Headwinds
Looking beyond October 2026, the future outlook for the manufacturing sector, as informed by the latest PMI data, presents a complex interplay of potential growth drivers and persistent headwinds. While the report offers a current snapshot, understanding its implications for the months ahead requires careful consideration of various economic and geopolitical factors. Projections suggest a continued, albeit perhaps slower, expansion, but with an increased focus on resilience and strategic adaptation.
One of the primary growth drivers is the ongoing technological advancement and digital transformation across industries. Investments in automation, artificial intelligence, and advanced robotics are expected to boost productivity and efficiency, enabling manufacturers to overcome labor shortages and enhance competitiveness. The demand for green technologies and sustainable manufacturing practices is also anticipated to fuel innovation and new market opportunities, driving specific segments of the industrial output forward.
Anticipated Challenges
- Geopolitical Instability: Ongoing conflicts and trade tensions could disrupt supply chains and commodity markets.
- Monetary Policy Tightening: Higher interest rates may dampen investment and consumer demand.
- Labor Market Dynamics: Persistent skill gaps and wage pressures could impact profitability.
- Energy Price Volatility: Unpredictable energy costs remain a significant operational risk.
However, several potential headwinds could temper this optimistic outlook. Geopolitical instability, particularly in key manufacturing regions, poses a constant threat to supply chain stability and trade flows. Furthermore, the global economic environment, characterized by varying rates of recovery and potential inflation concerns, could lead to tighter monetary policies, impacting investment and consumer spending. Manufacturers will need to remain agile, focusing on diversified supply chains, technological adoption, and robust risk management strategies to navigate these evolving challenges and capitalize on emerging opportunities in the coming year.
Strategies for Manufacturers in a Changing Landscape
In light of the insights from the October 2026 Manufacturing PMI and the broader economic outlook, manufacturers are compelled to adopt dynamic strategies to ensure resilience and sustained growth. The era of predictable, linear growth has given way to a landscape defined by rapid change and unforeseen disruptions, demanding a proactive and adaptive approach from industrial leaders. This involves not only optimizing current operations but also strategically positioning for future challenges and opportunities.
A paramount strategy involves enhancing supply chain resilience. This moves beyond simply diversifying suppliers to building truly robust, agile networks that can withstand shocks. Manufacturers are increasingly exploring regionalization or ‘near-shoring’ production, reducing reliance on single geographic hubs, and investing in advanced analytics to predict and mitigate potential disruptions before they escalate. Building stronger, more collaborative relationships with key suppliers also plays a crucial role in securing critical inputs and ensuring operational continuity.
Key Strategic Imperatives
- Digital Transformation: Investing in Industry 4.0 technologies like IoT, AI, and big data for operational efficiency.
- Workforce Development: Addressing skill gaps through training programs and attracting new talent.
- Sustainability Integration: Adopting eco-friendly practices to meet regulatory demands and consumer preferences.
- Market Diversification: Exploring new markets and product lines to reduce dependence on single segments.
Another critical strategy is the accelerated adoption of advanced manufacturing technologies. Industry 4.0 concepts, including automation, the Internet of Things (IoT), and artificial intelligence, are no longer just buzzwords but essential tools for enhancing productivity, reducing costs, and improving product quality. These technologies enable greater customization, faster time-to-market, and more efficient resource utilization. Furthermore, manufacturers are increasingly focusing on sustainability, not just as a compliance measure, but as a core business strategy that can drive innovation, attract environmentally conscious consumers, and reduce long-term operational costs. By integrating these multi-faceted strategies, manufacturers can better navigate the complexities highlighted by the PMI report and secure a competitive edge in the evolving global industrial landscape.
Analyzing Regional Variations in Industrial Output
While the national October 2026 Manufacturing PMI provides an overarching view, it’s crucial to acknowledge the significant regional variations within the US industrial output. The economic landscape is not monolithic, and different regions often exhibit distinct strengths, challenges, and growth trajectories, influenced by local industries, labor markets, and infrastructure. A deeper dive into these regional nuances offers a more granular understanding of the nation’s manufacturing health.
For instance, states with a strong presence in technology and advanced manufacturing, such as parts of the West Coast and Northeast, might show more robust growth in new orders and production, driven by innovation and high-tech demand. Conversely, regions heavily reliant on traditional heavy industries or those facing demographic shifts could experience slower expansion or even contraction in certain sub-indices. These regional disparities often reflect specialized industrial ecosystems and varying degrees of resilience to global economic shifts.
Regional Performance Snapshots
- Midwest: Strong in automotive and machinery, showing steady but moderate growth, sensitive to global trade.
- Northeast: Focus on pharmaceuticals and specialized electronics, indicating consistent demand and innovation-driven output.
- Southeast: Expanding in aerospace and textiles, attracting new investment but facing labor supply challenges.
- Southwest: Growth in semiconductor manufacturing and renewable energy components, benefiting from federal incentives.
Understanding these regional differences is vital for both national policymakers and local businesses. For policymakers, it informs targeted economic development programs and infrastructure investments. For manufacturers, it helps in strategic location decisions, talent acquisition, and market penetration strategies. The ability to disaggregate the national PMI data into regional insights allows for more precise forecasting and more effective resource allocation, recognizing that a rising tide does not necessarily lift all boats equally across the diverse manufacturing landscape of the United States. Therefore, a comprehensive analysis always includes a look at how different parts of the country are contributing to, and being affected by, the overall industrial trends.
| Key Aspect | Brief Description |
|---|---|
| Overall PMI Score | Indicates expansion or contraction in the manufacturing sector (above/below 50). |
| New Orders | Reflects current demand and future production expectations. |
| Supply Chain Health | Assessed through supplier delivery times and inventory levels. |
| Economic Impact | Influence on GDP, inflation, employment, and investment decisions. |
Frequently Asked Questions About Manufacturing PMI
What is the significance of the October 2026 Manufacturing PMI report?▼The October 2026 Manufacturing PMI is a vital economic indicator offering a real-time assessment of the US manufacturing sector’s health. It provides insights into production, new orders, employment, and inventories, helping businesses and policymakers understand economic trends and make informed decisions about investment and strategy.
How is the Manufacturing PMI calculated?▼The Manufacturing PMI is derived from a survey of purchasing managers, who report on five key areas: new orders, production, employment, supplier deliveries, and inventories. Each component is weighted, and a diffusion index is created. A reading above 50 signifies expansion, while below 50 indicates contraction.
What do changes in new orders and production indicate?▼An increase in new orders typically signals growing demand for manufactured goods, often leading to higher production levels in subsequent months. Conversely, a decline suggests softening demand. These components are critical for forecasting future industrial output and economic activity.
How does the PMI affect investment decisions?▼Investors closely monitor PMI data as it can influence stock market performance, particularly in industrial sectors. Positive PMI readings often boost investor confidence, signaling a healthy economy and potential for corporate growth, while negative readings can lead to caution and market adjustments.
What are the main challenges facing US manufacturers in late 2026?▼Manufacturers in late 2026 are primarily contending with ongoing supply chain complexities, persistent inflationary pressures, particularly in energy costs, and a tightening labor market. Geopolitical uncertainties also continue to pose risks to global trade and commodity prices, demanding adaptive strategies.
Conclusion
The October 2026 Manufacturing PMI: A Look at Industrial Output (RECENT UPDATES) underscores the dynamic and often challenging environment facing the US industrial sector. While the report indicates continued expansion, albeit at a potentially moderating pace, it also highlights the persistent influence of supply chain complexities, labor market dynamics, and geopolitical factors. Manufacturers are clearly navigating a landscape that demands agility, strategic investment in technology, and a renewed focus on resilience. The insights gleaned from this critical economic indicator will continue to serve as an indispensable guide for businesses and policymakers striving to foster sustainable growth and adapt to the evolving demands of the global economy. Understanding these trends is not merely an academic exercise; it is fundamental to shaping robust strategies for the future of American industry.